Market Summary
Executive Summary and Market Analysis
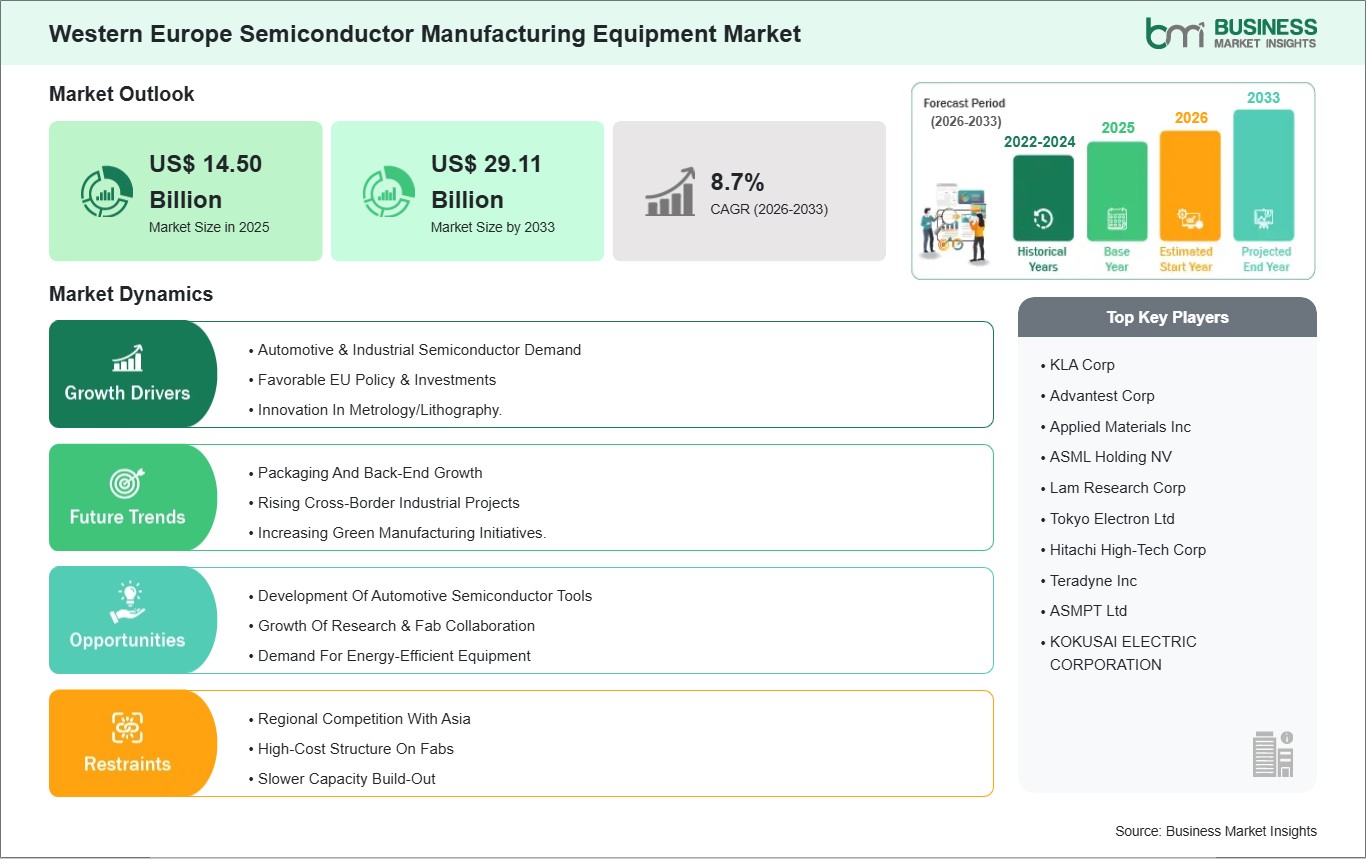
The Western Europe semiconductor manufacturing equipment market is poised for steady growth as regional foundries and global equipment suppliers invest in advanced process technologies and capacity expansion. Driven by increasing demand for high‑performance computing, automotive electronics, and industrial IoT applications, the market benefits from supportive governmental policies, particularly in Germany, the Netherlands, and France, aimed at strengthening local semiconductor ecosystems. Key players are focusing on EUV lithography, deposition systems, and etch technologies to enable sub‑7nm and next‑generation nodes, while sustainability and energy efficiency considerations influence capital equipment adoption. Despite competitive pressures from Asia‑Pacific and supply chain uncertainties, Western European manufacturers leverage strong R&D capabilities and collaborations between industry and academia to maintain technological relevance. Strategic partnerships, incentives under initiatives such as the EU’s Chips Act, and investments in workforce development are expected to enhance regional competitiveness. Overall, the market demonstrates resilience, with moderate CAGR projected over the next five years as demand for advanced semiconductors grows globally.
Segment Analysis
Western Europe Semiconductor Manufacturing Equipment Market Segmentation
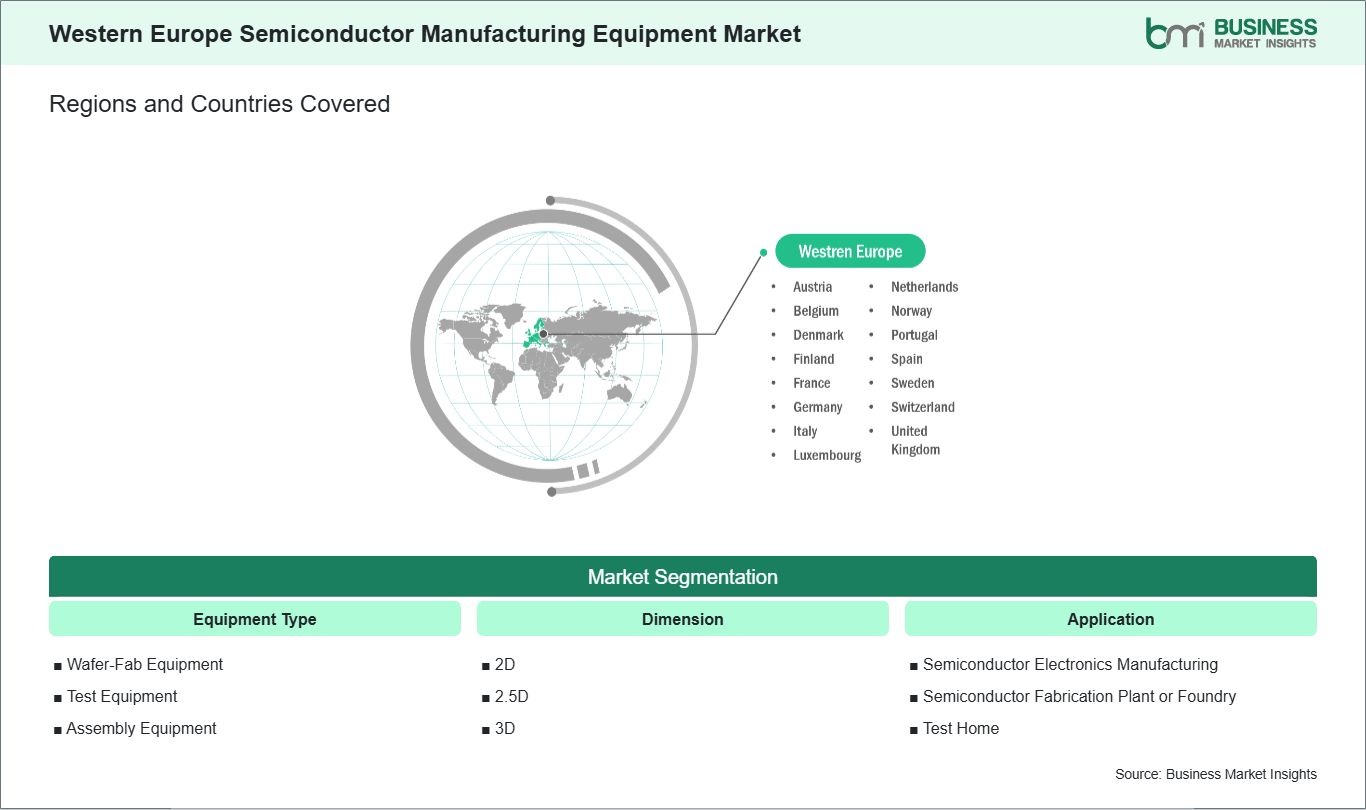
Key segments that contributed to the derivation of the Western Europe semiconductor manufacturing equipment market analysis are equipment type, dimension, and application.
- By equipment type, the Western Europe semiconductor manufacturing equipment market is bifurcated into wafer-fab equipment, test equipment, and assembly equipment. The wafer-fab equipment segment dominated the market in 2025.
- By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025.
- By application, the market is segmented into semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025.
Market Forces
Western Europe Semiconductor Manufacturing Equipment Market Drivers and Opportunities
Automotive Semiconductor Demand
The rapid electrification and digitalization of vehicles has made Western Europe a focal point in the global automotive semiconductor demand surge. With leading OEMs such as Volkswagen, BMW, and Stellantis accelerating production of electric vehicles (EVs), Advanced Driver‑Assistance Systems (ADAS), and connected car technologies, the need for high‑performance power, logic, and sensor semiconductors has grown substantially. European regulatory pressures on emissions and safety standards further compel automakers to integrate more sophisticated semiconductor‑enabled systems, from battery management to radar and lidar. This demand cascades directly into the semiconductor manufacturing equipment (SME) market as local fabs and foundries scale capacity, adopt cutting‑edge process nodes, and invest in high‑precision deposition, lithography, and inspection tools. Additionally, efforts to shorten supply chains in response to geopolitical shifts bolster regional semiconductor fabrication initiatives, enhancing long‑term equipment procurement and driving technological innovation specific to automotive grade components.
Industrial Semiconductor Demand
Industrial digital transformation across Western Europe has emerged as a powerful driver for semiconductor manufacturing equipment. Sectors such as automation, renewable energy, aerospace, and logistics increasingly depend on advanced semiconductors for robotics, intelligent sensors, programmable logic controllers (PLCs), and edge computing platforms. As manufacturers adopt Industry 4.0 principles—blending AI, IoT, and data analytics into factory operations—the demand for high‑reliability, low‑power, and high‑performance chips intensifies. This dynamic pushes regional foundries and global partners to expand fabrication capabilities to support diverse industrial applications. Consequently, investments in semiconductor manufacturing equipment—especially in wafer fabrication, precision etching, and yield enhancement technologies—rise to meet broader, more complex product portfolios. The result is a virtuous cycle: stronger industrial semiconductor demand accelerates SME spending, fosters innovation, and reinforces Western Europe’s competitiveness in high‑value manufacturing markets.
Size and Share Analysis
Western Europe Semiconductor Manufacturing Equipment Market Size and Share Analysis
By equipment type, the Western Europe semiconductor manufacturing equipment market is divided into wafer-fab equipment, assembly equipment, and test equipment. The wafer-fab equipment segment dominated the market in 2025. Western Europe demonstrates advanced wafer-fab equipment adoption, particularly in Germany, France, and the Netherlands. Emphasis is on microelectronics, automotive semiconductors, and clean technology, with state-backed programs supporting R&D, supply chain resilience, and high-tech industrial growth.
By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025. Western Europe shows mature 2D adoption across industrial automation, healthcare imaging, and smart retail. Strong emphasis on standardization, sustainability, and digital transformation drives consistent integration of 2D technologies into enterprise and public-sector operations.
By application, the market is segmented semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025. Western Europe leads semiconductor adoption through advanced manufacturing, automotive electronics dominance, and strong research institutions. Government-backed innovation programs, sustainability requirements, and demand for industrial automation and electric vehicles drive continued investment in semiconductor production.
Report Coverage
Western Europe Semiconductor Manufacturing Equipment Market Report Coverage and Deliverables
The "Western Europe Semiconductor Manufacturing Equipment Market Size and Forecast (2022-2033)" report provides a detailed analysis of the market covering below areas:
- Western Europe semiconductor manufacturing equipment market size and forecast at regional, and country levels for all the key market segments covered under the scope
- Western Europe semiconductor manufacturing equipment market trends, as well as market dynamics such as drivers, restraints, and key opportunities
- Western Europe semiconductor manufacturing equipment market analysis covering key market trends, global and regional framework, major players, regulations, and recent market developments
- Industry landscape and competition analysis covering market concentration, heat map analysis, prominent players, and recent developments for the air circuit breaker market
- Detailed company profiles, including SWOT analysis
Geographic Insights
Western Europe Semiconductor Manufacturing Equipment Market Geographic Insights
The geographical scope of the Western Europe semiconductor manufacturing equipment market report is expected to grow significantly during the forecast period.
The demand for semiconductor manufacturing equipment in Western Europe is rising rapidly due to several interrelated factors. First, the growing adoption of advanced technologies such as artificial intelligence, 5G, electric vehicles, and the Internet of Things has significantly increased the need for high-performance chips, driving investment in semiconductor fabrication. Second, governments in countries like Germany, France, and the Netherlands are offering incentives and funding to strengthen local semiconductor production, aiming to reduce dependence on Asian suppliers and enhance supply chain resilience. Third, the push for energy-efficient and miniaturized electronic devices has created a need for state-of-the-art equipment capable of producing smaller, more powerful semiconductors with higher yields. Additionally, the rising trend of reshoring and nearshoring manufacturing operations encourages European fabs to upgrade their machinery to remain competitive. Collectively, these technological, strategic, and economic factors are fueling the expansion of the semiconductor manufacturing equipment market in Western Europe.
Industry Activity
Recent Developments
The Western Europe semiconductor manufacturing equipment market is evaluated by gathering qualitative and quantitative data post primary and secondary research, which includes important corporate publications, association data, and databases. A few of the key developments in the Western Europe semiconductor manufacturing equipment market are:
- For instance, on October, 2025, Applied Materials, Inc. introduced new semiconductor manufacturing systems that enhance the performance of advanced logic and memory chips, which are foundational to AI computing. The new products target three critical areas in the race to deliver ever more powerful AI chips: leading-edge logic including Gate-All-Around (GAA) transistors, high-performance DRAM including high-bandwidth memory (HBM), and advanced packaging to create highly integrated systems-in-a-package that optimize chip performance, power consumption and cost.
- For instance, in February 2025, Advantest Corporation announced that it had entered into a partnership agreement with Micronics Japan Co., Ltd. (“MJC”). As semiconductors are expected to become increasingly advanced and complex, close collaboration within the semiconductor supply chain is essential to meet future market demands. Under this agreement, MJC and Advantest will leverage their respective expertise to provide innovative semiconductor test solutions, contributing to the optimization of customers' test processes and test costs. Additionally, Advantest plans to acquire a minority stake in MJC as part of this agreement.
Trust & Transparency
Research Methodology
The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst
review.
View Full Research Methodology
Key Sources Referred:
World Bank - Global Trade Indicators World Trade Organization (WTO) International Monetary Fund (IMF) International Trade Administration (ITA) Company website Company annual reports Company investor presentations