Market Summary
Executive Summary and Market Analysis
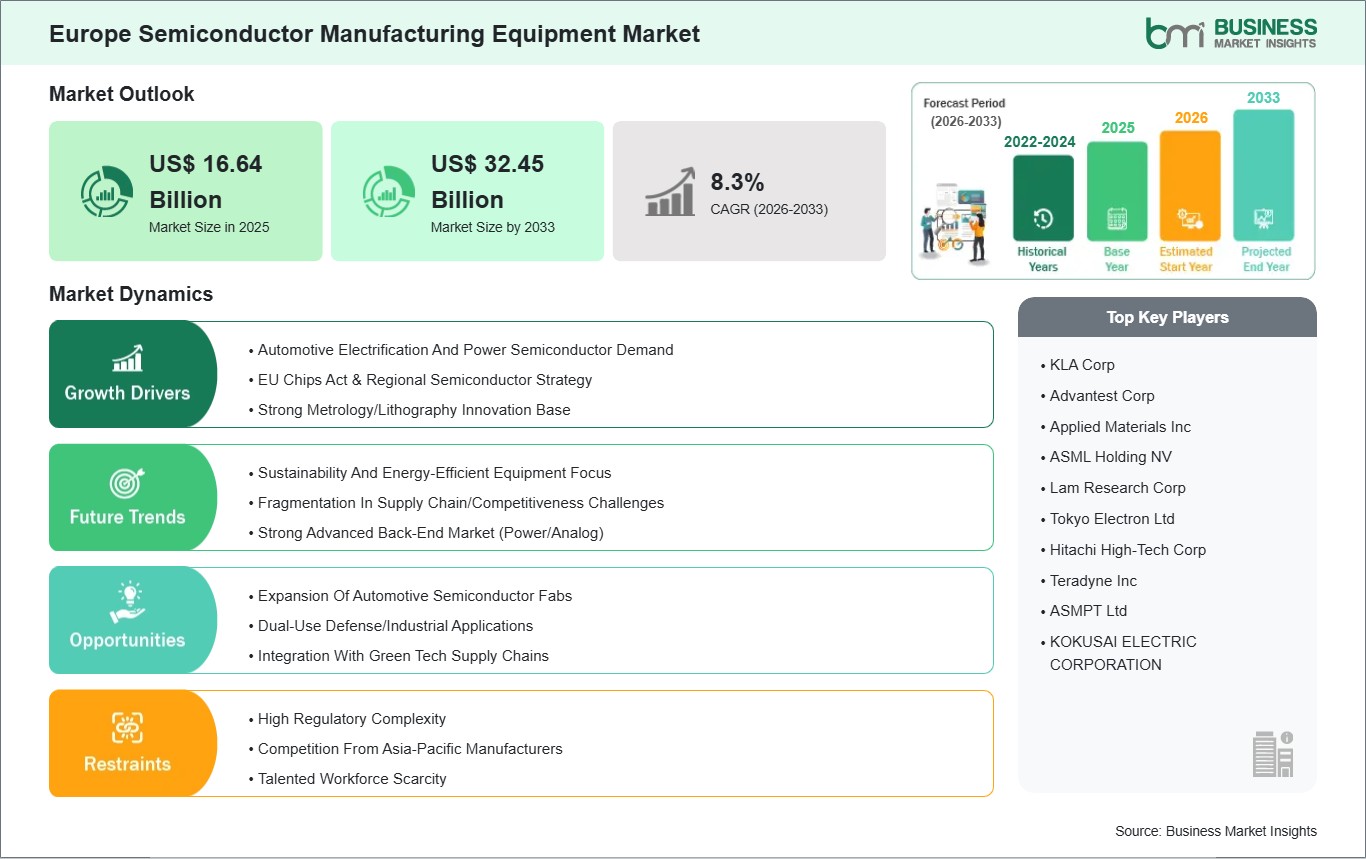
The Europe semiconductor manufacturing equipment market is emerging as a strategic growth frontier amid global supply chain realignment and increased technology investment across the continent. While Europe currently represents a small share of global semiconductor fabrication capacity, several countries are prioritizing infrastructure development, skills enhancement, and favorable industrial policies to attract semiconductor manufacturing and equipment deployment. Growing demand for consumer electronics, telecommunications infrastructure, automotive electronics, renewable energy systems, and digital services is driving the need for localized production capabilities and advanced manufacturing tools. Key market drivers include government incentives, foreign direct investments from Asian and Western technology firms, and partnerships aimed at technology transfer and workforce training. However, challenges such as limited existing fabrication facilities, inconsistent power supply, and the need for substantial capital investment remain significant. As ecosystem maturity advances through targeted policy support and investment ecosystems, Europe’s semiconductor manufacturing equipment market is poised for steady growth, offering opportunities for global equipment suppliers and regional technology development initiatives.
Segment Analysis
Europe Semiconductor Manufacturing Equipment Market Segmentation
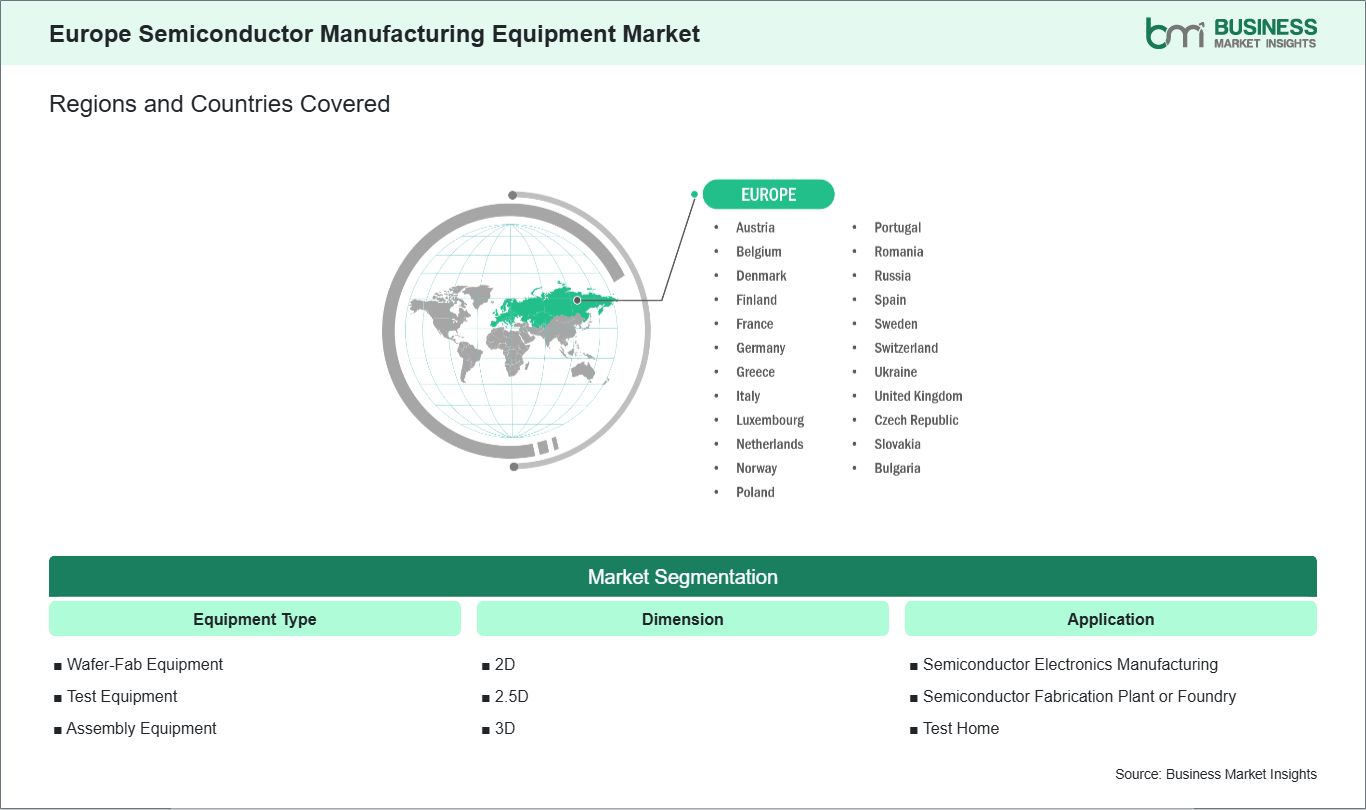
Key segments that contributed to the derivation of the Europe semiconductor manufacturing equipment market analysis are equipment type, dimension, and application.
- By equipment type, the Europe semiconductor manufacturing equipment market is bifurcated into wafer-fab equipment, test equipment, and assembly equipment. The wafer-fab equipment segment dominated the market in 2025.
- By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025.
- By application, the market is segmented into semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025.
Market Forces
Europe Semiconductor Manufacturing Equipment Market Drivers and Opportunities
Automotive Electrification and Power Semiconductor Demand
The rapid electrification of the automotive industry is a key driver of the semiconductor manufacturing equipment market in Europe. As governments accelerate bans on internal combustion engines and promote zero‑emission vehicles, automakers are redesigning platforms around electric powertrains. EVs require far more power semiconductors than traditional vehicles for functions such as inverters, onboard chargers, DC‑DC converters and traction control systems. This structural shift is triggering robust demand for advanced silicon carbide (SiC) and gallium nitride (GaN) devices, which deliver higher efficiency and performance at elevated voltages. European carmakers and tier‑1 suppliers are investing in localized chip supply chains to reduce dependence on external sources, strengthening investments into domestic fabrication and testing capacity. To support this, semiconductor manufacturing equipment suppliers are seeing increased orders for specialized deposition, etch and inspection tools tailored to power semiconductor production. The automotive electrification trend thus not only boosts semiconductor content per vehicle but directly expands the market for cutting‑edge SME technologies.
Expansion of Automotive Semiconductor Fabs
Europe’s strategic focus on strengthening its semiconductor sovereignty has opened a compelling opportunity in the expansion of automotive semiconductor fabrication facilities. With the EU and member governments offering incentives, funding programs such as the European Chips Act, and public‑private partnerships, automotive semiconductor fabs are being prioritized to secure supply for critical vehicle components. This localized builder boom reduces reliance on Asian supply chains and enables closer alignment between fab operators and regional automakers. For the semiconductor manufacturing equipment market, this translates into heightened demand for capital‑intensive fabrication tools—from advanced lithography and etch systems to metrology and wafer handling equipment. The push to manufacture high‑performance power devices like SiC and GaN on European soil further elevates the need for specialized SME gear capable of handling wide‑bandgap materials. As automotive fabs scale and new facilities emerge, equipment suppliers stand to benefit from long‑term service contracts, upgrades and recurring tool placements, making this expansion a significant growth lever for the region’s semiconductor equipment ecosystem.
Size and Share Analysis
Europe Semiconductor Manufacturing Equipment Market Size and Share Analysis
By equipment type, the Europe semiconductor manufacturing equipment market is divided into wafer-fab equipment, assembly equipment, and test equipment. The wafer-fab equipment segment dominated the market in 2025. Europe shows strong adoption of wafer-fab equipment, supported by advanced automotive electronics, industrial automation, and EU semiconductor initiatives that encourage local chip manufacturing, R&D investment, and supply-chain resilience across major technology hubs.
By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025. Europe demonstrates high 2D adoption through advanced manufacturing, healthcare imaging, and smart infrastructure. Strong regulatory frameworks and digital transformation initiatives drive widespread use of 2D technologies in automation, quality control, retail traceability, and research-driven innovation ecosystems.
By application, the market is segmented semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025. Europe has highly adopted semiconductor manufacturing through advanced fabrication, R&D leadership, and strong automotive and industrial electronics demand. Strategic public funding, sustainability-driven innovation, and resilient supply-chain policies strengthen Europe’s position in advanced chips and power semiconductors.
Report Coverage
Europe Semiconductor Manufacturing Equipment Market Report Coverage and Deliverables
The "Europe Semiconductor Manufacturing Equipment Market Size and Forecast (2022-2033)" report provides a detailed analysis of the market covering below areas:
- Europe semiconductor manufacturing equipment market size and forecast at regional and country levels for all the key market segments covered under the scope
- Europe semiconductor manufacturing equipment market trends, as well as market dynamics such as drivers, restraints, and key opportunities
- Europe semiconductor manufacturing equipment market analysis covering key market trends, global and regional framework, major players, regulations, and recent market developments
- Industry landscape and competition analysis covering market concentration, heat map analysis, prominent players, and recent developments for the air circuit breaker market
- Detailed company profiles, including SWOT analysis
Geographic Insights
Europe Semiconductor Manufacturing Equipment Market Geographic Insights
The geographical scope of the Europe semiconductor manufacturing equipment market report is expected to grow significantly during the forecast period.
The demand for semiconductor manufacturing equipment in Europe is rising due to the rapid adoption of advanced technologies such as artificial intelligence, 5G, electric vehicles, and the Internet of Things has intensified the need for high-performance semiconductors, driving manufacturers to expand production capacities. Second, Europe’s strategic initiatives, including the European Union’s “Digital Compass” and the European Chips Act, aim to strengthen domestic semiconductor production, reducing dependence on imports and enhancing supply chain resilience. Third, rising investments in research and development, coupled with government incentives, encourage companies to upgrade fabrication facilities with state-of-the-art equipment. Additionally, the growing trend of localized chip manufacturing to support automotive, healthcare, and industrial electronics sectors further fuels equipment demand. Overall, technological advancements, supportive policies, and the drive for supply chain independence collectively contribute to the robust growth of Europe’s semiconductor manufacturing equipment market.
Industry Activity
Recent Developments
The Europe semiconductor manufacturing equipment market is evaluated by gathering qualitative and quantitative data post primary and secondary research, which includes important corporate publications, association data, and databases. A few of the key developments in the Europe semiconductor manufacturing equipment market are:
- For instance, on October, 2025, Applied Materials, Inc. introduced new semiconductor manufacturing systems that enhance the performance of advanced logic and memory chips, which are foundational to AI computing. The new products target three critical areas in the race to deliver ever more powerful AI chips: leading-edge logic including Gate-All-Around (GAA) transistors, high-performance DRAM including high-bandwidth memory (HBM), and advanced packaging to create highly integrated systems-in-a-package that optimize chip performance, power consumption and cost.
- For instance, in February 2025, Advantest Corporation announced that it had entered into a partnership agreement with Micronics Japan Co., Ltd. (“MJC”). As semiconductors are expected to become increasingly advanced and complex, close collaboration within the semiconductor supply chain is essential to meet future market demands. Under this agreement, MJC and Advantest will leverage their respective expertise to provide innovative semiconductor test solutions, contributing to the optimization of customers' test processes and test costs. Additionally, Advantest plans to acquire a minority stake in MJC as part of this agreement.
Trust & Transparency
Research Methodology
The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst
review.
View Full Research Methodology
Key Sources Referred:
World Bank - Global Trade Indicators World Trade Organization (WTO) International Monetary Fund (IMF) International Trade Administration (ITA) Company website Company annual reports Company investor presentations