Market Summary
Executive Summary and Market Analysis
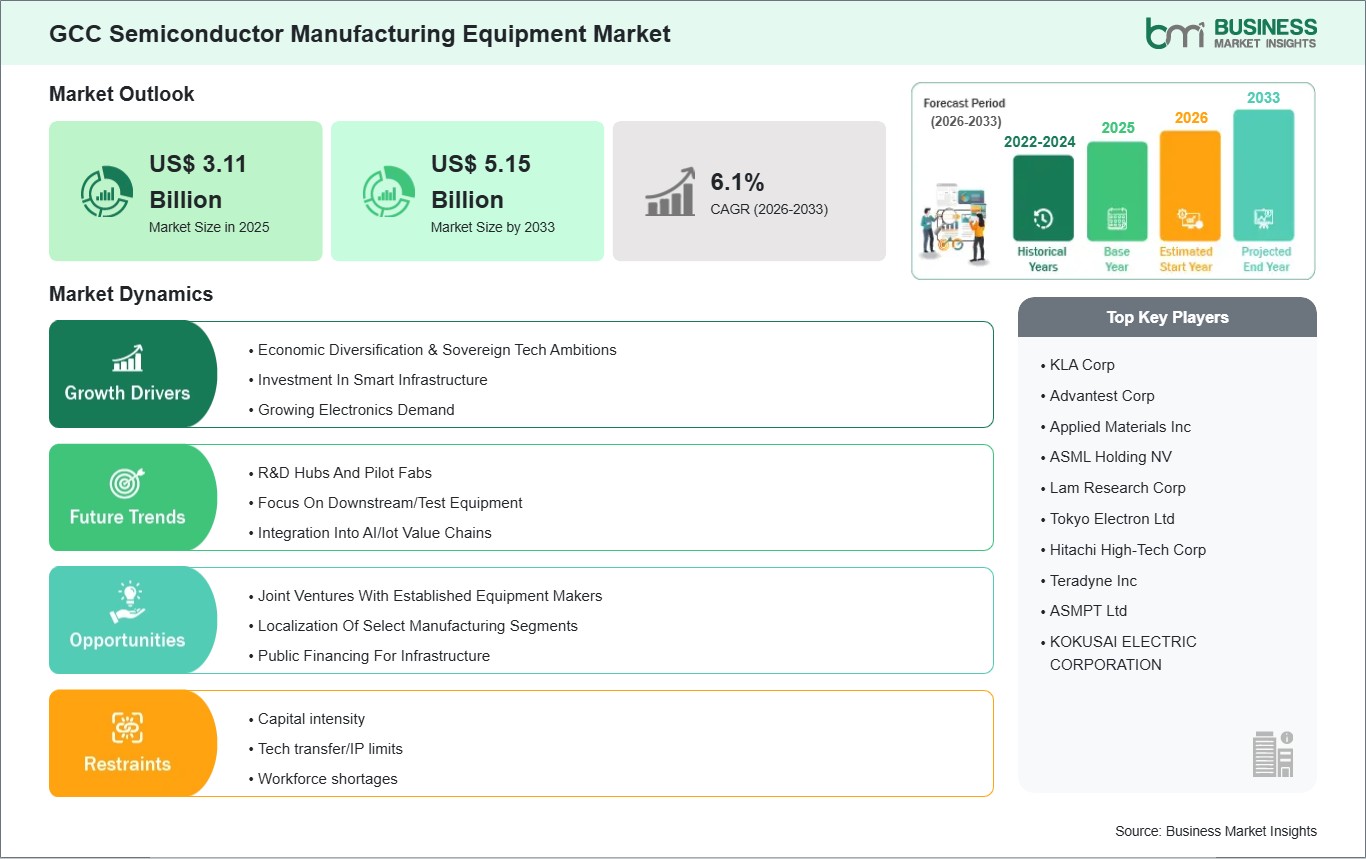
The GCC semiconductor manufacturing equipment market is emerging as a strategic growth frontier amid global supply chain realignment and increased technology investment across the continent. While GCC currently represents a small share of global semiconductor fabrication capacity, several countries are prioritizing infrastructure development, skills enhancement, and favorable industrial policies to attract semiconductor manufacturing and equipment deployment. Growing demand for consumer electronics, telecommunications infrastructure, automotive electronics, renewable energy systems, and digital services is driving the need for localized production capabilities and advanced manufacturing tools. Key market drivers include government incentives, foreign direct investments from Asian and Western technology firms, and partnerships aimed at technology transfer and workforce training. However, challenges such as limited existing fabrication facilities, inconsistent power supply, and the need for substantial capital investment remain significant. As ecosystem maturity advances through targeted policy support and investment ecosystems, GCC`s semiconductor manufacturing equipment market is poised for steady growth, offering opportunities for global equipment suppliers and regional technology development initiatives.
Segment Analysis
GCC Semiconductor Manufacturing Equipment Market Segmentation
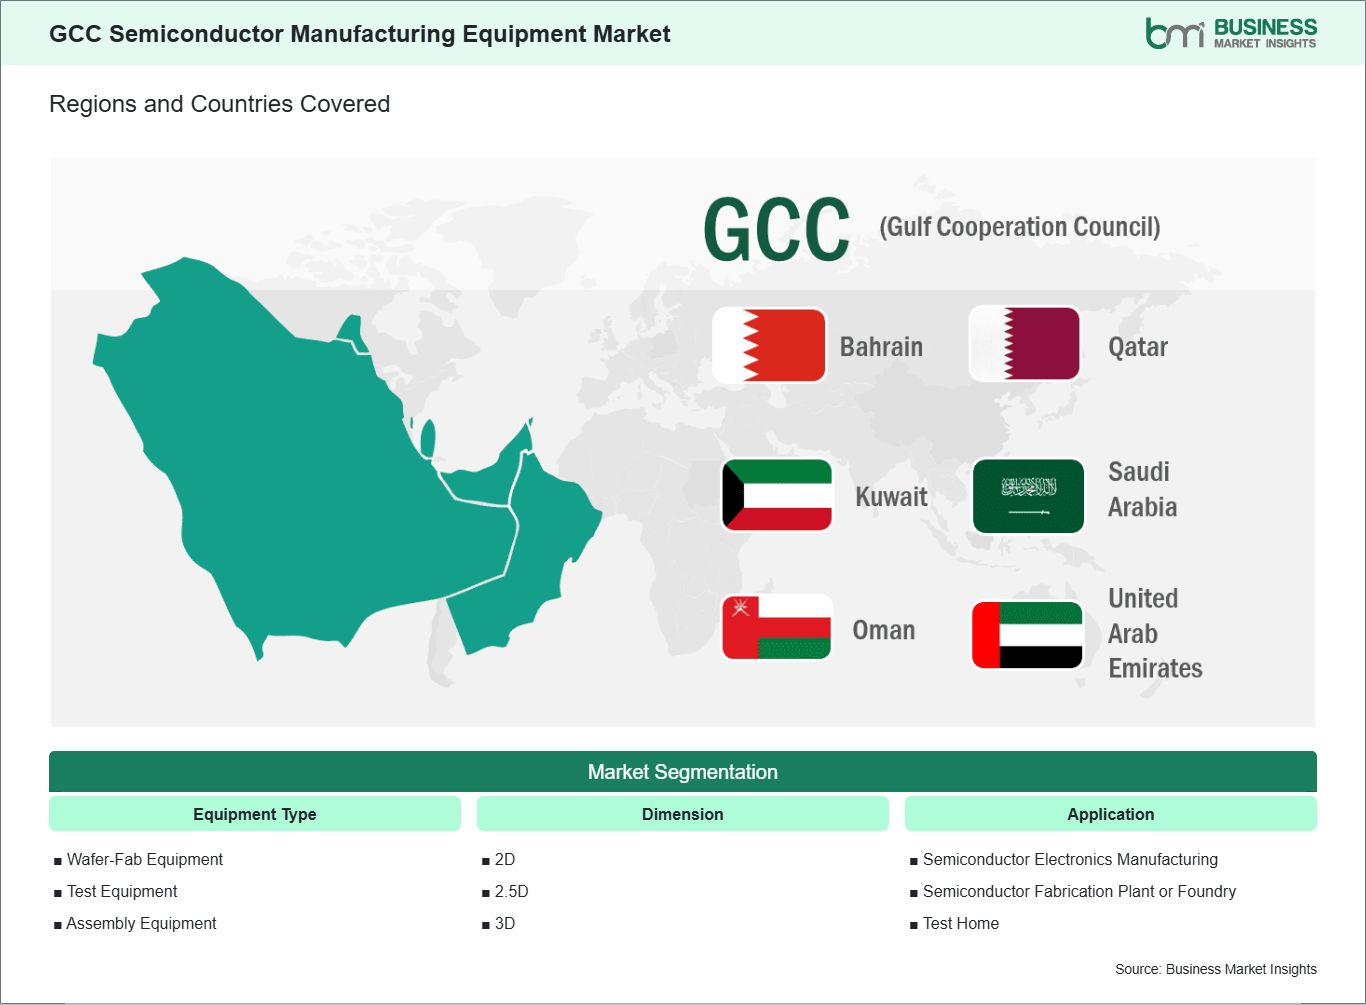
Key segments that contributed to the derivation of the GCC semiconductor manufacturing equipment market analysis are equipment type, dimension, and application.
- By equipment type, the GCC semiconductor manufacturing equipment market is bifurcated into wafer-fab equipment, test equipment, and assembly equipment. The wafer-fab equipment segment dominated the market in 2025.
- By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025.
- By application, the market is segmented into semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025.
Market Forces
GCC Semiconductor Manufacturing Equipment Market Drivers and Opportunities
Economic Diversification & Sovereign Tech Ambitions
Gulf states are aggressively diversifying away from hydrocarbon‑centric economies toward high‑value, knowledge‑based sectors, with semiconductors and advanced technology at the core of this transformation. Nations such as Saudi Arabia, the United Arab Emirates, Qatar, and others are investing in semiconductor ecosystems to reduce dependency on oil revenues, create sustainable employment, and build competitive domestic industries that contribute to GDP growth far beyond energy exports. Semiconductor manufacturing equipment is crucial for establishing and scaling fabrication facilities, advanced packaging lines, and test centers - components vital for a complete chip‑making value chain. This strategic shift aligns with broader sovereign ambitions to secure technological independence and resilience against global supply chain shocks, empowering these countries to participate meaningfully in global innovation networks. Such ambitions are supported by national initiatives like Saudi Vision 2030’s semiconductor programs and the UAE’s investment in GlobalFoundries and AI infrastructure, which collectively stimulate demand for cutting‑edge manufacturing equipment.
Joint Ventures With Established Equipment Makers
Collaborations between GCC governments and globally established semiconductor equipment manufacturers present a compelling opportunity to accelerate local industry maturity. By forming joint ventures and strategic partnerships with leading players in lithography, deposition, etching, metrology, and automation tools, GCC countries can expedite technology transfer, local skill development, and supply chain integration. Such collaborations reduce entry barriers for domestic fabs by providing access to proven expertise, state‑of‑the‑art technology, and specialized manufacturing systems that would otherwise take decades to develop indigenously. They also help bridge the talent gap by creating avenues for training and co‑innovation with global experts, addressing a key challenge for nascent semiconductor sectors in the region. Moreover, joint ventures can attract foreign direct investment, increase regional competitiveness, and integrate the GCC into global semiconductor supply networks. With interest from major players in establishing regional facilities and cooperation zones, this opportunity enhances the GCC’s ability to sustain long‑term semiconductor equipment demand while fostering an ecosystem conducive to research, production, and export.
Size and Share Analysis
GCC Semiconductor Manufacturing Equipment Market Size and Share Analysis
By equipment type, the GCC semiconductor manufacturing equipment market is divided into wafer-fab equipment, assembly equipment, and test equipment. The wafer-fab equipment segment dominated the market in 2025. In the GCC, wafer-fab equipment adoption is emerging as countries invest in smart manufacturing and digital economy initiatives. Saudi Arabia, UAE, and Qatar are establishing semiconductor clusters, relying on cutting-edge equipment to support automotive, defense, and renewable energy technology development.
By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025. The GCC region leads 2D adoption through smart city initiatives, digital governance, and advanced infrastructure investments. 2D technologies are widely used in construction, transportation, security, healthcare imaging, and retail digitization, supported by strong government-led digital transformation strategies.
By application, the market is segmented semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025. The GCC region is accelerating semiconductor adoption by investing in high-tech manufacturing, smart cities, and defense electronics. Government-led diversification strategies, strong capital availability, and demand for AI, IoT, and data centers support growing electronics production ecosystems.
Report Coverage
GCC Semiconductor Manufacturing Equipment Market Report Coverage and Deliverables
The "GCC Semiconductor Manufacturing Equipment Market Size and Forecast (2022-2033)" report provides a detailed analysis of the market covering below areas:
- GCC semiconductor manufacturing equipment market size and forecast at regional, and country levels for all the key market segments covered under the scope
- GCC semiconductor manufacturing equipment market trends, as well as market dynamics such as drivers, restraints, and key opportunities
- GCC semiconductor manufacturing equipment market analysis covering key market trends, global and regional framework, major players, regulations, and recent market developments
- Industry landscape and competition analysis covering market concentration, heat map analysis, prominent players, and recent developments for the air circuit breaker market
- Detailed company profiles, including SWOT analysis
Geographic Insights
GCC Semiconductor Manufacturing Equipment Market Geographic Insights
The geographical scope of the GCC semiconductor manufacturing equipment market report is expected to grow significantly during the forecast period.
The demand for semiconductor manufacturing equipment in the GCC (Gulf Cooperation Council) region is rising rapidly due to several interrelated factors. First, the GCC countries are increasingly investing in advanced technology and digital infrastructure as part of their economic diversification strategies, reducing dependence on oil revenues. This has led to growing initiatives in electronics, AI, automotive, and renewable energy sectors, all of which require semiconductors. Second, the global chip shortage highlighted the need for local semiconductor production, prompting governments in the region to develop semiconductor fabrication facilities and attract international manufacturers. Third, strong government support through subsidies, incentives, and strategic partnerships is encouraging private companies to expand semiconductor capabilities. Additionally, rising consumer demand for smart devices, 5G technology, and electric vehicles in the GCC further drives the need for semiconductors. Collectively, these factors create a robust growth environment for the semiconductor manufacturing equipment market in the region.
Industry Activity
Recent Developments
The GCC semiconductor manufacturing equipment market is evaluated by gathering qualitative and quantitative data post primary and secondary research, which includes important corporate publications, association data, and databases. A few of the key developments in the GCC semiconductor manufacturing equipment market are:
- For instance, on October, 2025, Applied Materials, Inc. introduced new semiconductor manufacturing systems that enhance the performance of advanced logic and memory chips, which are foundational to AI computing. The new products target three critical areas in the race to deliver ever more powerful AI chips: leading-edge logic including Gate-All-Around (GAA) transistors, high-performance DRAM including high-bandwidth memory (HBM), and advanced packaging to create highly integrated systems-in-a-package that optimize chip performance, power consumption and cost.
- For instance, in February 2025, Advantest Corporation announced that it had entered into a partnership agreement with Micronics Japan Co., Ltd. (“MJC”). As semiconductors are expected to become increasingly advanced and complex, close collaboration within the semiconductor supply chain is essential to meet future market demands. Under this agreement, MJC and Advantest will leverage their respective expertise to provide innovative semiconductor test solutions, contributing to the optimization of customers' test processes and test costs. Additionally, Advantest plans to acquire a minority stake in MJC as part of this agreement.
Trust & Transparency
Research Methodology
The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst
review.
View Full Research Methodology
Key Sources Referred:
World Bank - Global Trade Indicators World Trade Organization (WTO) International Monetary Fund (IMF) International Trade Administration (ITA) Company website Company annual reports Company investor presentations