Market Summary
Executive Summary and Market Analysis
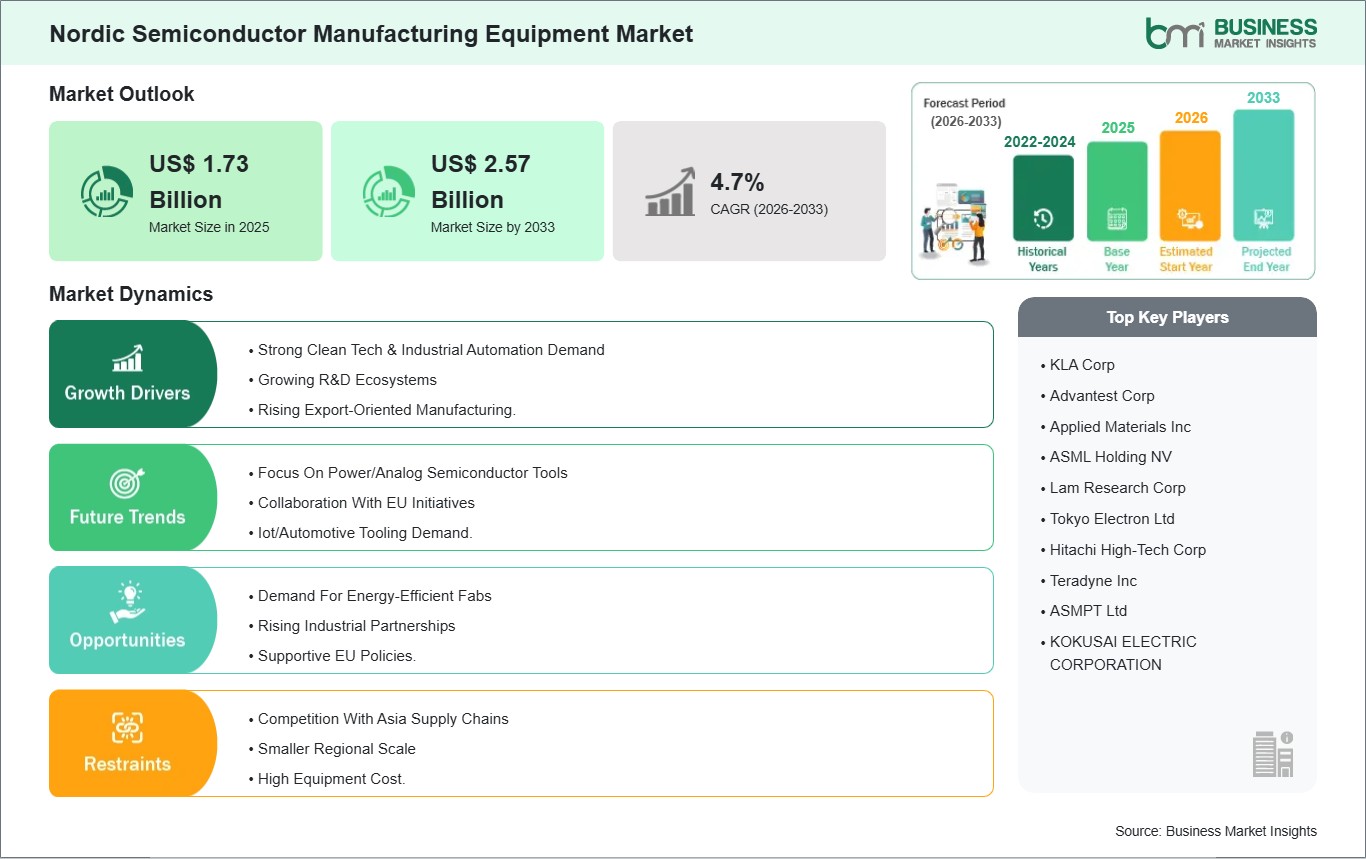
The Nordic semiconductor manufacturing equipment market has emerged as a strategic hub for advanced electronics production, driven by strong regional investments in technology infrastructure, R&D, and industry collaborations. Key Nordic countries such as Sweden, Finland, and Norway leverage a highly skilled workforce, robust innovation ecosystems, and proximity to leading global semiconductor manufacturers, attracting suppliers of lithography, etching, and inspection systems. The market is characterized by a growing emphasis on sustainable and energy‑efficient equipment, reflecting Nordic commitments to environmental stewardship and circular economy principles. Continued public and private funding initiatives are accelerating development of specialized equipment for next‑generation semiconductors, including components for automotive, IoT, and 5G applications. However, supply chain dependencies and global competition present challenges that require strategic partnerships and capacity expansion. Overall, the Nordic semiconductor equipment market shows promising growth potential, anchored by technological expertise, policy support, and alignment with global semiconductor trends, positioning the region as a competitive player in advanced manufacturing.
Segment Analysis
Nordic Semiconductor Manufacturing Equipment Market Segmentation
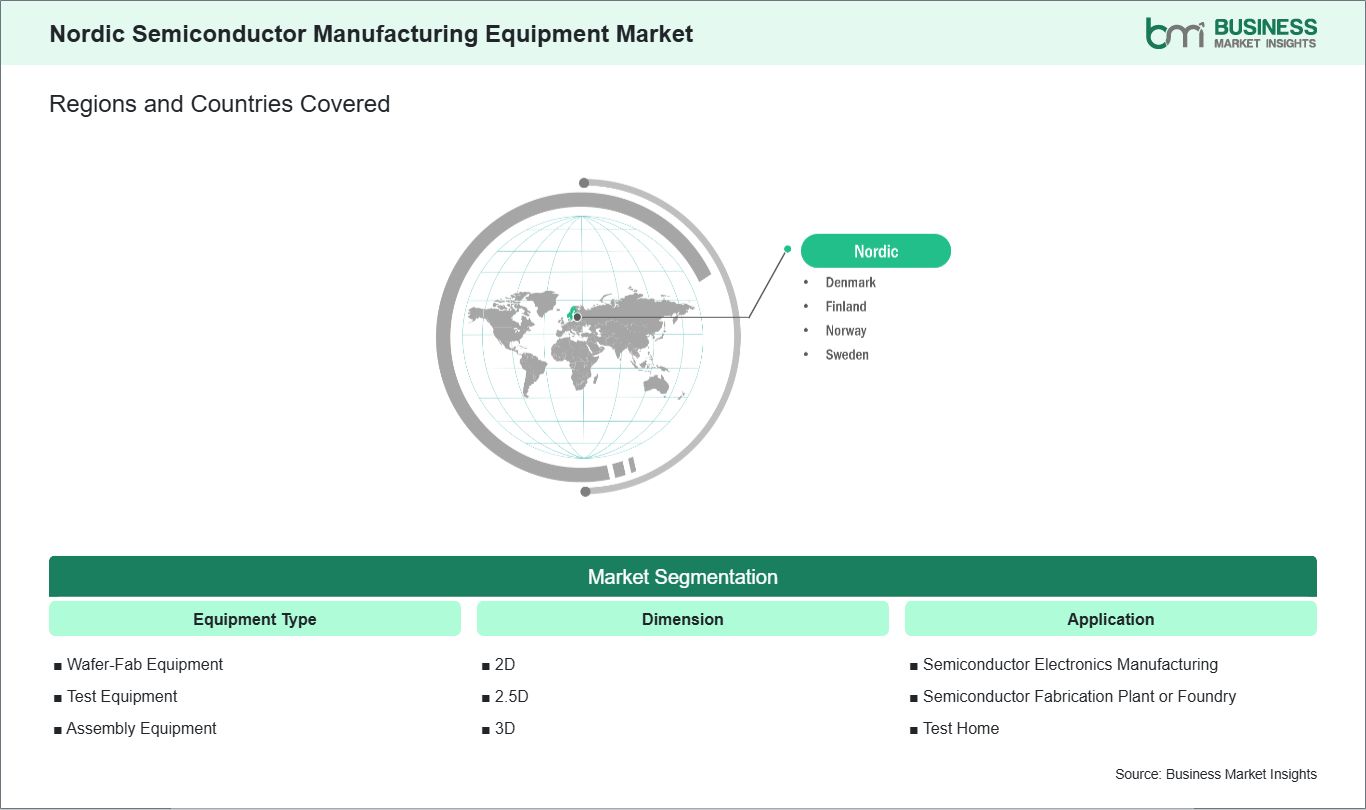
Key segments that contributed to the derivation of the Nordic semiconductor manufacturing equipment market analysis are equipment type, dimension, and application.
- By equipment type, the Nordic semiconductor manufacturing equipment market is bifurcated into wafer-fab equipment, test equipment, and assembly equipment. The wafer-fab equipment segment dominated the market in 2025.
- By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025.
- By application, the market is segmented into semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025.
Market Forces
Nordic Semiconductor Manufacturing Equipment Market Drivers and Opportunities
Strong Clean Tech & Industrial Automation Demand
The Nordic region’s leadership in clean technology and industrial automation is a significant driver for growth in the semiconductor manufacturing equipment market. Nordic countries like Sweden, Finland, Denmark, and Norway have robust environmental and sustainability policies that encourage investment in energy‑efficient, low‑emission technologies across industries. This clean tech emphasis translates into higher demand for semiconductor devices used in renewable energy systems, smart grid controls, and sustainable manufacturing—boosting demand for advanced semiconductor production tools that enable precise, efficient fabrication. Additionally, the Nordic industrial base increasingly integrates automation, robotics, and digital control systems to enhance productivity and reduce energy intensity, directly increasing the need for automation‑ready semiconductor manufacturing equipment, including metrology, deposition, and automated process control tools. As the region pushes toward carbon‑neutral industry targets, fab equipment suppliers that can deliver high precision with reduced environmental impact are particularly well‑positioned for growth.
Demand for Energy Efficient Fabs
The Nordic market presents a clear opportunity in the rising demand for energy‑efficient fabs that support sustainable semiconductor manufacturing. Semiconductor fabrication is inherently energy intensive, and manufacturers globally—especially in Europe and the Nordics—are prioritizing equipment that reduces energy consumption and aligns with regional sustainability goals. Nordic governments and research institutions emphasize green industrial practices, which accelerates adoption of energy‑efficient tools and processes in pilot fabs and research facilities. Semiconductor manufacturing equipment that incorporates features such as lower power consumption, optimized thermal management, and advanced process controls helps fabs minimize operating costs while meeting strict environmental standards. Europe’s broader focus on sustainability in fab infrastructure highlights the importance of equipment aligned with energy‑efficient production, further incentivizing Nordic fabs to invest in cutting‑edge, eco‑optimized manufacturing systems. This trend not only enhances regional competitiveness but also opens avenues for suppliers specializing in sustainable semiconductor equipment.
Size and Share Analysis
Nordic Semiconductor Manufacturing Equipment Market Size and Share Analysis
By equipment type, the Nordic semiconductor manufacturing equipment market is divided into wafer-fab equipment, assembly equipment, and test equipment. The wafer-fab equipment segment dominated the market in 2025. Nordic countries, including Sweden, Finland, and Denmark, adopt wafer-fab equipment to support their high-tech, telecommunications, and clean-energy sectors. Investment emphasizes precision manufacturing, automation, and sustainable processes, often in collaboration with European semiconductor consortia.
By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025. Nordic countries demonstrate advanced 2D adoption supported by digital maturity, sustainability goals, and innovation-driven economies. 2D technologies are widely used in healthcare imaging, smart manufacturing, logistics optimization, and public services enabled by strong data infrastructure.
By application, the market is segmented semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025. The Nordic region demonstrates strong semiconductor adoption driven by innovation in power electronics, automotive systems, and renewable energy technologies. High R&D intensity, sustainability focus, and advanced manufacturing capabilities position the region as a leader in specialized semiconductor applications.
Report Coverage
Nordic Semiconductor Manufacturing Equipment Market Report Coverage and Deliverables
The "Nordic Semiconductor Manufacturing Equipment Market Size and Forecast (2022-2033)" report provides a detailed analysis of the market covering below areas:
- Nordic semiconductor manufacturing equipment market size and forecast at regional, and country levels for all the key market segments covered under the scope
- Nordic semiconductor manufacturing equipment market trends, as well as market dynamics such as drivers, restraints, and key opportunities
- Nordic semiconductor manufacturing equipment market analysis covering key market trends, global and regional framework, major players, regulations, and recent market developments
- Industry landscape and competition analysis covering market concentration, heat map analysis, prominent players, and recent developments for the air circuit breaker market
- Detailed company profiles, including SWOT analysis
Geographic Insights
Nordic Semiconductor Manufacturing Equipment Market Geographic Insights
The geographical scope of the Nordic semiconductor manufacturing equipment market report is expected to grow significantly during the forecast period.
The demand for semiconductor manufacturing equipment in the Nordic region is rising sharply due to several interlinked factors. First, the increasing adoption of advanced technologies such as 5G, artificial intelligence, and electric vehicles is driving a surge in semiconductor consumption, which in turn fuels the need for cutting-edge fabrication equipment. Second, Nordic countries are emphasizing technological self-reliance and strengthening their local semiconductor supply chains, prompting investments in domestic production facilities. Additionally, government incentives and funding initiatives aimed at promoting high-tech manufacturing have encouraged companies to expand their semiconductor fabrication capabilities. The growing presence of research and development hubs in Sweden, Finland, and Denmark further supports this trend, as these centers often require sophisticated tools for prototyping and small-scale production. Moreover, the global chip shortage has highlighted the importance of regional production, motivating Nordic firms to modernize and scale up their semiconductor manufacturing infrastructure, boosting equipment demand.
Industry Activity
Recent Developments
The Nordic semiconductor manufacturing equipment market is evaluated by gathering qualitative and quantitative data post primary and secondary research, which includes important corporate publications, association data, and databases. A few of the key developments in the Nordic semiconductor manufacturing equipment market are:
- For instance, on October, 2025, Applied Materials, Inc. introduced new semiconductor manufacturing systems that enhance the performance of advanced logic and memory chips, which are foundational to AI computing. The new products target three critical areas in the race to deliver ever more powerful AI chips: leading-edge logic including Gate-All-Around (GAA) transistors, high-performance DRAM including high-bandwidth memory (HBM), and advanced packaging to create highly integrated systems-in-a-package that optimize chip performance, power consumption and cost.
- For instance, in February 2025, Advantest Corporation announced that it had entered into a partnership agreement with Micronics Japan Co., Ltd. (“MJC”). As semiconductors are expected to become increasingly advanced and complex, close collaboration within the semiconductor supply chain is essential to meet future market demands. Under this agreement, MJC and Advantest will leverage their respective expertise to provide innovative semiconductor test solutions, contributing to the optimization of customers' test processes and test costs. Additionally, Advantest plans to acquire a minority stake in MJC as part of this agreement.
Trust & Transparency
Research Methodology
The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst
review.
View Full Research Methodology
Key Sources Referred:
World Bank - Global Trade Indicators World Trade Organization (WTO) International Monetary Fund (IMF) International Trade Administration (ITA) Company website Company annual reports Company investor presentations