Market Summary
Executive Summary and Market Analysis
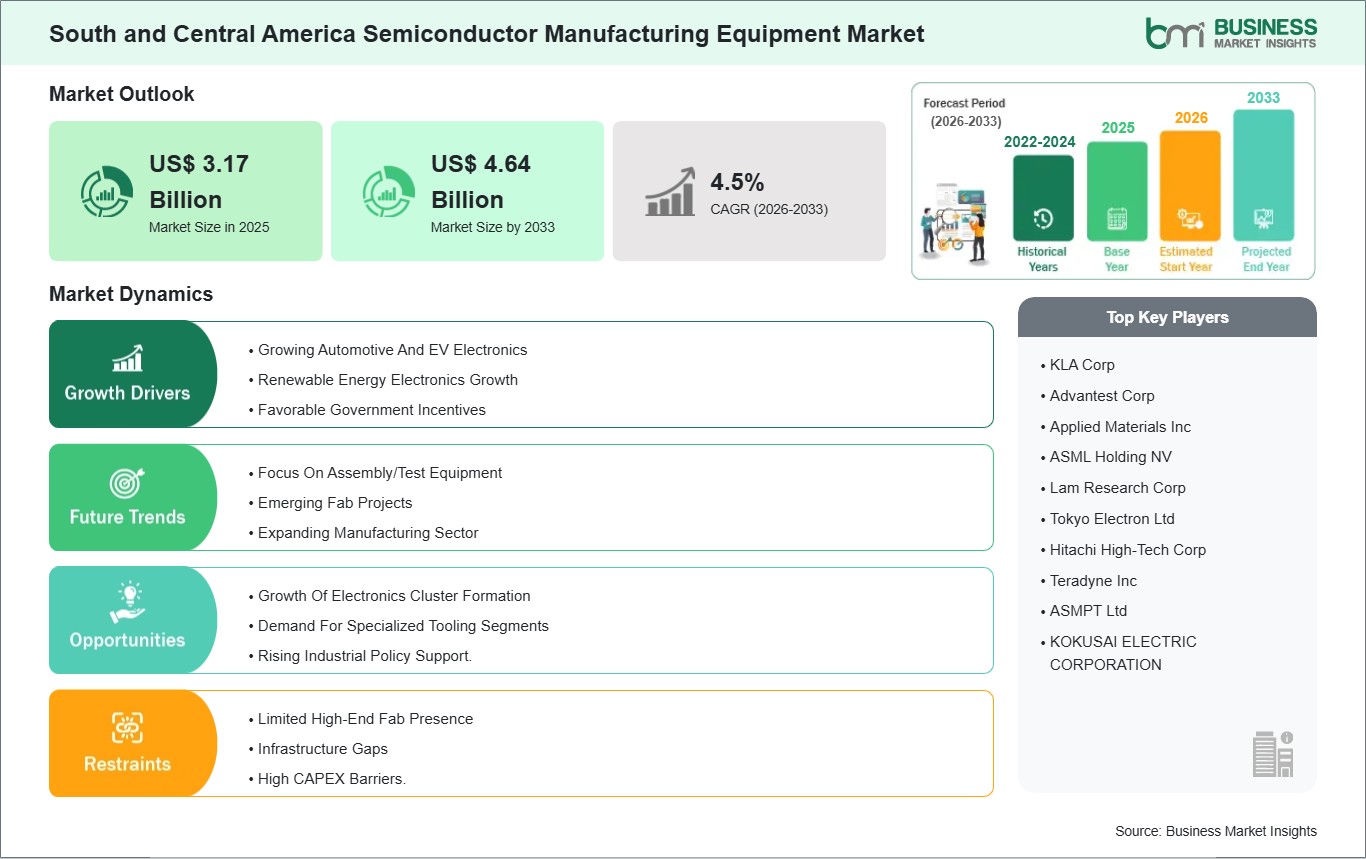
The South and Central America semiconductor manufacturing equipment market is positioned for sustained growth driven by rising regional demand for chips across AI, 5G, automotive, IoT, and cloud infrastructures, prompting investments in advanced fabrication and packaging tools. Government initiatives aimed at enhancing local semiconductor capabilities, coupled with strategic incentives and public‑private partnerships, are accelerating fab expansions and equipment procurement throughout the region. Key growth drivers include large‑scale foundry capacity buildouts, adoption of cutting‑edge etching, lithography, and metrology systems, and increased emphasis on yield optimization through modern inspection and process control technologies. Nevertheless, high capital intensity, lengthy lead times for advanced machinery, and persistent skilled labor shortages present significant barriers to rapid development. Supply chain dependencies on global suppliers and environmental compliance costs further complicate market dynamics. Despite these challenges, competitive participation by global equipment vendors and supportive policy frameworks indicate robust medium‑term market potential across South and Central America.
Segment Analysis
South and Central America Semiconductor Manufacturing Equipment Market Segmentation
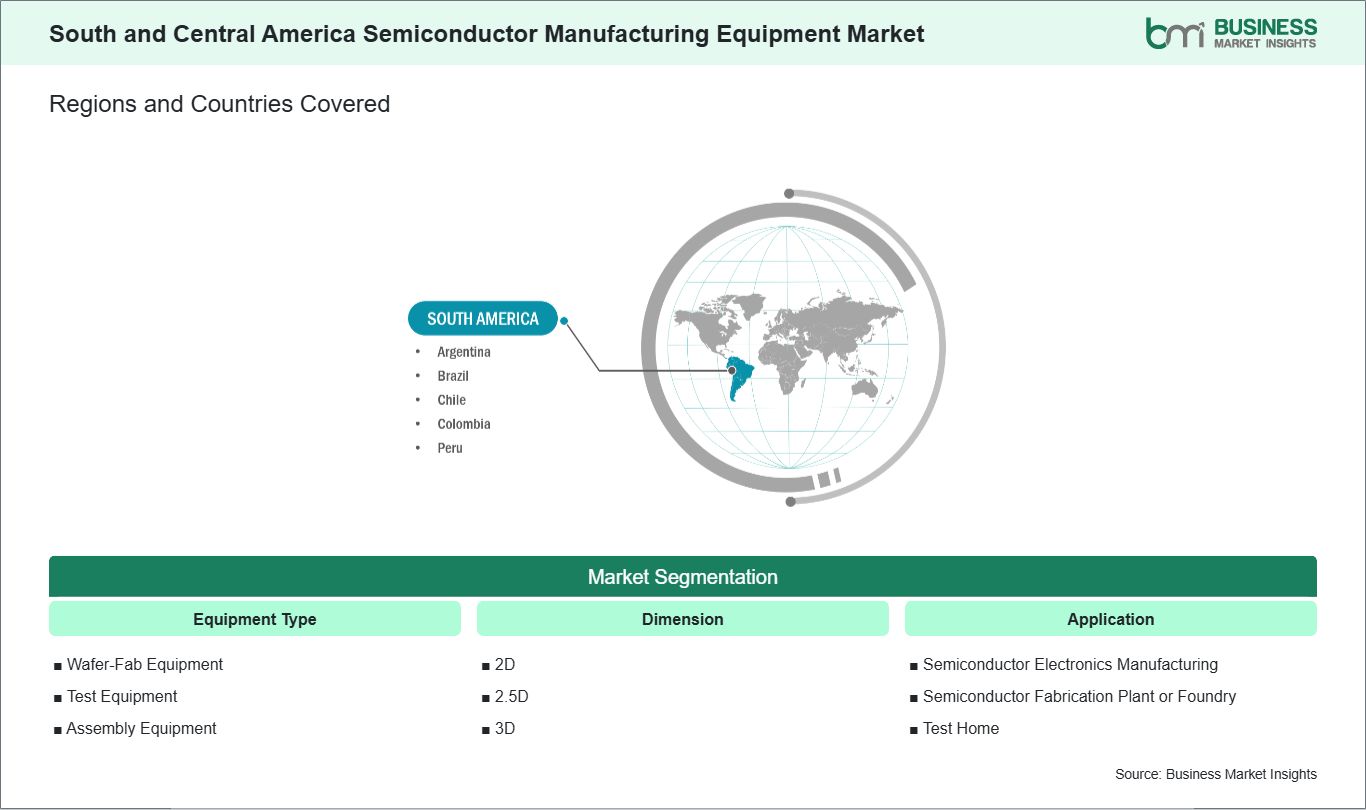
Key segments that contributed to the derivation of the South and Central America semiconductor manufacturing equipment market analysis are equipment type, dimension, and application.
- By equipment type, the South and Central America semiconductor manufacturing equipment market is bifurcated into wafer-fab equipment, test equipment, and assembly equipment. The wafer-fab equipment segment dominated the market in 2025.
- By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025.
- By application, the market is segmented into semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025.
Market Forces
South and Central America Semiconductor Manufacturing Equipment Market Drivers and Opportunities
Growing Automotive and EV Electronics
The booming automotive sector in South and Central America—particularly the rapid adoption of electric vehicles (EVs) and advanced driver‑assistance systems—is a key driver for the regional semiconductor manufacturing equipment market. Modern vehicles increasingly integrate electronic control units (ECUs), sensors, power management chips, and infotainment systems, all of which rely on sophisticated semiconductors. As legacy internal combustion engine vehicles give way to hybrid and fully electric models, demand for high‑performance power semiconductors (like IGBTs, SiC, and GaN devices) and integrated circuits for battery management, motor control, and connectivity has surged. Automakers and tier‑1 suppliers are investing in local supply chains to reduce import dependence, shorten lead times, and improve cost efficiency. Consequently, regional semiconductor fabs require cutting‑edge equipment for wafer fabrication, advanced packaging, and testing to support this automotive electronics growth. This alignment between automotive electronics demand and semiconductor production capabilities significantly stimulates investment in SME technologies across South and Central America.
Growth of Electronics Cluster Formation
The emergence and expansion of electronics cluster formation across South and Central America present a significant opportunity for the semiconductor manufacturing equipment market. Electronics clusters—geographically concentrated networks of semiconductor fabs, R&D centers, suppliers, and skilled labor pools—create an ecosystem that encourages collaboration, innovation, and economies of scale. Governments in the region are increasingly supporting such clusters through favorable policies, tax incentives, infrastructure development, and public‑private partnerships to attract foreign direct investment and domestic high‑tech manufacturing. As clusters mature, they stimulate demand for advanced manufacturing equipment, including lithography systems, deposition tools, etchers, and inspection and metrology technologies. These clusters also help build specialized talent pipelines and improve access to capital, reducing barriers for new fabrication facilities. Moreover, proximity to end markets in automotive, telecommunications, and consumer electronics further enhances the business case for localized semiconductor production. The resulting concentration of demand for SME tools accelerates technology adoption and positions South and Central America as an emerging hub in the global semiconductor value chain.
Size and Share Analysis
South and Central America Semiconductor Manufacturing Equipment Market Size and Share Analysis
By equipment type, the South and Central America semiconductor manufacturing equipment market is divided into wafer-fab equipment, assembly equipment, and test equipment. The wafer-fab equipment segment dominated the market in 2025. Adoption of wafer-fab equipment in South and Central America is limited but growing. Brazil and Mexico invest in semiconductor research and small-scale fabrication facilities, supported by incentives and international partnerships, aiming to strengthen domestic production and reduce dependence on imports.
By dimension, the market is segmented into 2D, 2.5D, and 3D. The 2D segment held the largest share of the market in 2025. South and Central America increasingly adopt 2D technologies to modernize logistics, healthcare, and retail sectors. Mobile-enabled solutions and digital trade initiatives accelerate 2D usage, improving operational efficiency and accessibility across diverse and rapidly growing markets.
By application, the market is segmented semiconductor electronics manufacturing, semiconductor fabrication plant/foundry, and test home. The semiconductor electronics manufacturing segment held the largest share of the market in 2025. South and Central America are expanding semiconductor electronics manufacturing via assembly, testing, and electronics integration. Growing industrial automation, automotive production, and consumer electronics demand, alongside regional trade agreements, are supporting increased adoption across manufacturing value chains.
Report Coverage
South and Central America Semiconductor Manufacturing Equipment Market Report Coverage and Deliverables
The "South and Central America Semiconductor Manufacturing Equipment Market Size and Forecast (2022-2033)" report provides a detailed analysis of the market covering below areas:
- South and Central America semiconductor manufacturing equipment market size and forecast at regional, and country levels for all the key market segments covered under the scope
- South and Central America semiconductor manufacturing equipment market trends, as well as market dynamics such as drivers, restraints, and key opportunities
- South and Central America semiconductor manufacturing equipment market analysis covering key market trends, global and regional framework, major players, regulations, and recent market developments
- Industry landscape and competition analysis covering market concentration, heat map analysis, prominent players, and recent developments for the air circuit breaker market
- Detailed company profiles, including SWOT analysis
Geographic Insights
South and Central America Semiconductor Manufacturing Equipment Market Geographic Insights
The geographical scope of the South and Central America semiconductor manufacturing equipment market report is expected to grow significantly during the forecast period.
The demand for semiconductor manufacturing equipment in South and Central America is rising due to several key factors. Rapid digital transformation across industries—such as telecommunications, automotive, healthcare, and consumer electronics—is accelerating the need for local semiconductor production capabilities to support advanced technologies like 5G, AI, and IoT. Governments in the region are increasingly implementing policies and incentives to attract foreign direct investment and strengthen their tech ecosystems, which encourages semiconductor fabrication facilities to establish or expand operations locally. Additionally, global supply chain disruptions highlighted vulnerabilities in reliance on overseas production, prompting companies to diversify manufacturing bases and reduce risks by investing in regional fabrication infrastructure. Increasing demand for data centers and energy-efficient computing solutions is further propelling investment in advanced chips and, consequently, the equipment required to produce them. Combined with workforce skill development and international partnerships, these trends are driving significant growth in the semiconductor manufacturing equipment market across South and Central America.
Industry Activity
Recent Developments
The South and Central America semiconductor manufacturing equipment market is evaluated by gathering qualitative and quantitative data post primary and secondary research, which includes important corporate publications, association data, and databases. A few of the key developments in the South and Central America semiconductor manufacturing equipment market are:
- For instance, on October, 2025, Applied Materials, Inc. introduced new semiconductor manufacturing systems that enhance the performance of advanced logic and memory chips, which are foundational to AI computing. The new products target three critical areas in the race to deliver ever more powerful AI chips: leading-edge logic including Gate-All-Around (GAA) transistors, high-performance DRAM including high-bandwidth memory (HBM), and advanced packaging to create highly integrated systems-in-a-package that optimize chip performance, power consumption and cost.
- For instance, in February 2025, Advantest Corporation announced that it had entered into a partnership agreement with Micronics Japan Co., Ltd. (“MJC”). As semiconductors are expected to become increasingly advanced and complex, close collaboration within the semiconductor supply chain is essential to meet future market demands. Under this agreement, MJC and Advantest will leverage their respective expertise to provide innovative semiconductor test solutions, contributing to the optimization of customers' test processes and test costs. Additionally, Advantest plans to acquire a minority stake in MJC as part of this agreement.
Trust & Transparency
Research Methodology
The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst
review.
View Full Research Methodology
Key Sources Referred:
World Bank - Global Trade Indicators World Trade Organization (WTO) International Monetary Fund (IMF) International Trade Administration (ITA) Company website Company annual reports Company investor presentations