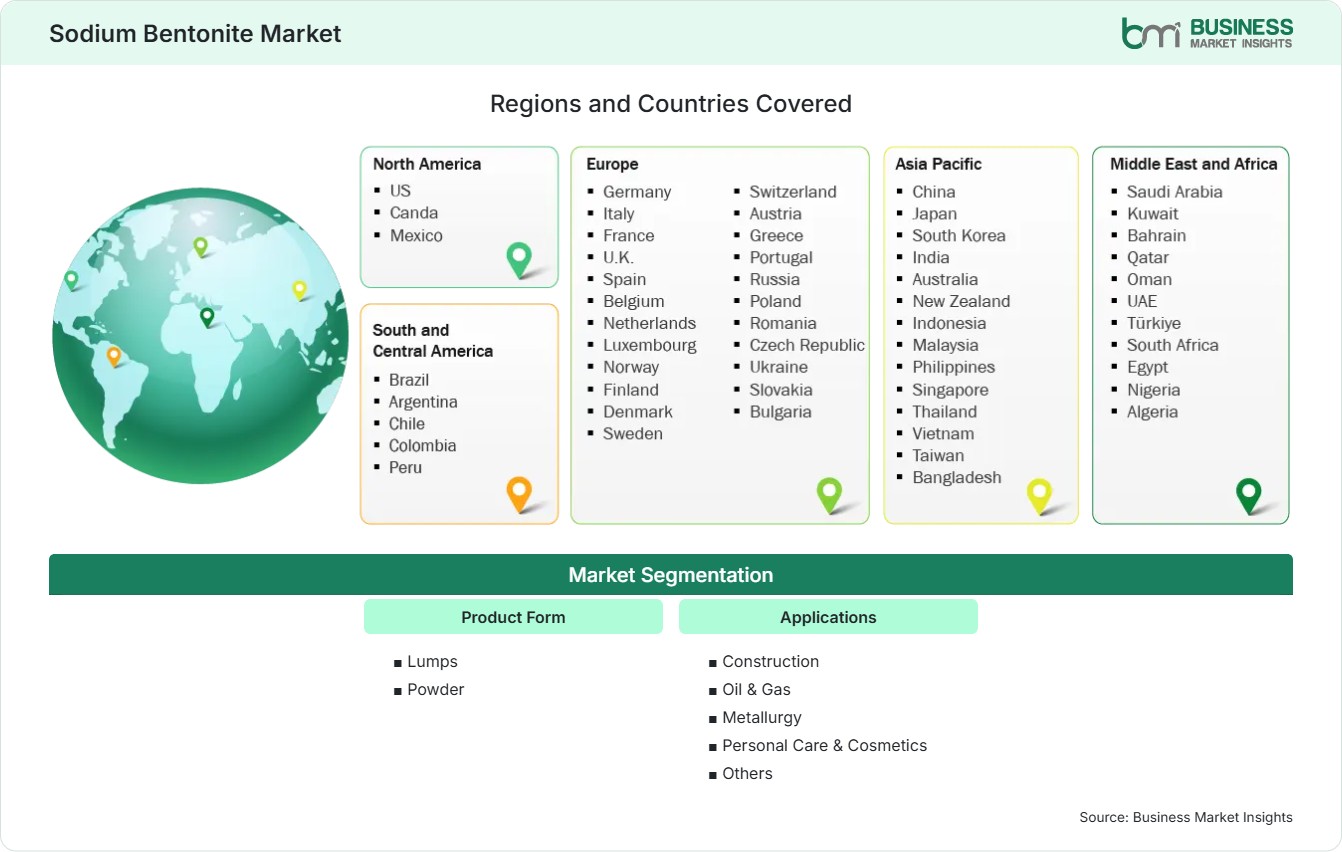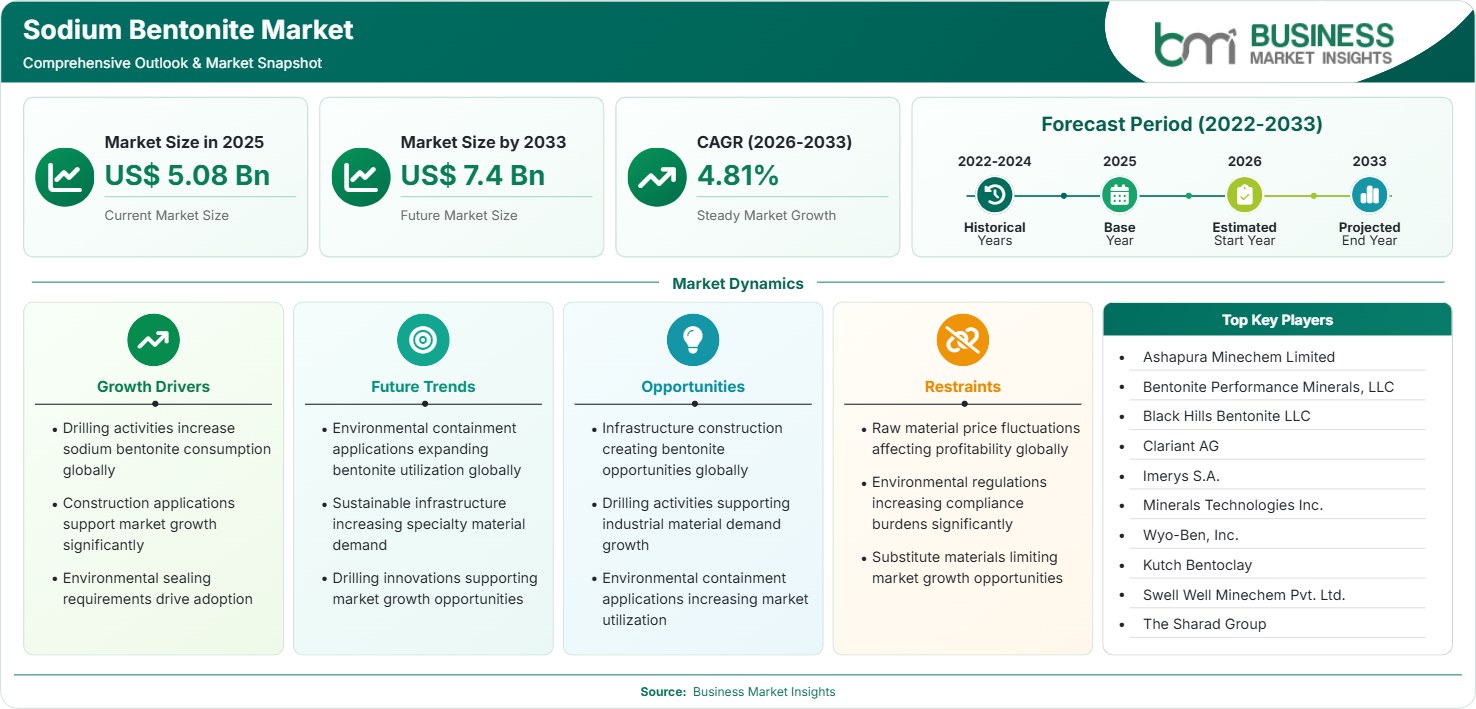
Sodium Bentonite Market Regional Highlights
North America Sodium Bentonite Market
North America represents 21%–24% share in 2025 and is projected to expand at a 4.3%–4.7% CAGR during 2026–2033. The region benefits from extensive domestic deposits, established processing infrastructure, drilling demand, construction applications, and environmental containment projects. The Sodium Bentonite Market share remains supported by US production and established rail distribution. Canada and the US provide strong technical ecosystems, while Mexico adds regional demand for drilling and infrastructure. The region’s supply advantage reduces dependence on long-distance imports for several industrial applications.
- US drilling activity supports high-viscosity grades, although upstream investment remains cyclical. The IEA projected a 6% decline in global upstream oil investment in 2025, reinforcing the importance of diversified end-use exposure.
- Environmental engineering is expanding demand for swelling grades used in liners, slurry walls, wastewater containment, and soil sealing, particularly where permeability control is a primary design requirement.
- Domestic producers increasingly compete through rail access, technical support, formulation consistency, and application testing rather than mineral availability alone, strengthening customer retention among industrial buyers.
- Pet absorbents and cat litter provide a stabilizing demand stream because sodium bentonite’s swelling and clumping characteristics support efficient moisture capture and simplified waste removal.
US Sodium Bentonite Market
The US represents approximately 65%–70% of North American demand in 2025, with a 4.1%–4.6% CAGR through 2033. Wyoming, Montana, and South Dakota remain strategically important production areas, while Texas and other energy-intensive states contribute to downstream demand. USGS reported estimated bentonite production of 4.8 million metric tons in 2024 and identified pet waste absorbents and drilling mud as major applications.
- Domestic reserves and established processing networks support shorter lead times, while rail connectivity remains critical for moving bulk material from western mining regions to national customers.
- Civil engineering demand benefits from tunneling, slurry walls, foundation construction, landfill containment, ponds, and wastewater infrastructure requiring low-permeability mineral barriers.
- Specialty applications are gaining importance as suppliers develop cosmetic, environmental, pet care, and industrial grades that deliver higher technical value than untreated bulk material.
Europe Sodium Bentonite Market
The Europe region accounts for 19%-22% of the Sodium Bentonite Market in 2025, growing at a CAGR of 4.0%-4.4% from 2026 - 2033. Key industrial markets are located in Germany, Italy, Spain, France, Poland, and Türkiye, with Türkiye contributing significantly to mineral supply and exports. Foundries, construction applications, environmental lining, and filtration drive the growth. Low emission, mine restoration, product tracing, and reliable performance are essential to European consumers. Clariant holds bentonite mines and production plants in Europe and elsewhere.
- Germany and Italy benefit from sophisticated foundry industries, where activated sodium bentonite improves mould strength, dimensional stability, processability, and casting consistency.
- Türkiye offers an important resource and export platform, connecting European, Middle Eastern, and North African buyers with a competitive mineral supply.
- Environmental regulation supports premium grades designed for containment, wastewater management, and lower-emission foundry operations where mineral performance can reduce downstream process impacts.
- Specialty mineral suppliers increasingly combine mining, processing, laboratory testing, and technical support to meet tighter specifications from industrial customers.
Asia Pacific Sodium Bentonite Market
The Asia Pacific region accounts for 33%-36% of the market share in 2025 and has the highest regional growth rate, with a 5.2%-5.6% CAGR until 2033. China and India are major consumers and producers, driven by activities such as construction, steelmaking, drilling, foundry operations, and environmental initiatives. Japan, South Korea, Indonesia, and the Southeast Asian countries contribute unique industrial demand. The significance of China and India lies in the fact that steel, infrastructure, mineral processing, and industrial manufacturing create multiple demand streams simultaneously. According to Worldsteel, crude steel production in China was 960.8 million metric tons and in India 164.9 million metric tons in 2025.
- China remains a major production and consumption center, with demand spanning foundry binders, drilling fluids, construction, water treatment, and industrial processing.
- India combines substantial bentonite resources with expanding steel, infrastructure, export, and processing activity, creating opportunities for value-added grades and international supply contracts.
- Indonesia, Vietnam, and Southeast Asian markets benefit from infrastructure construction and industrialization, while localized processing can reduce freight costs and improve product responsiveness.
- Regional suppliers increasingly invest in technical services and application-specific products as customers demand consistent performance rather than commodity mineral specifications.
Rest of World Sodium Bentonite Market
The South and Central America Sodium Bentonite Market is experiencing growing demand, with applications in drilling, construction, foundry, and mineral processing in countries such as Brazil and Mexico. The Middle East and Africa offer additional demand for oil and gas exploration, infrastructure, water treatment, and mining. The RoW region accounts for 20%-24% share in 2025 and grows at 4.2%-4.6% CAGR till 2033.
Brazil and Mexico provide established industrial demand, while Saudi Arabia and the UAE benefit from energy investment. Africa offers longer-term potential through mining, infrastructure, and water-management projects.
- Brazil combines steel, mining, construction, and drilling applications, creating demand diversity that can reduce exposure to individual industrial cycles.
- Mexico remains relevant for drilling and industrial minerals, with domestic bentonite production complemented by cross-border trade and manufacturing demand.
- Saudi Arabia and the UAE offer attractive drilling and infrastructure opportunities, supported by substantial energy investment and large-scale industrial development programs.
- South Africa and selected African markets provide potential through mining, foundry, environmental remediation, and civil construction as industrial infrastructure expands.