
Physical Vapor Deposition Market Outlook: Size, Share, Trends, Growth Analysis, Competitive Landscape & Forecast, 2026-2033

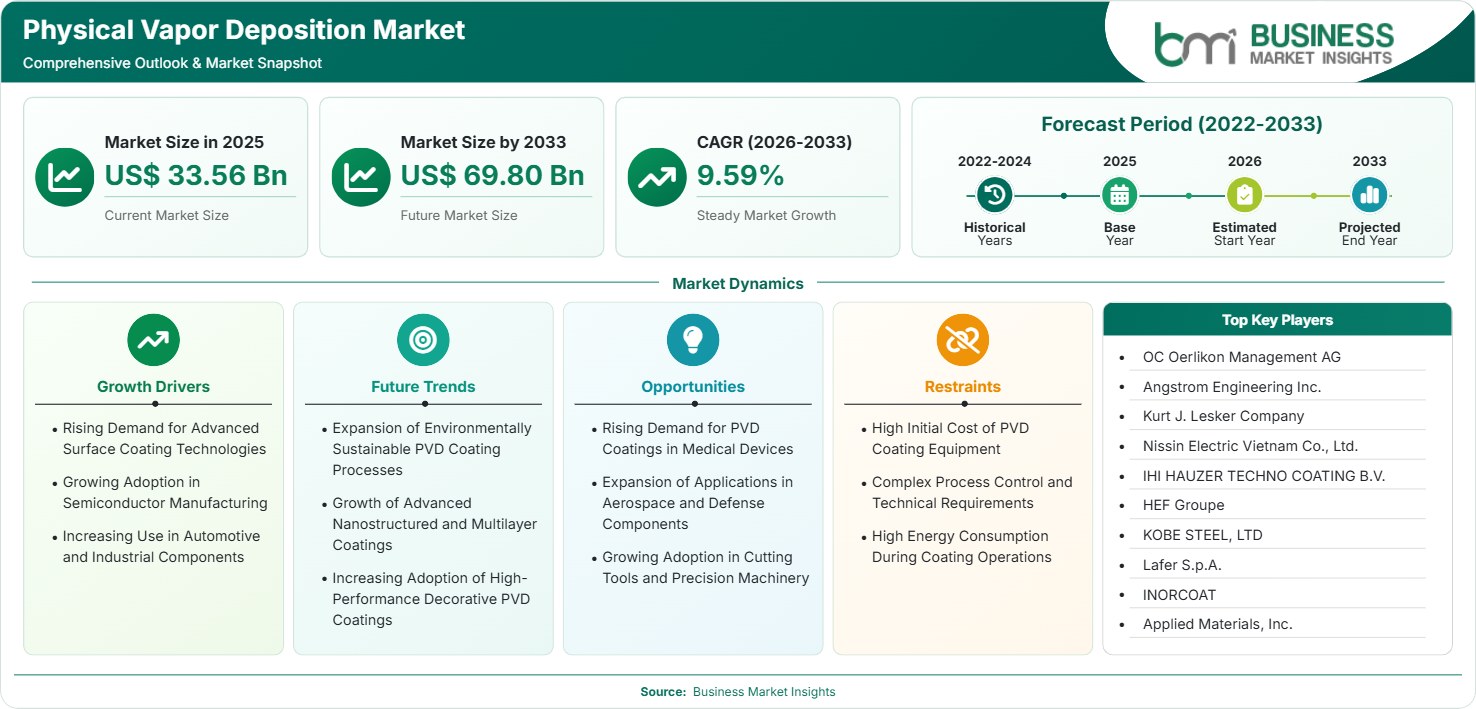
The Physical Vapor Deposition Market size was valued at US$ 33.56 Billion in 2025 and is projected to reach US$ 69.80 Billion by 2033, growing at a CAGR of 9.59% during 2026–2033. Rising demand for advanced surface coating technologies, increasing adoption of semiconductor manufacturing processes, growing use of wear-resistant coatings in industrial applications, and expanding deployment of thin-film technologies are supporting market growth globally.

Report Coverage
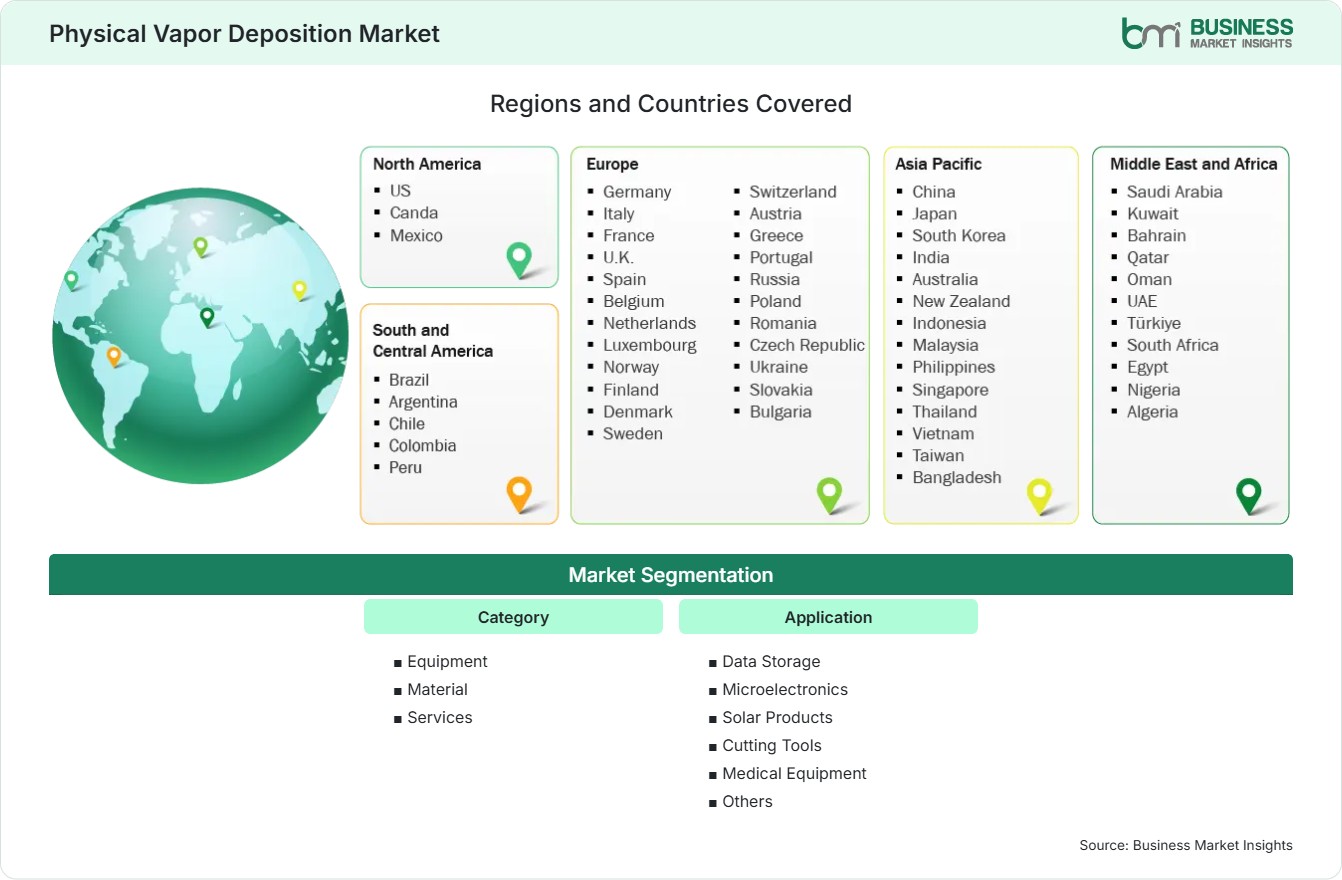
  • Category: Equipment, Material, Services
  • Application: Data Storage, Microelectronics, Solar Products, Cutting Tools, Medical Equipment, Others
US$ 33.56 Bn Market size in 2025
US$ 69.80 Bn Market Size by 2033
9.59% CAGR, 2026 - 2033
2026-2033 Forecast Period

AI Overview

Physical Vapor Deposition Market Summary

  • North America Region: North America holds a market share of 34%–37% in 2025, growing with a CAGR of 9.1%–9.8% during 2026–2033. Strong semiconductor manufacturing activities, increasing demand for advanced coatings, and technological innovation continue supporting regional leadership. The U.S. market is expected to register a CAGR of 9.3%–10.0%.
  • Fastest Growing Region: Asia Pacific accounts for 31%–34% share in 2025 and is projected to grow at a CAGR of 10.1%–10.8% through 2033. Expanding electronics manufacturing, rising industrial output, and growing solar panel production continue driving regional growth.
  • Leading Segment: Equipment represents 52%–55% share in 2025 and is expected to grow at a CAGR of 9.6%–10.3% through 2033. Increasing installation of advanced coating and deposition systems continues supporting segment dominance.
  • High Growth Segment: Microelectronics accounts for 29%–32% share in 2025 and is forecast to grow at a CAGR of 10.4%–11.1% during 2026–2033. Rising semiconductor demand and advanced electronics manufacturing continue accelerating segment growth.
  • Key Market Opportunity: Expansion of semiconductor fabrication facilities, advanced medical coatings, solar energy technologies, and precision industrial tooling is creating substantial growth opportunities.
  • Major Market Players: OC Oerlikon Management AG, Angstrom Engineering Inc., Kurt J. Lesker Company, Nissin Electric Vietnam Co., Ltd., IHI HAUZER TECHNO COATING B.V., HEF Groupe, KOBE STEEL, LTD., Lafer S.p.A., INORCOAT, and Applied Materials, Inc.
Strategic Insights

Physical Vapor Deposition Market: Strategic Insights

Physical Vapor Deposition Market Strategic Framework
FREE PDF
Request your free sample
Request free sample
Stakeholder View

Key Takeaways

  • Physical vapor deposition remains a critical technology for advanced surface engineering, enabling improved hardness, wear resistance, corrosion protection, and functional performance.
  • Equipment continues dominating the physical vapor deposition market as manufacturers increase deployment of advanced deposition systems across production facilities.
  • Microelectronics represents the fastest-growing application segment, supported by rising demand for miniaturized and high-performance electronic components.
  • Semiconductor manufacturing remains a major demand driver, particularly for precision coatings and advanced fabrication processes.
  • Industrial coatings are expanding across automotive, aerospace, energy, tooling, and other end-use industries.
  • North America leads the market, supported by technological innovation and strong semiconductor activity.
  • Asia Pacific is expected to record the fastest growth as electronics manufacturing expands.
  • Solar energy and medical devices are creating significant future opportunities for advanced coating technologies.
Geographic Outlook

Physical Vapor Deposition Market Regional Highlights

North America Physical Vapor Deposition Market

North America accounts for 34%–37% Physical Vapor Deposition Market share in 2025 and is projected to grow at a CAGR of 9.1%–9.8% through 2033. The region benefits from advanced manufacturing capabilities, increasing semiconductor investments, and growing adoption of precision coating technologies.

  • Semiconductor manufacturers are increasing investments in advanced deposition systems to support domestic chip production and technology development.
  • Aerospace and defense industries continue utilizing high-performance coatings to improve component durability and operational efficiency.
  • Medical device manufacturers are expanding adoption of PVD coatings to enhance product performance and biocompatibility.
  • Growing demand for advanced electronics is supporting installation of next-generation vacuum coating equipment.
  • Industrial tooling companies increasingly deploy wear-resistant coating technologies to improve productivity and lifespan.
  • Research institutions and technology companies continue driving innovation in thin-film deposition processes and applications.

US Physical Vapor Deposition Market

The United States contributes approximately 89%–93% of North American revenue and is expected to register a CAGR of 9.3%–10.0% through 2033. The country remains the largest market due to strong semiconductor, aerospace, and advanced manufacturing activities.

  • Domestic semiconductor expansion projects are increasing demand for sophisticated deposition equipment and processing technologies.
  • Electronics manufacturers are investing in advanced coating solutions to support miniaturization and performance enhancement objectives.
  • Medical technology companies continue utilizing surface engineering technologies for specialized healthcare applications.
  • Aerospace component manufacturers increasingly adopt high-performance coatings for durability and corrosion resistance.
  • Industrial automation growth is strengthening demand for coated tools and precision-engineered components.
  • Government support for advanced manufacturing continues encouraging investment across key technology sectors.

Europe Physical Vapor Deposition Market

Europe represents 22%–25% of global revenue in 2025 and is anticipated to expand at a CAGR of 9.5%–10.2% through 2033. Strong industrial manufacturing activity, advanced engineering capabilities, and growing demand for sustainable coating technologies continue supporting regional growth. Germany remains the leading market while Poland demonstrates stronger growth momentum.

  • Germany continues leading regional demand through strong automotive, machinery, and industrial manufacturing sectors.
  • Poland is among the fastest-growing markets and is estimated to register a CAGR of 10.4%–11.1% during the forecast period.
  • Automotive manufacturers increasingly adopt advanced coating technologies to improve component performance and durability.
  • Sustainability initiatives are encouraging the use of environmentally efficient coating processes across industries.
  • Demand for precision-engineered cutting tools continues supporting market expansion.
  • Research and innovation activities remain important contributors to regional technological advancement.

Asia Pacific Physical Vapor Deposition Market

Asia Pacific accounts for 31%–34% of global revenue in 2025 and is expected to achieve the fastest CAGR of 10.1%–10.8% through 2033. Rapid industrialization, growing electronics manufacturing, expanding semiconductor production, and increasing investments in renewable energy technologies continue supporting strong regional growth.

  • China remains the largest regional market due to extensive electronics, semiconductor, and solar manufacturing activities.
  • India is projected to achieve approximately 11.0%–11.7% CAGR, supported by manufacturing expansion and electronics production growth.
  • Semiconductor fabrication investments continue generating strong demand for deposition equipment and services.
  • Solar panel manufacturers increasingly utilize thin-film coating technologies to improve product efficiency.
  • Consumer electronics growth continues supporting adoption of advanced microelectronics manufacturing processes.
  • Industrial modernization initiatives are expanding the use of high-performance surface coating solutions.

Rest of World Physical Vapor Deposition Market

Rest of World accounts for 8%–11% of global revenue in 2025 and is projected to expand at a CAGR of 8.4%–9.1% through 2033. Growing industrial development, increasing adoption of advanced manufacturing technologies, and rising investments in infrastructure are supporting market growth across Latin America, the Middle East, and Africa.

  • Brazil continues generating demand through expanding industrial manufacturing and automotive production activities.
  • The UAE is witnessing increasing adoption of advanced coating technologies across infrastructure and industrial projects.
  • Saudi Arabia is expected to achieve approximately 9.3%–10.0% CAGR through 2033, supported by industrial diversification initiatives.
  • Manufacturing modernization programs are encouraging investments in surface engineering technologies.
  • Energy and industrial sectors continue utilizing advanced coatings to improve equipment performance and reliability.
  • Emerging industrial ecosystems are creating long-term opportunities for equipment suppliers and service providers.
Global Market Geography
FREE PDF
Request your free sample
Request free sample
Segment Analysis

Physical Vapor Deposition Market Segmentation

Category

The category segment represents the primary components of the physical Vapor deposition ecosystem, including equipment, consumable materials, and specialized coating services. This segment accounts for approximately 52%–55% share in 2025 and is projected to grow at a CAGR of 9.6%–10.3% through 2033. The expanding Physical Vapor Deposition Market Scope is supported by increasing manufacturing automation, rising semiconductor investments, and growing utilization of advanced surface engineering technologies across industrial sectors.

  • Equipment: Equipment dominates the market due to increasing deployment of vacuum coating systems, deposition chambers, sputtering systems, and evaporation equipment across semiconductor, industrial, and medical applications.
  • Material: Materials include coating targets, deposition materials, specialty metals, ceramics, and advanced compounds utilized throughout the coating process.
  • Services: Service providers continue expanding offerings including coating applications, equipment maintenance, process optimization, and technical support solutions.

Application

The application segment highlights the major industries utilizing PVD coatings and thin-film deposition technologies. This segment accounts for approximately 29%–32% share in 2025 and is expected to register a CAGR of 10.4%–11.1% through 2033. Current Physical Vapor Deposition Market Trends indicate increasing adoption across semiconductor manufacturing, medical equipment, renewable energy technologies, and industrial tooling applications.

  • Data Storage: PVD technologies are widely used in hard disk drives, magnetic storage media, and advanced data storage devices.
  • Microelectronics: Microelectronics dominates the market owing to extensive utilization in semiconductor fabrication, integrated circuits, sensors, and electronic component manufacturing.
  • Solar Products: Solar product manufacturers increasingly deploy thin-film coating technologies to improve photovoltaic efficiency and product performance.
  • Cutting Tools: Industrial cutting tools utilize wear-resistant PVD coatings to enhance durability, precision, and operational lifespan.
  • Medical Equipment: Medical device manufacturers adopt PVD coatings to improve corrosion resistance, biocompatibility, and product reliability.
  • Others: Other applications include automotive components, decorative coatings, aerospace equipment, and advanced industrial machinery.
Market Forces

Physical Vapor Deposition Market Dynamics

Key Market Drivers

Rising Demand for Advanced Surface Coating Technologies

Several factors influence the popularity of physical Vapor Deposition techniques, including the increasing need for efficient surface coatings. Modern industries require effective coating systems that provide better wear and corrosion resistance, high thermal stability, and durability of products. At the same time, physical vapor deposition coating techniques provide an opportunity to improve the performance of products while maintaining environmentally friendly production processes. Modern manufacturing companies use advanced coating techniques more often for better quality and operational efficiency.

Growing Adoption in Semiconductor Manufacturing

The fast growth in the number of semiconductor fabrication plants still creates high demand for physical vapor deposition equipment and services. The PVD equipment plays a key role in forming the thin films necessary for semiconductor chips, integrated circuits, sensors, and electronic devices. The growing needs for consumer electronics, artificial intelligence solutions, data centers, and connected devices are prompting more companies to invest in semiconductor fabrication plants. High deposition technology accuracy is essential for manufacturers to meet their requirements for miniaturization and performance. Demand for advanced PVD equipment will continue growing as global semiconductor production keeps increasing.

Increasing Use in Automotive and Industrial Components

The industrial and automotive industries rely on PVD coatings to increase the durability and wear resistance of vital parts. They include the components of engines, transmissions, tools, machines, and any other components used under harsh operating conditions. This technique decreases friction, increases efficiency, and ensures a long lifetime for equipment, which helps in reducing maintenance cost. Due to an increasing focus on quality of products and their performance, there will be more application of this technique in industrial settings.

Key Market Opportunities

Rising Demand for PVD Coatings in Medical Devices

The healthcare sector is creating significant opportunities for physical Vapor deposition technologies due to increasing use of advanced coatings in medical devices and surgical instruments. PVD coatings enhance biocompatibility, corrosion resistance, surface hardness, and sterilization performance. Medical manufacturers are continuously seeking innovative materials capable of improving product safety and durability. Growing investments in healthcare infrastructure and medical technology development are further supporting adoption. As the global medical device industry continues expanding, demand for specialized PVD coating solutions is expected to increase substantially.

Expansion of Applications in Aerospace and Defense Components

Aerospace and defense industries are increasingly adopting advanced coating technologies to improve reliability and performance of critical components. Physical Vapor deposition enables the creation of lightweight, durable, and wear-resistant coatings suitable for demanding operational environments. Aircraft systems, turbine components, defense equipment, and precision instrumentation benefit from enhanced surface properties provided by PVD processes. Continued investments in aviation modernization and defense technologies are creating attractive growth opportunities for coating providers and equipment manufacturers serving these specialized sectors.

Growing Adoption in Cutting Tools and Precision Machinery

Industrial manufacturers are increasingly utilizing PVD-coated cutting tools and machinery components to improve machining efficiency, productivity, and equipment lifespan. Coated tools provide enhanced hardness, reduced friction, and superior wear resistance during demanding manufacturing operations. Precision engineering industries continue emphasizing advanced tooling solutions capable of maintaining consistent performance and minimizing downtime. Long-term Physical Vapor Deposition Market Forecast projections remain highly favorable as manufacturers invest in high-performance production technologies and advanced machining capabilities.

Market Restraints and Challenges

High Initial Cost of PVD Coating Equipment

Factor: Physical Vapor deposition systems require substantial capital investment for vacuum chambers, coating equipment, process control systems, and supporting infrastructure. Installation and commissioning costs can be significant, particularly for advanced manufacturing facilities.

Impact: High capital expenditure requirements may create adoption barriers for small and medium-sized manufacturers. Investment costs can also extend project payback periods and influence procurement decisions across certain end-use industries.

Complex Process Control and Technical Requirements

Factor: PVD coating processes require precise control of vacuum conditions, deposition parameters, coating materials, substrate preparation, and process monitoring to achieve consistent performance and quality outcomes.

Impact: Technical complexity may increase operational costs, require specialized expertise, and create challenges related to workforce training and process optimization. Companies must invest continuously in skilled personnel and process management capabilities to maintain competitive performance.

Company Analysis

Competitive Landscape

The Physical Vapor Deposition Market Analysis is characterized by strong competition among coating equipment manufacturers, vacuum technology providers, advanced materials suppliers, and specialized coating service companies. Market participants are focusing on high-precision deposition systems, semiconductor manufacturing solutions, advanced thin-film coating technologies, and industrial surface engineering applications to strengthen their market positions. Rising demand for microelectronics, growing adoption of high-performance coatings, and increasing investments in semiconductor fabrication facilities continue driving innovation across the market. Companies are investing in automation, process optimization, advanced coating materials, and next-generation deposition technologies to address evolving industry requirements.

Company Name

Overview

Products and Services relevant to this market

OC Oerlikon Management AG

Global provider of surface solutions and advanced manufacturing technologies.

PVD coating systems, surface engineering solutions, thin-film coatings, and industrial coating services.

Angstrom Engineering Inc.

Manufacturer of vacuum deposition equipment and thin-film processing systems.

PVD systems, sputtering equipment, evaporation systems, and semiconductor coating solutions.

Kurt J. Lesker Company

Vacuum technology and materials provider serving research and industrial markets.

Vacuum deposition systems, coating materials, PVD equipment, and thin-film processing technologies.

Nissin Electric Vietnam Co., Ltd.

Industrial technology company focused on advanced manufacturing solutions.

PVD equipment, coating technologies, vacuum systems, and surface treatment solutions.

IHI HAUZER TECHNO COATING B.V.

Specialist in advanced coating technologies and deposition systems.

PVD coating equipment, industrial coating services, and wear-resistant surface solutions.

HEF Groupe

Surface engineering and materials technology company.

PVD coatings, tribological solutions, surface treatment services, and industrial coating technologies.

KOBE STEEL, LTD.

Industrial manufacturing company with advanced materials and machinery expertise.

Vacuum coating systems, industrial equipment, advanced materials, and surface engineering solutions.

Lafer S.p.A.

Surface treatment and coating technology provider.

PVD coating systems, decorative coatings, industrial surface treatments, and advanced finishing solutions.

INORCOAT

Provider of vacuum coating equipment and surface engineering technologies.

PVD equipment, coating services, thin-film deposition systems, and industrial coating solutions.

Applied Materials, Inc.

Global semiconductor manufacturing equipment company.

PVD systems, semiconductor fabrication equipment, thin-film deposition technologies, and materials engineering solutions.

Trust & Transparency

Research Methodology

The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst review.

View Full Research Methodology

Questions Answered

Frequently Asked Questions

How is semiconductor manufacturing influencing the physical Vapor deposition industry?

Semiconductor manufacturing is increasing demand for advanced thin-film deposition technologies that enable precise coating processes required for integrated circuits, microchips, sensors, and next-generation electronic devices.

What does this Physical Vapor Deposition Market Report cover?

This report covers category analysis, application assessment, regional trends, competitive landscape analysis, market drivers, opportunities, restraints, challenges, and future growth prospects through 2033.

Why is Microelectronics the fastest-growing application segment?

Microelectronics is experiencing the fastest growth because PVD technology is essential for semiconductor fabrication, integrated circuit production, sensors, and advanced electronic component manufacturing.

Which category segment dominates the market?

Equipment dominates the market due to increasing deployment of advanced deposition systems, sputtering equipment, and vacuum coating technologies across semiconductor and industrial manufacturing facilities.

What is driving growth in the Physical Vapor Deposition market?

Rising demand for advanced surface coating technologies, growing adoption in semiconductor manufacturing, increasing use in automotive and industrial components, and expanding applications in medical and aerospace industries are major factors driving market growth.

Access the Full Physical Vapor Deposition Market Report

Get segment-level forecasts, regional estimates, competitive benchmarking, company profiles and downloadable Excel datasets.

Access the full Physical Vapor Deposition Market Report
350 pages PDF & Excel | 2026-08-20
Similar Research

Related Market Reports