
Industrial Drums Market Outlook: Size, Share, Trends, Growth Analysis, Competitive Landscape & Forecast, 2026-2033

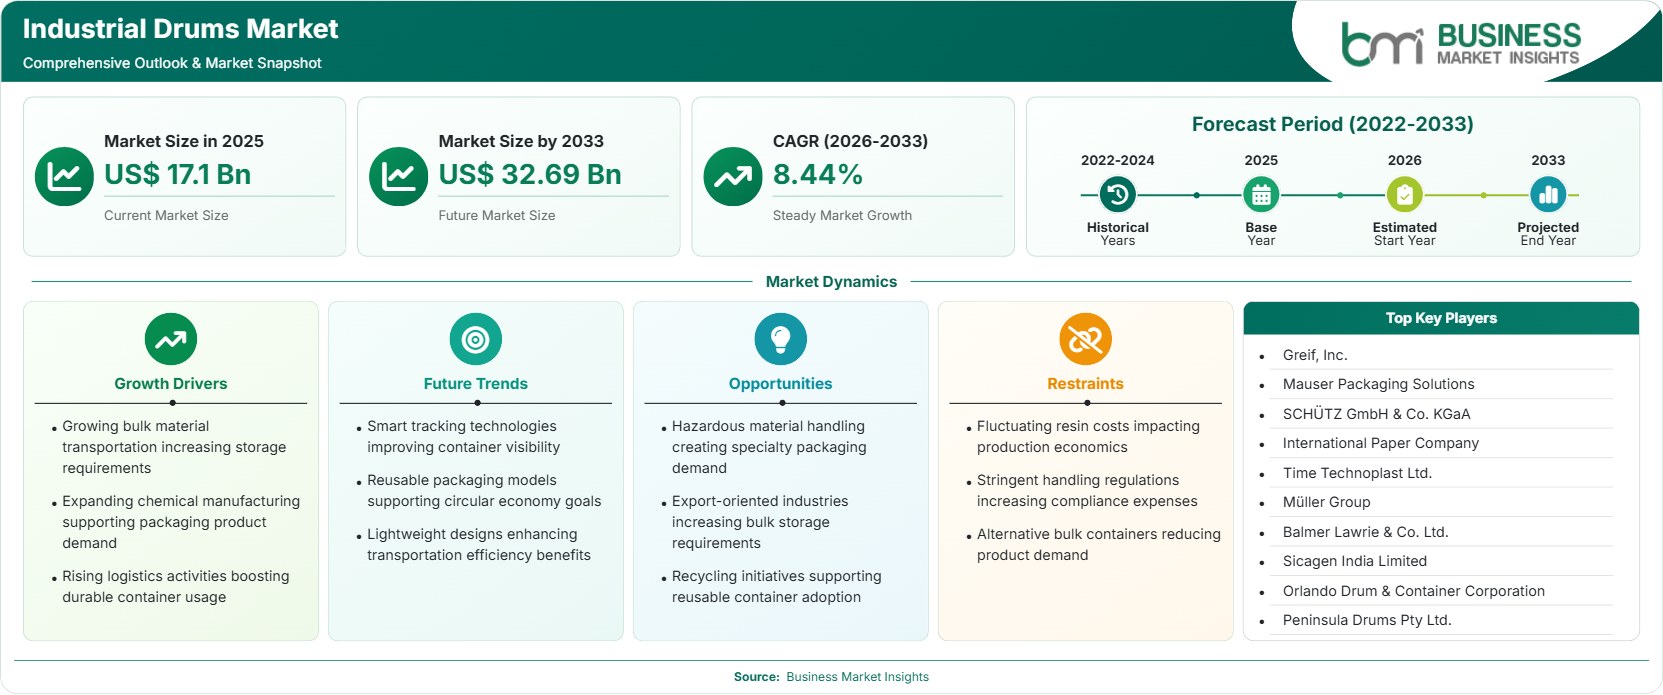
The Industrial Drums Market size was valued at US$ 17.1 Billion in 2025 and is projected to reach US$ 32.69 Billion by 2033, growing at a CAGR of 8.44% during 2026–2033. Rising chemical exports, expanding food processing activities, pharmaceutical logistics requirements, and increasing demand for sustainable bulk packaging solutions are creating strong growth opportunities across industrial supply chains.

Report Coverage
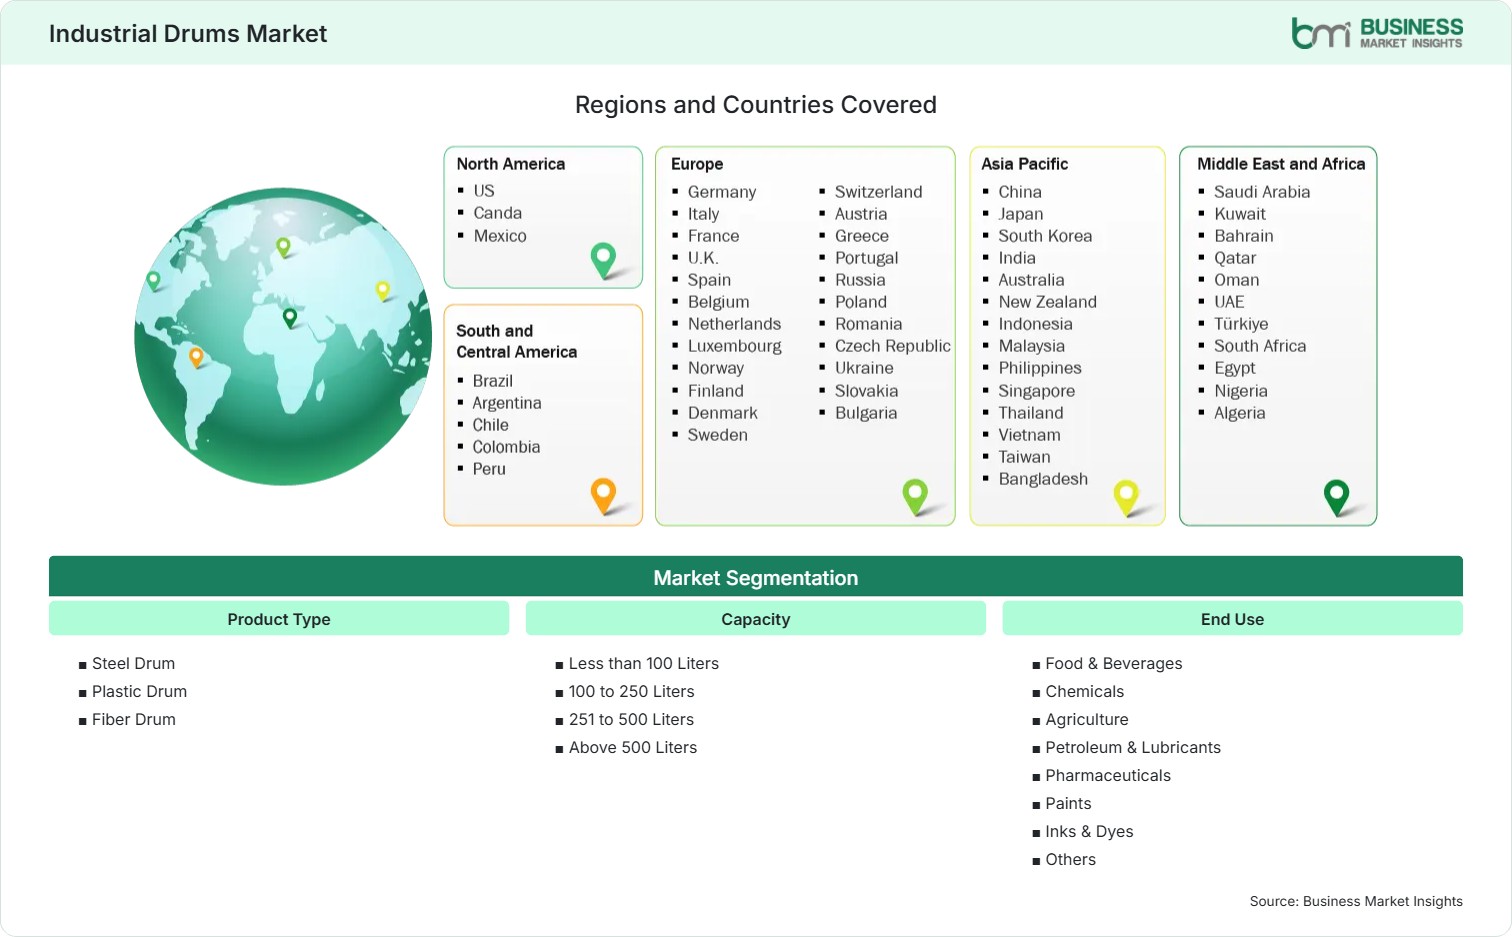
  • Product Type: Steel Drum, Plastic Drum, Fiber Drum
  • Capacity: Less than 100 Liters, 100 to 250 Liters, 251 to 500 Liters, Above 500 Liters
  • End Use: Food & Beverages, Chemicals, Agriculture, Petroleum & Lubricants, Pharmaceuticals, Paints, Inks & Dyes, Others
US$ 17.1 Bn Market size in 2025
US$ 32.69 Bn Market Size by 2033
8.44% CAGR, 2026 - 2033
2026-2033 Forecast Period

AI Overview

Industrial Drums Market Summary

  • North America Region: North America holds a market share of 32%–35% in 2025, growing with a CAGR of 7.2%–7.8% during 2026–2033, supported by chemical manufacturing investments, hazardous material transportation requirements, sustainability initiatives, and modernization of industrial packaging infrastructure. The United States benefits from strong chemical production expansion and replacement demand, advancing at a CAGR of 7.3%–7.9%.
  • Fastest Growing Region: Asia Pacific accounts for 28%–31% share in 2025 and is projected to expand at a CAGR of 9.8%–10.5% through 2033. Rapid industrialization, chemical exports, pharmaceutical manufacturing growth, and increasing storage requirements continue attracting packaging capacity investments.
  • Leading Segment: Steel Drum represents 42%–45% share in 2025 and is expected to advance at a CAGR of 7.8%–8.5%. High durability, compatibility with hazardous chemicals, superior stacking strength, and widespread industrial application sustain segment leadership across global supply chains.
  • High Growth Segment: Pharmaceuticals holds 11%–14% share in 2025 and records a CAGR of 10.1%–10.9%. Expanding biologics production, strict packaging compliance standards, and increased temperature-sensitive product transportation create substantial demand for advanced drum solutions.
  • Key Market Opportunity: Circular packaging initiatives are accelerating demand for reconditioned and recyclable containers, enabling manufacturers to reduce lifecycle costs, meet sustainability targets, enhance traceability, and create recurring service-based revenue streams.
  • Major Market Players: Greif, Inc.; Mauser Packaging Solutions; SCHÜTZ GmbH & Co. KGaA; International Paper Company; Time Technoplast Ltd.; Müller Group; Balmer Lawrie & Co. Ltd.; Sicagen India Limited; Orlando Drum & Container Corporation; Peninsula Drums Pty Ltd.
Strategic Insights

Industrial Drums Market: Strategic Insights

Industrial Drums Market Strategic Framework
FREE PDF
Request your free sample
Request free sample
Stakeholder View

Key Takeaways

  • The resin suppliers, the steel producers, the drum manufacturers, the reconditioning companies, the logistics providers, and the industrial end users are now more incorporated into the value chain, which leads to possibilities for vertically integrated packaging ecosystems.
  • Pharmaceutical products and specialty chemicals offer the strongest Industrial Drums Market growth potential due to stringent handling requirements, rising export volumes, and increasing demand for contamination-resistant storage solutions.
  • For manufacturers who are aiming to win over high-end industrial customers, intelligent packaging technologies such as RFID tracking, digital identification systems, and lifecycle monitoring are becoming important factors in distinguishing their products.
  • The investment environment in Asia Pacific is highly attractive because of strong growth in chemical production, the expansion of industrial exports, and the growing localization of packaging manufacturing facilities.
  • As global packaging companies increasingly aim to expand geographically, to develop their sustainability capabilities, and to gain access to specialised industrial end-user networks, consolidation activity is growing.
  • The initiatives promoting a circular economy are having a transforming effect on procurement strategies, which is leading to a greater use of reconditioned steel and plastic containers in a number of industrial applications.
Geographic Outlook

Industrial Drums Market Regional Highlights

North America Industrial Drums Market

North America accounted for approximately 32%–35% of global demand in 2025 and is expected to expand at a CAGR of 7.2%–7.8% through 2033. Chemical production, petroleum transportation, pharmaceutical production capability, and industrial logistics are among those factors that account for regional dominance. The Industrial Drums Market share remains supported by replacement demand and sustainability initiatives promoting reconditioned drums.

  • Increasingly, chemical producers are adopting reusable packaging systems to improve their sustainability performance and, at the same time, reduce transportation costs within regional supply chains.
  • The increasing amount of hazardous materials being transported leads to a greater demand for containers that are certified and capable of satisfying strict safety and regulatory compliance requirements.
  • By expanding its program of reconditioning infrastructure, the initiative promotes the use of circular packaging and thus enhances cost efficiency for industrial customers in a number of sectors.
  • The fact that there are investments in pharmaceutical manufacturing creates a demand for high-performance storage and transportation solutions, which are intended to keep the product's integrity.
  • Sustainability regulations promote the wider use of recyclable materials and the implementation of lifecycle management programs within industrial packaging operations.

US Industrial Drums Market

The United States represents approximately 72%–76% of North American Industrial Drums Market demand and is projected to register a CAGR of 7.3%–7.9% during the forecast period. The large-scale production of chemicals, strong lubricant consumption, specialized manufacturing operations, and efficient logistics operations have been some of the factors that have kept the demand up. Reshoring of industries and increased domestic chemical production are some of the factors that keep the demand for packaging high.

  • The volume of chemical exports is still increasing, which in turn raises the demand for durable packaging solutions that meet the requirements for international transport.
  • The trends in industrial automation are leading to the use of standardised container formats to improve warehouse efficiency and handling productivity.
  • The sustainability commitments of manufacturers encourage a greater use of packaging that is recyclable or reconditioned.
  • Spending on specialty chemicals and pharmaceuticals increases the demand for high-specification storage and transport containers.

Europe Industrial Drums Market

Europe represented around 24%–27% of the global Industrial Drums Market demand in 2025 and is anticipated to expand at a CAGR of 7.0%–7.6% through 2033. Strict regulations, advanced chemical manufacturing processes, and heavy international commerce are all positive indicators for packaging stability. Germany is leading the region in consumption terms with a CAGR of 7.1% to 7.7%. Growth is much higher in Poland and other East European countries.

  • Germany retains its position of regional leadership due to its large chemical industry, its industrial base, which is oriented towards exports, and the sophisticated packaging recovery system it has in place to support its circular economy goals.
  • The demand in France and Italy for food ingredients, specialty chemicals, paints and lubricants is such that it requires secure transportation solutions.
  • As sustainability regulations become more stringent, there is an increase in investment in technologies for recyclable packaging and in reconditioning facilities across the various regional markets.
  • Poland has some of the strongest prospects for growth because of expansion in manufacturing, the development of its logistics infrastructure, and rising industrial exports.
  • Industrial customers are increasingly adopting digital traceability solutions to achieve better compliance, greater visibility into their inventory, and improved efficiency in their supply chains.

Asia Pacific Industrial Drums Market

Asia Pacific captured approximately 28%–31% of global Industrial Drums Market demand in 2025 and is expected to record the fastest CAGR of 9.8%–10.5% through 2033. China remains the leading country supported by large-scale chemical production and manufacturing exports, while India demonstrates one of the strongest growth trajectories with CAGR exceeding 10%.

  • China benefits from extensive manufacturing ecosystems and strong exports requiring large-scale packaging and bulk transportation solutions.
  • India is experiencing strong growth, which is due to the expansion in the production of pharmaceuticals, increased industrial investment, and higher consumption of chemicals.
  • Because of the favorable production costs and the possibility of exporting, economies in Southeast Asia are drawing in investments for packaging manufacturing.
  • The addition of petrochemical capacity in Asia is still leading to a great demand for containers used in the storage and handling of hazardous liquids.
  • Because of increasing environmental awareness, recyclable and reusable industrial packaging systems are being adopted across the various regional supply chains.

Rest of World Industrial Drums Market

Rest of World accounted for approximately 10%–13% of global Industrial Drums Market demand in 2025 and is projected to expand at a CAGR of 8.3%–8.9% through 2033. South & Central America benefit from agricultural processing, chemicals production, and expanding logistics networks. Brazil remains the leading regional market.

In the Middle East and Africa, petrochemical sector investments, energy infrastructure projects, and industrial diversification programs support packaging demand. Saudi Arabia and the United Arab Emirates demonstrate strong growth prospects, while South Africa remains a key manufacturing and distribution hub.

  • Brazil drives regional consumption through agricultural exports, food ingredient processing, lubricant demand, and industrial manufacturing expansion.
  • Gulf countries benefit from ongoing petrochemical capacity investments, generating sustained demand for bulk liquid transportation containers.
  • Industrial diversification initiatives across the Middle East create opportunities for packaging manufacturers to establish regional production facilities.
  • African pharmaceutical and food processing sectors contribute incremental demand for safe storage and transportation solutions.
  • Improvements in logistics infrastructure strengthen market accessibility and support broader industrial packaging adoption across developing economies.
Global Market Geography
FREE PDF
Request your free sample
Request free sample
Segment Analysis

Industrial Drums Market Segmentation

Product Type

Product type remains a critical determinant of purchasing decisions across industrial applications. This segment accounted for a substantial portion of overall demand, with steel-based solutions maintaining 42%–45% market share in 2025 and growing at 7.8%–8.5% CAGR. The Industrial Drums Market scope continues expanding as manufacturers emphasize durability, sustainability, product compatibility, and regulatory compliance.

  • Steel Drum: Widely used for hazardous chemicals, petroleum products, and industrial liquids due to superior durability, stackability, regulatory compliance capabilities, and strong resistance to demanding transportation and storage conditions.
  • Plastic Drum: Gaining popularity among food, pharmaceutical, and specialty chemical industries because of lightweight characteristics, corrosion resistance, handling efficiency, and compatibility with multiple liquid formulations.
  • Fiber Drum: Preferred in dry bulk and powdered applications where lightweight construction, cost efficiency, sustainability benefits, and ease of disposal provide advantages for industrial users.

Capacity

Capacity selection varies according to transportation requirements, storage practices, product characteristics, and operational efficiency objectives. The segment benefits from increasing industrial output and global trade activity. Mid-sized and larger-capacity products account for a significant share of demand owing to their suitability for chemicals, lubricants, food ingredients, and pharmaceutical applications across complex distribution networks.

  • Less than 100 Liters: Supports specialty chemicals, laboratory applications, premium ingredients, and niche industrial products requiring manageable volumes and flexible handling procedures.
  • 100 to 250 Liters: Represents the most widely utilized capacity category as it balances storage efficiency, transport practicality, regulatory compliance, and product versatility across industries.
  • 251 to 500 Liters: Increasingly adopted for high-volume chemical distribution, lubricant transport, and industrial ingredient storage where operational efficiencies are prioritized.
  • Above 500 Liters: Suitable for bulk industrial operations involving large-volume liquid handling, petrochemical processing, and centralized storage requirements across extensive facilities.

End Use

End-use demand reflects broad industrial adoption and growing movement of liquid and semi-liquid commodities across global supply chains. Chemicals remain the dominant consumer category, while pharmaceuticals represent the fastest-expanding application with 10.1%–10.9% CAGR. The Industrial Drums Market trends indicate increasing demand for traceability, reusability, and compliance-driven packaging solutions throughout key industrial sectors.

  • Food & Beverages: Utilized for transporting syrups, concentrates, edible oils, flavoring ingredients, and bulk food materials while maintaining safety and quality requirements.
  • Chemicals: Represents the largest application area due to extensive requirements for hazardous material containment, transportation reliability, and regulatory compliance.
  • Agriculture: Supports storage and distribution of crop protection chemicals, fertilizers, additives, and agricultural processing materials throughout supply chains.
  • Petroleum & Lubricants: Relies on durable containers capable of safely managing oils, greases, lubricants, and petroleum-derived industrial products.
  • Pharmaceuticals: Benefits from stringent packaging standards, growing biologics production, and increasing international pharmaceutical trade activity.
  • Paints, Inks & Dyes: Requires secure containment solutions that preserve product quality and facilitate efficient transportation and storage operations.
Market Forces

Industrial Drums Market Dynamics

Key Market Drivers

Expansion of Global Chemical Manufacturing Capacity

Investment in the chemical industry in Asia, North America, and the Middle East is still creating steady demand for industrial packaging. Since large quantities of solvents, intermediates, specialty chemicals, and hazardous liquids need dependable methods of storage and transportation, this has led to benefits for the industrial packaging sector caused by rising levels of cross-border trade and the growing volume of downstream manufacturing. Industrial customers are now more likely to choose products that are certified and able to comply with safety and environmental standards. The greater complexity of logistics is encouraging the use of robust and reusable types of packaging.

Growth in Pharmaceutical and Life Sciences Logistics

The pharmaceutical industry is now relying more on secure packaging for active pharmaceutical ingredients, intermediates, and special formulations. The growing production of biologics together with the increase in global pharmaceutical exports means that contamination-resistant transport systems are needed. Because of the ongoing regulatory demands concerning traceability, product integrity and quality assurance, there is a continuing push for the use of high-performance containers. The development of new healthcare manufacturing centres also serves to boost demand. Better cold-chain networks and greater international trade in pharmaceuticals have led to a higher level of requirements when it comes to storage and handling.

Sustainability and Circular Packaging Adoption

The push towards corporate sustainability and the existence of environmental regulations are causing a greater use of industrial containers that are reusable and recyclable. By offering reconditioning services, the length of time that these products last is extended, and at the same time, waste production is reduced, as well as procurement costs are lowered. Nowadays, industrial companies tend to assess packaging according to its performance over its entire lifecycle rather than on the initial cost of acquiring it. Models based on the circular economy help packaging companies to improve their ability to retain customers and to create opportunities for recurring revenue. A growing emphasis on sustainable procurement methods is having a particular impact in the chemicals, food processing, and manufacturing industries.

Key Market Opportunities

Expansion of Reconditioned Packaging Service Models

Reconditioning infrastructure offers attractive growth avenues as industrial buyers seek cost-effective and environmentally responsible packaging solutions. Refurbished steel and plastic containers help reduce lifecycle costs while supporting corporate sustainability commitments. Service-based business models incorporating collection, inspection, cleaning, and redistribution create recurring revenue opportunities for suppliers. Adoption is increasing among chemical producers, lubricant companies, and food ingredient processors aiming to reduce waste. Industrial Drums Market Forecasts increasingly indicate that circular packaging ecosystems will become integral components of procurement strategies.

Growing Demand from Emerging Pharmaceutical Hubs

The expansion of pharmaceutical manufacturing in India, in Southeast Asia, in Latin America and in some Middle Eastern countries is opening up considerable prospects for industrial packaging suppliers. Manufacturers of active ingredients, intermediates and biologics need dependable packaging systems which can meet the requirements relating to regulatory compliance and product integrity. Growth in healthcare spending, higher levels of export activity and the establishment of local drug production programmes are all contributing to increasing demand. Companies creating high-purity container solutions suitable for use in pharmaceutical settings will probably be able to take advantage of high-margin opportunities.

Digital Traceability and Smart Packaging Integration

The use of RFID, QR-coded identification, asset tracking, and lifecycle management technologies is creating new possibilities across industrial logistics networks. There is a growing demand from industrial operators for better visibility regarding the movement of inventory and the way assets are being used. Smart packaging systems contribute to improved compliance, lower losses, and aid in operational efficiency efforts. In the chemical, pharmaceutical, and specialty manufacturing sectors, traceability-enhanced packaging solutions are among the first to have been adopted. Suppliers who are able to combine robust physical products with digital monitoring capabilities can distinguish themselves in ever more competitive situations.

Market Restraints and Challenges

Volatility in Raw Material Costs

The fluctuating prices of steel, plastic resins, energy, and transport inputs continue to create uncertainty in manufacturing operations. This causes fluctuating cost of production, complicates the task of developing pricing strategies, reduces the predictability of profit margins, and adds to the risks involved in procurement on the part of both the manufacturer and the consumer. A sudden change in the cost of raw materials can reduce profit margins and discourage interest in entering into long-term contractual agreements. In highly competitive industries, producers often find it difficult to pass on cost increases to consumers.

Stringent Environmental and Compliance Requirements

The fact that evolving environmental regulations, the standards for the transport of hazardous materials, and the rules relating to waste management place extra compliance demands on manufacturers has an impact in that the costs associated with certification, testing, and documentation may rise, leading to higher operating expenses and longer product development times. Companies are required to continually adapt their products and processes to meet changing regulatory requirements across different countries. When it comes to dealing with the complex compliance requirements, smaller manufacturers generally have more severe resource limitations.

Company Analysis

Competitive Landscape

The competitive environment remains characterized by a mixture of multinational packaging leaders and regional specialists. Ongoing investments in sustainability, reconditioning services, and advanced manufacturing capabilities continue shaping competitive positioning. Industrial Drums Market analysis indicates that companies with broad geographic footprints, circular economy capabilities, and strong industrial customer relationships maintain notable advantages.

Company Name

Overview

Products and Services relevant to this market

Greif, Inc.

Global industrial packaging manufacturer serving chemicals, food, lubricants, and agricultural industries through extensive production and service networks.

Steel drums, plastic drums, fiber drums, intermediate bulk containers, reconditioning services, and industrial packaging solutions.

Mauser Packaging Solutions

International packaging company focused on industrial containers, sustainability initiatives, and closed-loop packaging management services.

Steel drums, plastic drums, packaging recovery programs, reconditioning services, and bulk packaging products.

SCHÜTZ GmbH & Co. KGaA

Leading industrial packaging supplier recognized for innovative container technologies and global manufacturing operations.

Plastic drums, industrial containers, logistics solutions, and sustainable packaging systems.

International Paper Company

Diversified packaging producer with strong expertise across industrial and fiber-based packaging applications.

Fiber drums, industrial packaging materials, and customized containment solutions.

Time Technoplast Ltd.

Major industrial packaging producer with significant presence across Asia and developing markets.

Plastic drums, composite packaging solutions, industrial containers, and specialized packaging products.

Müller Group

European packaging manufacturer serving industrial customers through broad product portfolios and technical expertise.

Steel drums, industrial packaging systems, and customized storage solutions.

Balmer Lawrie & Co. Ltd.

Established supplier with strong presence in industrial packaging and logistics-related operations.

Steel barrels, industrial drums, packaging services, and related logistics solutions.

Sicagen India Limited

Industrial products company supplying packaging and materials solutions across various end-user industries.

Steel drums, storage containers, and industrial packaging products.

Orlando Drum & Container Corporation

North American specialist focused on industrial container distribution and lifecycle management services.

Reconditioned drums, steel containers, plastic containers, and packaging recovery services.

Peninsula Drums Pty Ltd.

Regional packaging provider supporting industrial sectors with durable storage and transport solutions.

Steel drums, plastic drums, reconditioning services, and industrial packaging products.

Trust & Transparency

Research Methodology

The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst review.

View Full Research Methodology

Access the Full Industrial Drums Market Report

Get segment-level forecasts, regional estimates, competitive benchmarking, company profiles and downloadable Excel datasets.

Access the full Industrial Drums Market Report
350 pages PDF & Excel | 2026-09-21
Similar Research

Related Market Reports