
EUV Lithography Market Outlook: Size, Share, Trends, Growth Analysis, Competitive Landscape & Forecast, 2026-2033

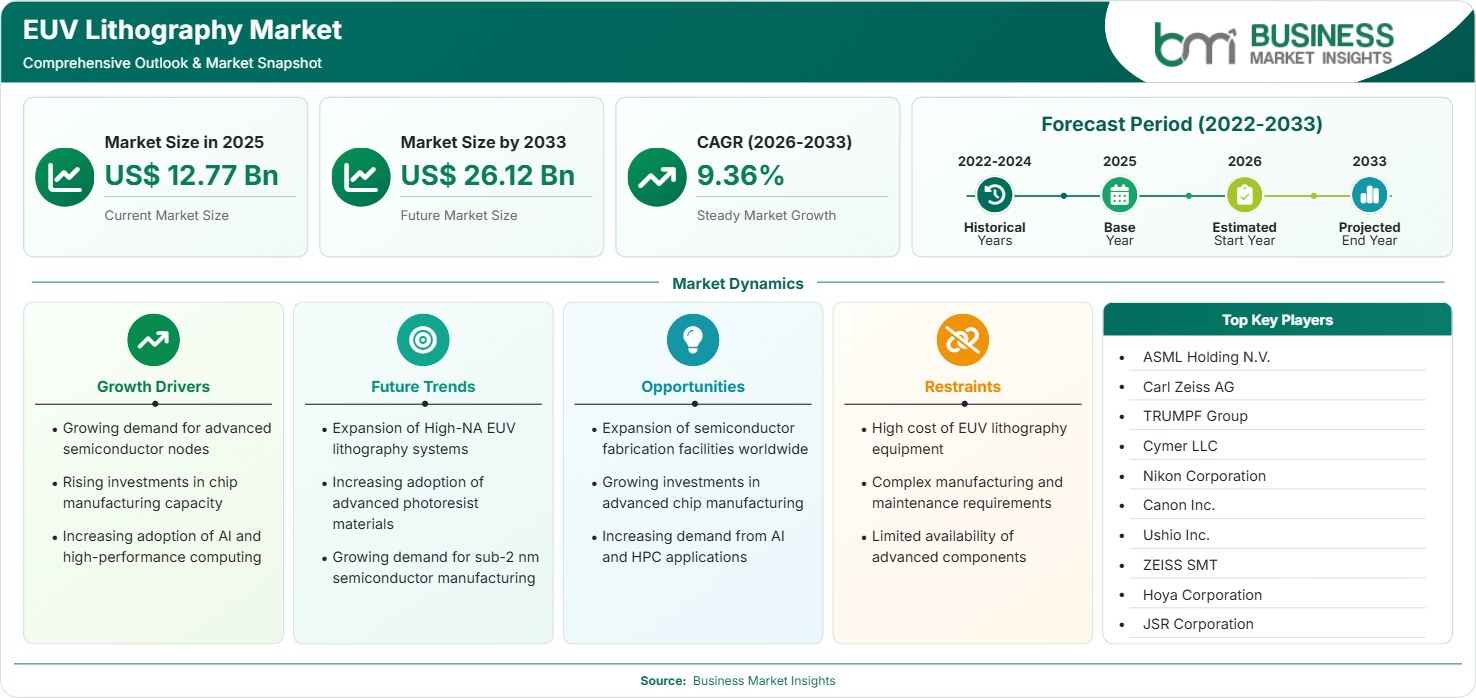
The EUV Lithography Market size was valued at US$ 12.77 Billion in 2025 and is projected to reach US$ 26.12 Billion by 2033, growing at a CAGR of 9.36% during 2026–2033, driven by advanced semiconductor node demand, expanding fabrication investments, AI computing growth, and increasing adoption of next-generation chip manufacturing technologies.

Report Coverage
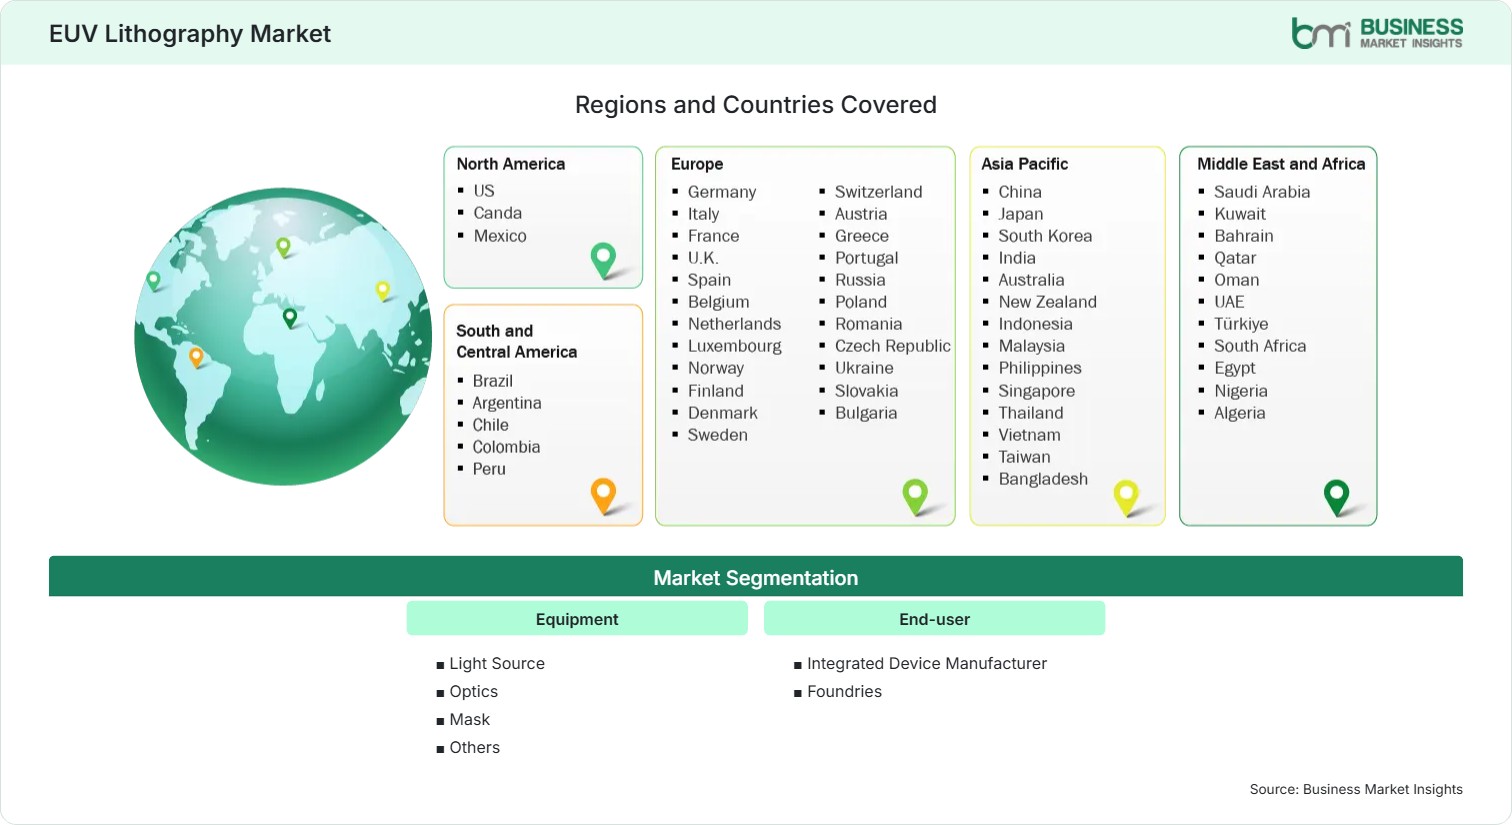
  • Equipment: Light Source, Optics, Mask, Others
  • End-user: Integrated Device Manufacturer, Foundries
US$ 12.77 Bn Market size in 2025
US$ 26.12 Bn Market Size by 2033
9.36% CAGR, 2026 - 2033
2026-2033 Forecast Period

AI Overview

EUV Lithography Market Summary

  • North America Region: North America holds 22%–26% share in 2025, growing at a CAGR of 8.8%–9.4% during 2026–2033, supported by semiconductor reshoring programs, advanced chip investments, AI infrastructure expansion, and government incentives. The US market benefits from new fabrication projects, advanced processor demand, and semiconductor supply chain development, expanding at a CAGR of 8.9%–9.5% during 2026–2033.
  • Fastest Growing Region: Asia Pacific accounts for 55%–60% share in 2025, expanding at a CAGR of 9.8%–10.4% during 2026–2033, driven by semiconductor manufacturing leadership, foundry expansion, advanced node investments, and rising demand from consumer electronics, AI processors, and high-performance computing applications.
  • Leading Segment: Optics represents 35%–40% share in 2025, growing at a CAGR of 9.0%–9.6% during 2026–2033, supported by precision requirements, mirror technology advancements, improved imaging performance, and increasing complexity of extreme ultraviolet semiconductor production systems.
  • High Growth Segment: Light Source accounts for 25%–30% share in 2025, advancing at a CAGR of 10.0%–10.6% during 2026–2033, supported by improvements in EUV power generation, higher wafer throughput requirements, and demand for efficient advanced semiconductor manufacturing equipment.
  • Key Market Opportunity: Expansion of advanced semiconductor fabs, increasing AI accelerator production, and global investments in next-generation chip manufacturing create opportunities for EUV equipment suppliers, component manufacturers, and technology ecosystem participants.
  • Major Market Players: ASML Holding N.V., Carl Zeiss AG, TRUMPF Group, Cymer LLC, Nikon Corporation, Canon Inc., Ushio Inc., ZEISS SMT, Hoya Corporation, and JSR Corporation.
Strategic Insights

EUV Lithography Market: Strategic Insights

EUV Lithography Market Strategic Framework
FREE PDF
Request your free sample
Request free sample
Stakeholder View

Key Takeaways

  • The semiconductor equipment ecosystem is becoming more concentrated around advanced lithography suppliers, precision optics manufacturers, light source specialists, and specialized material providers supporting EUV production.
  • Advanced logic chips, AI processors, and high-performance computing applications represent the strongest demand opportunities as semiconductor companies increase investments in leading-edge fabrication capabilities.
  • Innovation priorities are focused on higher EUV source power, improved imaging accuracy, increased wafer throughput, and reduced operational downtime for advanced manufacturing facilities.
  • Asia Pacific remains the core investment region due to established semiconductor manufacturing clusters, while North America is gaining importance through semiconductor localization initiatives.
  • Strategic partnerships and technology investments are increasing as semiconductor equipment companies seek stronger supply chains for critical components, optics, and specialized manufacturing technologies.
  • The competitive landscape is shaped by technological barriers, high research requirements, and limited supplier availability for advanced lithography components.
Geographic Outlook

EUV Lithography Market Regional Highlights

North America EUV Lithography Market

North America represents 22%–26% share in 2025 and expands at a CAGR of 8.8%–9.4% during 2026–2033. The region is gaining importance due to semiconductor manufacturing investments, AI infrastructure growth, and government-supported chip production initiatives. The EUV Lithography Market share is supported by increasing fab construction and demand for advanced processors. The US remains the primary contributor due to major investments in advanced semiconductor facilities.

  • Semiconductor incentives and domestic manufacturing programs are encouraging new fabrication facility development and increasing demand for advanced lithography equipment.
  • AI chip production growth is supporting investments in leading-edge semiconductor manufacturing capabilities across the region.
  • Research institutions and technology companies are strengthening semiconductor innovation ecosystems through advanced process development initiatives.
  • Equipment suppliers are expanding support networks to address growing requirements from new semiconductor manufacturing facilities.

US EUV Lithography Market

The US market accounts for 18%–22% share in 2025 and grows at a CAGR of 8.9%–9.5% during 2026–2033. Growth is supported by semiconductor manufacturing investments, advanced chip development, and strategic efforts to strengthen domestic supply chains. Leading technology companies are increasing demand for advanced semiconductor production capabilities, particularly for AI processors and high-performance computing applications. Government incentives are accelerating fabrication expansion and creating opportunities for EUV equipment adoption. The EUV Lithography Market is also supported by partnerships between semiconductor manufacturers, equipment providers, and research organizations.

  • New semiconductor fabrication projects are increasing demand for advanced lithography systems and supporting equipment ecosystem development.
  • AI and data center expansion are driving requirements for high-performance chips produced using advanced manufacturing processes.
  • Domestic semiconductor initiatives are improving investment confidence for leading-edge manufacturing projects.
  • Technology companies are increasing collaboration with equipment suppliers to optimize advanced node production.

Europe EUV Lithography Market

Europe holds 12%–16% share in 2025 and grows at a CAGR of 8.5%–9.1% during 2026–2033. The region benefits from semiconductor technology expertise, advanced equipment manufacturing capabilities, and strategic investments in chip production. Germany, the Netherlands, and France represent important markets due to their semiconductor ecosystem strengths. EUV adoption is supported by efforts to improve regional semiconductor resilience and reduce dependency on external supply chains. Equipment innovation and precision component manufacturing remain key contributors to regional competitiveness in EUV Lithography Market.

  • The Netherlands plays a critical role through advanced semiconductor equipment expertise and specialized technology development.
  • Germany supports semiconductor manufacturing through industrial capabilities, research infrastructure, and precision engineering expertise.
  • European semiconductor initiatives are encouraging investments in advanced fabrication and technology partnerships.
  • Component manufacturers are strengthening capabilities for optics, materials, and specialized EUV system requirements.
  • Regional research programs continue supporting semiconductor innovation and manufacturing competitiveness.

Asia Pacific EUV Lithography Market

Asia Pacific dominates with 55%–60% share in 2025 and records the fastest growth at a CAGR of 9.8%–10.4% during 2026–2033. The region remains the largest semiconductor manufacturing hub due to advanced foundry capacity, electronics production, and technology investments. Taiwan, South Korea, Japan, and China represent major markets. Strong demand from logic chips, memory devices, AI processors, and consumer electronics continues supporting EUV Lithography Market forecasts. Regional semiconductor companies are expanding fabrication capacity to maintain leadership in advanced manufacturing.

  • Taiwan remains a major market due to leading foundry capabilities and advanced semiconductor production investments.
  • South Korea is increasing EUV adoption through memory and logic semiconductor manufacturing expansion.
  • Japan supports the ecosystem through semiconductor materials, components, and technology expertise.
  • China is investing in semiconductor capabilities while developing domestic alternatives across the supply chain.
  • Regional demand is strengthened by electronics manufacturing and AI hardware development.

Rest of World EUV Lithography Market

Rest of World markets represent 4%–8% share in 2025 and expand at a CAGR of 7.8%–8.5% during 2026–2033. Latin America, the Middle East, and other emerging regions have limited current EUV adoption but present long-term opportunities through semiconductor ecosystem development and technology investments. Governments and technology companies are exploring semiconductor manufacturing capabilities to strengthen digital infrastructure in EUV Lithography Market. Growth remains dependent on investment scale, technical expertise, and availability of supporting semiconductor infrastructure.

  • Emerging regions are evaluating semiconductor investments to support digital transformation and technology independence.
  • Middle Eastern economies are exploring advanced technology industries through diversification and innovation initiatives.
  • Latin American markets are developing electronics and technology capabilities through strategic investments.
  • Semiconductor ecosystem development remains dependent on skilled workforce availability and infrastructure readiness.
  • Long-term opportunities exist through partnerships with established semiconductor manufacturing regions.
Global Market Geography
FREE PDF
Request your free sample
Request free sample
Segment Analysis

EUV Lithography Market Segmentation

Equipment

Equipment segmentation represents the core technology foundation of the EUV Lithography Market, covering critical systems required for semiconductor patterning at advanced nodes. Optics accounted for 35%–40% share in 2025 and is projected to grow at a CAGR of 9.0%–9.6% during 2026–2033. Growth is supported by increasing precision requirements, advanced mirror technologies, and rising demand for higher-resolution semiconductor manufacturing capabilities.

  • Light Source: Light source systems are essential for generating extreme ultraviolet wavelengths required for advanced chip fabrication. Demand is increasing through higher power requirements, improved throughput, and continuous technology development.
  • Optics: Optics represents the largest equipment component due to complex mirror systems, precision engineering requirements, and the need for improved imaging accuracy in advanced semiconductor production environments.
  • Mask: EUV masks are gaining importance as semiconductor designs become more complex. Growth is supported by advanced pattern requirements, improved mask quality, and increasing demand for defect-free manufacturing processes.

End-user

End-user segmentation reflects growing adoption among semiconductor manufacturers investing in advanced fabrication capabilities. Foundries represented 55%–60% share in 2025 and are expected to grow at a CAGR of 9.5%–10.1% during 2026–2033. Demand is driven by expansion of advanced node production, increasing outsourcing of semiconductor manufacturing, and rising requirements for AI and high-performance computing chips in EUV Lithography Market.

  • Integrated Device Manufacturer: Integrated device manufacturers continue adopting EUV systems to maintain control over advanced semiconductor production. Investments focus on improving process capability, chip performance, and manufacturing competitiveness.
  • Foundries: Foundries are the leading end-user segment due to increasing demand from semiconductor designers requiring outsourced advanced manufacturing capacity. Expansion of leading-edge fabrication facilities continues supporting EUV adoption.
Market Forces

EUV Lithography Market Dynamics

Key Market Drivers

Growing Demand for Advanced Semiconductor Nodes

The transition toward smaller semiconductor process nodes is a primary driver accelerating EUV adoption across the semiconductor industry. Chip manufacturers are increasingly using advanced lithography technologies to produce processors with higher performance, lower power consumption, and improved transistor density. Demand from AI accelerators, premium smartphones, automotive electronics, and high-performance computing systems is encouraging investments in advanced fabrication capabilities. The EUV Lithography Market growth is closely linked with semiconductor manufacturers’ efforts to maintain technology leadership at leading-edge nodes. Increasing design complexity and performance requirements are pushing manufacturers beyond traditional lithography approaches. Equipment suppliers are responding through improvements in source power, imaging accuracy, and system productivity to support next-generation chip production.

Rising Investments in Chip Manufacturing Capacity

Global semiconductor capacity expansion is creating strong demand for advanced manufacturing equipment as companies and governments prioritize supply chain resilience. Major semiconductor regions are investing in new fabrication facilities to increase domestic production capabilities and reduce dependency on concentrated manufacturing locations. These investments are supporting procurement of advanced lithography systems required for leading-edge semiconductor production. The expansion of foundries and integrated device manufacturing facilities is increasing the addressable market for EUV equipment suppliers. Government incentives, including semiconductor manufacturing support programs, are encouraging companies to accelerate construction timelines and technology upgrades. This capacity expansion trend is expected to remain a major contributor to long-term equipment demand.

Increasing Adoption of AI and High-Performance Computing

The fast adoption of artificial intelligence and advanced computing applications is boosting the need for advanced semiconductors that are fabricated through state-of-the-art semiconductor fabrication processes. Advanced AI processors, advanced graphics processors, and advanced processors used in data centers need better performance, efficiency, and more transistors, hence the adoption of EUV in the manufacture of semiconductors. The rise in cloud computing infrastructure and the need for more computing is pushing tech companies to invest in advanced semiconductor supply chains. The semiconductor manufacturer are expanding their capabilities to meet the demand from AI and data center hardware makers.

Key Market Opportunities

Expansion of Semiconductor Fabrication Facilities Worldwide

Global spread of semiconductor fabrications offers immense prospects to EUV equipment vendors. Nations around the world in North America, Europe, and Asia Pacific are building new fabs to enhance their semiconductor production lines and advance the construction of digital infrastructure. New fab constructions will need advanced lithography technologies that would allow producing state-of-the-art chips for computer, automotive, and consumer electronics applications. Vendors will be able to profit from technology partnership deals and maintenance contracts connected to those fabs. Regional semiconductor development initiatives are promoting investments into the development of the ecosystem around semiconductor production that includes materials, components, and engineering services.

Growing Investments in Advanced Chip Manufacturing

Growing investment in chip manufacturing technology is opening up many possibilities for firms specializing in EUV systems, high-quality components, and semiconductor process technologies. Semiconductor makers are spending a lot of money to boost their capabilities, raise wafer output, and reduce process nodes. Investment in advanced manufacturing is backed by the demand for artificial intelligence, automotive electronics, telecommunications, and high-performance computing industries. Companies that can supply dependable machinery, components, and services have many opportunities in building up the semiconductor industry infrastructure. The need for ongoing technological upgrading also creates many opportunities in enhancing systems and raising productivity in already operating manufacturing facilities.

Increasing Demand from AI and HPC Applications

AI and high-performance computing applications represent a major opportunity area as technology companies require increasingly powerful semiconductor solutions. Advanced processors used in data centers, machine learning systems, and accelerated computing platforms require sophisticated manufacturing processes supported by EUV technology. The semiconductor producers are making substantial investments in advanced manufacturing capabilities to cater to the demand for high-performance semiconductors. Equipment makers may benefit from collaborations with semiconductor manufacturers to improve efficiency and expand advanced-node manufacturing. It is likely that the steady development of cloud computing, generative AI, and data applications will sustain robust demand for advanced semiconductors.

Market Restraints and Challenges

High Cost of EUV Lithography Equipment

Factor: EUV lithography systems require extremely high capital investment due to complex optical components, advanced light source technology, and precision engineering requirements. Impact: High equipment costs can limit adoption among smaller semiconductor manufacturers and increase capital expenditure requirements for new fabrication facilities. High utilization is imperative for the justification of investments and maintenance of manufacturing economics. The cost burden goes far beyond capital expenditure in terms of installation costs, operational costs, and upgrade costs. Those semiconductor companies that have a sound financial base and capabilities of production can better adapt to EUV systems. Cost reductions and productivity increases continue to be very important.

Complex Manufacturing and Maintenance Requirements

Factor: EUV systems involve highly sophisticated technologies requiring specialized manufacturing processes, advanced engineering expertise, and continuous maintenance support. Impact: Technical complexity can increase operational challenges, extend installation timelines, and require significant workforce expertise. Semiconductor manufacturers must maintain strict environmental controls and precise operating conditions to achieve consistent production performance. Equipment downtime can significantly affect manufacturing output due to the critical role of lithography systems in semiconductor production. Suppliers are focusing on improving system reliability, service capabilities, and predictive maintenance technologies to address these challenges. The complexity of EUV technology remains a key barrier affecting adoption speed across semiconductor manufacturing markets.

Company Analysis

Competitive Landscape

The EUV Lithography Market analysis highlights a highly concentrated competitive environment driven by advanced semiconductor equipment expertise, precision engineering capabilities, intellectual property strength, and long-term technology partnerships. Companies are focusing on improving EUV system performance, optical precision, source power efficiency, and component reliability to support next-generation semiconductor manufacturing.

Company Name

Overview

Products and Services relevant to this market

ASML Holding N.V.

ASML Holding N.V. is the leading global semiconductor lithography equipment provider and the primary supplier of commercial EUV systems.

Provides EUV lithography systems, advanced semiconductor manufacturing equipment, upgrades, and lifecycle support services.

Carl Zeiss AG

Carl Zeiss AG is a German precision optics company specializing in advanced optical technologies for semiconductor applications.

Develops high-precision EUV optics, mirror systems, and optical components used in advanced lithography equipment.

TRUMPF Group

TRUMPF Group is a German technology company providing laser and industrial solutions for semiconductor manufacturing.

Supplies high-power laser technology used in EUV light generation systems and advanced manufacturing applications.

Cymer LLC

Cymer LLC is a semiconductor technology company specializing in laser-produced plasma EUV light source solutions.

Provides EUV light source technologies, service solutions, and performance optimization systems for lithography platforms.

Nikon Corporation

Nikon Corporation is a Japanese precision equipment manufacturer with expertise in semiconductor lithography technologies.

Offers semiconductor lithography systems, precision imaging technologies, and advanced manufacturing equipment solutions.

Canon Inc.

Canon Inc. is a global imaging and precision technology company serving semiconductor manufacturing markets.

Provides semiconductor lithography equipment, nanoimprint technologies, and related precision manufacturing solutions.

Ushio Inc.

Ushio Inc. develops optical technologies and light source solutions for industrial and semiconductor applications.

Supplies specialized light sources, optical components, and semiconductor process technologies.

ZEISS SMT

ZEISS SMT is the semiconductor technology division of ZEISS focused on advanced lithography solutions.

Provides EUV optical systems, precision mirrors, and semiconductor manufacturing components.

Hoya Corporation

Hoya Corporation is a Japanese technology company specializing in optical materials and advanced components.

Manufactures photomasks, optical materials, and semiconductor-related products supporting advanced chip production.

JSR Corporation

JSR Corporation is a Japanese materials technology company serving semiconductor manufacturing industries.

Provides semiconductor materials, photoresists, and process solutions supporting advanced lithography applications.

Trust & Transparency

Research Methodology

The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst review.

View Full Research Methodology

Questions Answered

Frequently Asked Questions

How are semiconductor supply chain strategies affecting EUV Lithography Market report?

Global semiconductor localization initiatives are encouraging new fabrication investments across multiple regions, increasing demand for advanced manufacturing equipment and supporting broader adoption of EUV lithography technologies.

What limits wider adoption of EUV lithography market trends?

High capital investment requirements, complex operating conditions, specialized maintenance needs, and limited availability of technical expertise restrict adoption among smaller semiconductor manufacturers.

What industries are increasing demand for EUV-produced chips?

Artificial intelligence, cloud computing, automotive electronics, telecommunications, consumer electronics, and high-performance computing industries are increasing demand for advanced semiconductors manufactured using EUV technology.

Which companies are leading EUV lithography technology development?

ASML Holding N.V. leads commercial EUV system development, supported by specialized technology providers including ZEISS SMT, TRUMPF Group, Cymer LLC, and semiconductor material suppliers contributing critical components.

Why is EUV lithography important for advanced semiconductor manufacturing?

EUV lithography enables semiconductor manufacturers to create smaller and more complex chip designs by improving patterning capabilities. It supports advanced processors used in AI, high-performance computing, smartphones, automotive electronics, and data center applications.

Access the Full EUV Lithography Market Report

Get segment-level forecasts, regional estimates, competitive benchmarking, company profiles and downloadable Excel datasets.

Access the full EUV Lithography Market Report
350 pages PDF & Excel | 2026-08-07
Similar Research

Related Market Reports