
Wind Turbine Operation and Maintenance Market Outlook: Size, Share, Trends, Growth Analysis, Competitive Landscape & Forecast, 2026-2033

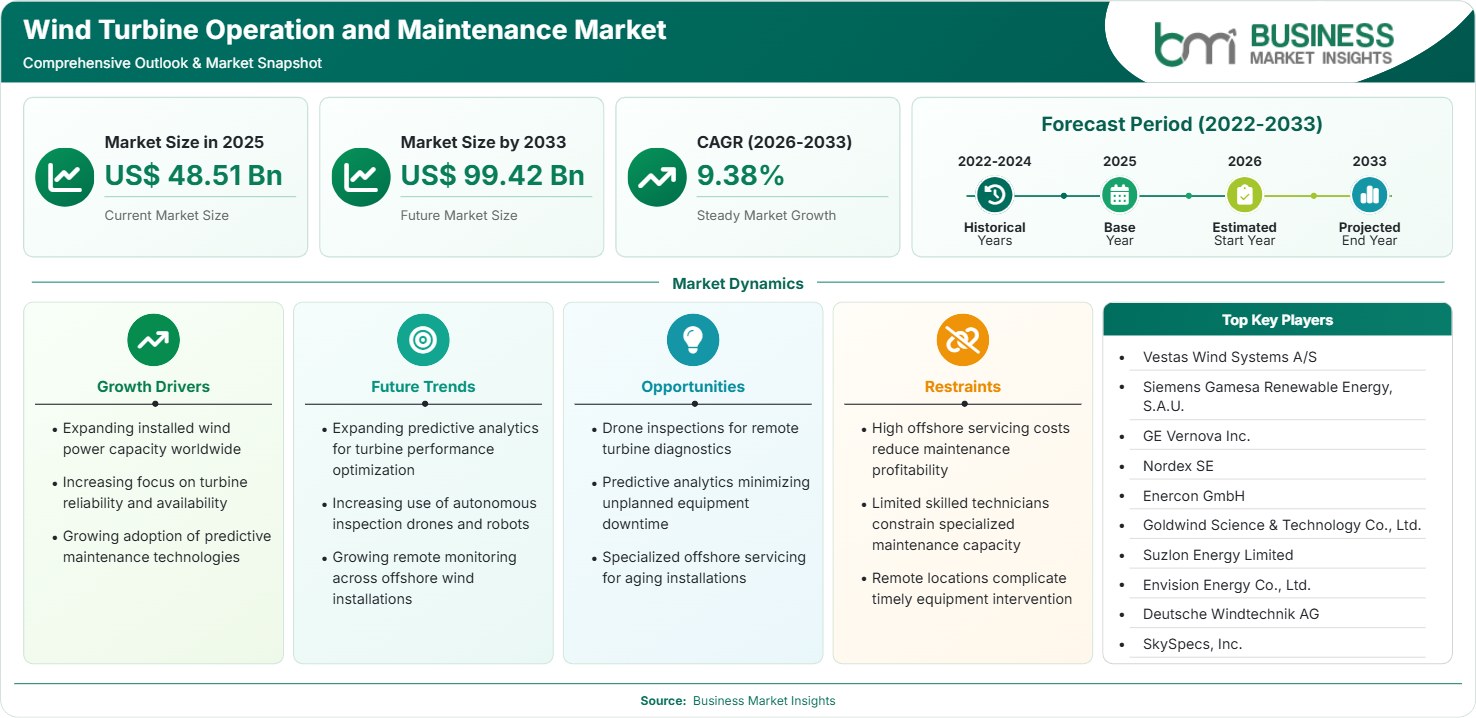
The Wind Turbine Operation and Maintenance Market size was valued at US$ 48.51 Billion in 2025 and is projected to reach US$ 99.42 Billion by 2033, growing at a CAGR of 9.38% during 2026–2033. Rising installed wind capacity, aging turbine fleets, predictive maintenance adoption, offshore wind expansion, and digital asset management platforms are creating strong revenue opportunities across global service ecosystems.

Report Coverage
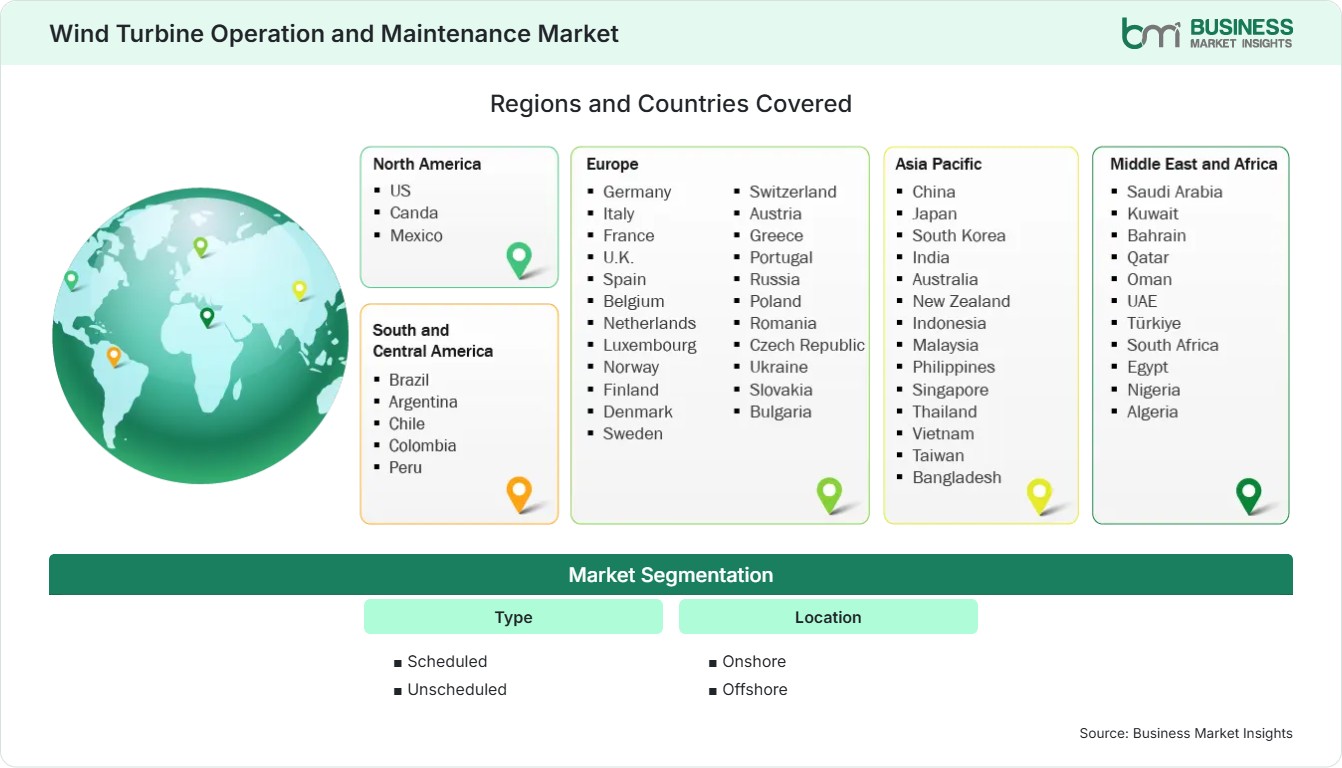
  • Type: Scheduled, Unscheduled
  • Location: Onshore, Offshore
US$ 48.51 Bn Market size in 2025
US$ 99.42 Bn Market Size by 2033
9.38% CAGR, 2026 - 2033
2026-2033 Forecast Period

AI Overview

Wind Turbine Operation and Maintenance Market Summary

  • North America Region: North America holds a market share of 32%–35% in 2025, growing with a CAGR of 8.4%–8.9% during 2026–2033. Key drivers include aging wind assets, repowering programs, predictive diagnostics adoption, grid modernization investments, expanding long-term service agreements, and increasing turbine uptime optimization requirements across utility operators. The US maintains regional leadership through large installed wind fleets and service contract expansion, advancing at 8.5%–9.0% CAGR.
  • Fastest Growing Region: Asia Pacific holds a market share of 27%–30% in 2025 and is expected to grow at a CAGR of 10.8%–11.4%. Expanding offshore installations, government renewable targets, increasing turbine deployment, digital monitoring integration, local service network development, and asset life extension programs support strong growth.
  • Leading Segment: Onshore location accounts for 74%–78% share in 2025 with a CAGR of 8.8%–9.3%. Large installed bases, lower servicing complexity, favorable access conditions, expanding predictive maintenance adoption, aging turbine populations, and repowering activities sustain segment leadership worldwide.
  • High Growth Segment: Offshore location represents 22%–26% share in 2025 while growing at 11.2%–11.9% CAGR. Increasing offshore capacity additions, greater maintenance intensity, specialized vessel requirements, digital inspections, larger turbine deployment, and performance optimization services accelerate revenue generation.
  • Key Market Opportunity: AI-enabled condition monitoring, drone-based inspections, digital twins, and predictive asset management platforms can reduce downtime, improve turbine availability, lower service costs, extend component life, and strengthen operator profitability.
  • Major Market Players: Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy, S.A.U., GE Vernova Inc., Nordex SE, Enercon GmbH, Goldwind Science & Technology Co., Ltd., Suzlon Energy Limited, Envision Energy Co., Ltd., Deutsche Windtechnik AG, and SkySpecs, Inc.
Strategic Insights

Wind Turbine Operation and Maintenance Market: Strategic Insights

Wind Turbine Operation and Maintenance Market Strategic Framework
FREE PDF
Request your free sample
Request free sample
Stakeholder View

Key Takeaways

  • The ecosystem for the service sector is shifting from a model in which manufacturers took the lead in providing maintenance to a hybrid model that includes original equipment manufacturers, independent service providers, software companies, specialists in drone inspections, and vendors that provide predictive analytics.
  • The offshore assets have the greatest potential for increased revenue since they involve higher levels of maintenance, more complicated logistics, and greater spending per megawatt than similar onshore installations.
  • Digital twins, AI-powered diagnostics, robotics, and automated inspections are changing maintenance practices to move from a reactive style of intervention to one based on predictive asset management.
  • The investment landscape in the Asia Pacific is the most attractive one because of the large number of new wind farms being installed, the expansion of offshore projects, and the growing demand for local maintenance capabilities.
  • Industry participants continue to pursue acquisitions, strategic partnerships, and long-term service agreements to strengthen service portfolios and secure recurring revenue streams.
  • The aging fleets of turbines in North America and Europe are driving greater demand for repowering, component replacement, and life-extension services to improve operating economics.
Geographic Outlook

Wind Turbine Operation and Maintenance Market Regional Highlights

North America Wind Turbine Operation and Maintenance Market

North America accounted for approximately 32%–35% Wind Turbine Operation and Maintenance Market share in 2025 and is projected to record 8.4%–8.9% CAGR through 2033. The region benefits from mature wind infrastructure, extensive installed capacity, and increasing requirements for life-extension services. Utilities are adopting predictive maintenance technologies to improve operational efficiency while reducing downtime. Repowering programs and multi-year service agreements continue strengthening service revenues, particularly across the United States and Canada.

  • The need to replace gearboxes, refurbish blades, and install advanced monitoring systems is growing due to the repowering of older wind farms.
  • Turbine owners are increasingly adopting independent service providers to find more cost-effective options than those offered by the original equipment manufacturers.
  • The use of drones for blade inspections is helping to reduce maintenance downtime while improving worker safety and inspection frequency.
  • The initiatives aimed at modernizing the grid enable improved asset monitoring and the implementation of integrated strategies to optimize performance.

US Wind Turbine Operation and Maintenance Market

The United States represents approximately 78%–82% of the regional Wind Turbine Operation and Maintenance Market revenue and is expected to expand at 8.5%–9.0% CAGR. Large installed wind capacity, supportive renewable policies, and increasing focus on asset performance management support long-term market development. Fleet aging is encouraging investments in predictive diagnostics, component replacement programs, and life-extension strategies. Strong participation from OEMs and independent service companies enhances competitive intensity.

  • Texas, Iowa, Oklahoma, and Kansas are still major centers for maintenance because of the large number of wind generation assets.
  • Operators are now using AI-based monitoring to detect component failures before unexpected outages occur.
  • Long-term service agreements help companies plan their income and schedule maintenance before problems occur.
  • Investments in repowering are still increasing, as operators seek to improve energy output and operational efficiency.

Europe Wind Turbine Operation and Maintenance Market

Europe held 28%–31% Wind Turbine Operation and Maintenance Market share in 2025 and is expected to expand at 8.7%–9.2% CAGR. Strong offshore wind deployment, ambitious renewable targets, and aging installed capacity support steady demand. Germany leads regional revenue generation, while the United Kingdom demonstrates the fastest offshore-driven expansion. Advanced digitalization initiatives and established service infrastructure enhance maintenance efficiency and asset reliability.

  • Germany remains the largest national market, due to its large number of onshore assets and repowering investments.
  • The United Kingdom's growth was due to large offshore maintenance contracts and demand for vessels.
  • Denmark and the Netherlands are still investing in the expansion of their offshore capacity and in service innovation.
  • Digital twins and condition-monitoring systems are increasingly being used by the major wind operators.
  • The policies aimed at reducing carbon emissions are still promoting the expansion of wind energy and the demand for the related services.

Asia Pacific Wind Turbine Operation and Maintenance Market

Asia Pacific accounted for 27%–30% Wind Turbine Operation and Maintenance Market share in 2025 and is forecast to grow at 10.8%–11.4% CAGR, making it the fastest-growing region. Rapid expansion of onshore and offshore wind installations, manufacturing advantages, and supportive renewable energy policies underpin market development. China dominates regional demand, while India and Vietnam present attractive high-growth opportunities. Increasing digitalization and localized service ecosystems further strengthen market prospects.

  • China is leading the region in revenue due to the large amount of wind capacity it has installed and the scale of its maintenance facilities.
  • India is gaining advantages due to the expansion of its fleet, the aging of its turbines, and the growing use of predictive maintenance technologies.
  • Vietnam and South Korea are becoming increasingly appealing as offshore service markets.
  • Local service providers are helping boost regional competitiveness by offering cost-effective maintenance options.
  • The increasing level of investment in renewable energy continues to drive strong demand for maintenance services.

Rest of World Wind Turbine Operation and Maintenance Market

Rest of World represents 8%–11% Wind Turbine Operation and Maintenance Market share and is anticipated to grow at 9.0%–9.6% CAGR. South and Central America benefit from the expansion of wind portfolios in Brazil and Chile, while the Middle East and African markets gain momentum through renewable diversification initiatives. Infrastructure development and grid modernization projects continue supporting new installations and associated service requirements.

  • Brazil remains the biggest opportunity in Latin America due to the rapid expansion of its wind capacity.
  • There is an increasing number of investments being made in long-term maintenance agreements and digital operations platforms in Chile.
  • Saudi Arabia and the UAE are currently expanding their renewable energy portfolios to meet future operation and maintenance requirements.
  • South Africa is still a significant market in Africa and is seeing an increase in utility-scale wind projects.
  • Regional localization strategies help make services more available and improve response times.
Global Market Geography
FREE PDF
Request your free sample
Request free sample
Segment Analysis

Wind Turbine Operation and Maintenance Market Segmentation

Type

Scheduled maintenance accounted for approximately 58%–62% market share in 2025 and is expected to grow at 8.8%–9.3% CAGR. The Wind Turbine Operation and Maintenance Market scope continues expanding as operators prioritize preventive servicing, asset reliability, and performance optimization. Increasing use of predictive analytics and condition monitoring supports maintenance planning and reduces unexpected failures.

  • Scheduled: Preventive inspections, lubrication programs, component monitoring, and planned servicing improve turbine availability, reduce lifecycle costs, and support long-term operational efficiency across utility-scale wind farms.
  • Unscheduled: Corrective maintenance addresses unexpected equipment failures, component damage, and emergency repairs. Growth is supported by aging fleets, severe weather exposure, and increasing operational complexity.

Location

The Wind Turbine Operation and Maintenance Market trends indicate onshore installations remain dominant with 74%–78% share in 2025 and projected 8.8%–9.3% CAGR. Offshore assets, however, generate higher maintenance expenditure per turbine due to demanding environments, specialized logistics, and advanced inspection requirements, supporting stronger long-term service revenues.

  • Onshore: Easier site accessibility, established maintenance infrastructure, and large installed turbine volumes support continuing demand for preventive services and operational performance enhancement.
  • Offshore: Harsh operating environments, vessel dependency, complex logistics, and larger turbine capacities drive demand for sophisticated maintenance technologies and specialized service expertise.
Market Forces

Wind Turbine Operation and Maintenance Market Dynamics

Key Market Drivers

Expansion of Global Installed Wind Capacity

Global wind deployment continues to accelerate as governments pursue decarbonization agendas and renewable energy targets. Every new turbine installation creates recurring service requirements throughout operational lifecycles. The Wind Turbine Operation and Maintenance Market's growth is increasingly tied to installed capacity expansion, particularly in Asia-Pacific and offshore Europe. Wind fleets commissioned over previous decades are entering phases requiring more intensive inspection, repair, and component replacement. Asset owners are prioritizing availability improvements because even minor efficiency gains materially affect project economics. Continued growth in utility-scale deployments ensures a steadily expanding addressable maintenance base and recurring service opportunities.

Adoption of Predictive Maintenance Technologies

Digital transformation is having a profound effect on how asset management is carried out across wind energy portfolios. Nowadays, operators are increasingly using condition-monitoring systems, AI analytics, vibration monitoring, drones, and digital twins to detect potential failures before they lead to costly outages. These technologies not only reduce maintenance costs but also enhance operational reliability. With real-time performance insights, maintenance providers can better plan workforce deployment and manage spare parts. As turbine capacities rise and projects are spread across larger geographic areas, predictive maintenance has become essential to maximize energy production. The increasing demand for data-driven operational efficiency continues to drive the rapid adoption of sophisticated maintenance technologies.

Growth of Offshore Wind Installations

Since the conditions at sea, the difficulties in accessing the sites, and the need for specialized equipment mean that offshore wind projects involve much higher maintenance costs, the expansion of offshore investments in Europe and the Asia Pacific region is opening up long-term possibilities for service providers. Higher turbine ratings, the development of floating wind farms, and the fact that assets are located in remote areas are all driving greater demand for advanced monitoring systems, inspection technologies, and specialized vessels. Operators are increasingly seeking integrated service contracts to reduce downtime and improve reliability. Offshore expansion will therefore continue to be a key driver of long-term revenue in maintenance service ecosystems.

Key Market Opportunities

AI-Driven Asset Performance Management Platforms

There is a significant investment opportunity in leveraging artificial intelligence for turbine operations. By analyzing the data obtained from sensors, SCADA systems and monitoring equipment, it is possible to predict failures, optimize maintenance schedules and improve asset performance. Manufacturers creating scalable analytics platforms are expected to benefit from rising operator demand for greater operational efficiency. As turbine fleets become more complex, the advantages of AI-powered maintenance solutions are growing. With digital transformation progressing rapidly, software-based revenue models present attractive growth prospects for wind energy portfolios worldwide.

Life Extension and Repowering Programs

A growing percentage of wind assets are approaching the end of their original design lifetimes. Asset owners increasingly evaluate life-extension strategies and repowering projects to maximize returns. This trend creates demand for component replacement, structural assessments, gearbox refurbishment, and advanced engineering services. Wind Turbine Operation and Maintenance Market Forecasts increasingly reflect strong revenue contributions from aging fleet management. Service providers capable of delivering cost-effective upgrade solutions stand to benefit from expanding repowering activity and operational optimization requirements.

Independent Multi-Brand Service Expansion

The end of the OEM warranty periods is causing turbine owners to consider a wider range of maintenance sourcing options. Since independent companies have expertise across a variety of brands, they can offer competitive pricing and tailored support. This opens the possibility of extending maintenance coverage to mixed turbine fleets. The increasing demand for flexibility, local service, and cost efficiency is promoting greater acceptance of non-OEM maintenance arrangements. Those firms that invest in technical personnel, spare parts capabilities, and digital platforms are likely to gain a larger share of the market.

Market Restraints and Challenges

Skilled Workforce Constraints and Service Delays

There is a growing demand in the industry for technicians who can service modern wind turbine systems, driven by shortages of specialist workers in blade repair, offshore operations, and digital diagnostics. This situation has led to delays in maintenance scheduling, higher labor costs, longer downtime, and reduced operational efficiency. Offshore projects are especially at risk since they demand highly skilled personnel and specific certifications. With global installations continuing to increase, workforce development has become a strategic priority. Companies that are unable to obtain qualified staff may encounter difficulties maintaining service quality and meeting contract requirements.

Supply Chain Disruptions and Higher Operating Costs

The need for maintenance work depends on the availability of replacement parts, logistics infrastructure, and specialized equipment. Disruptions to the supply chain affect blades, gearboxes, bearings, electronics, and transport networks. This results in higher maintenance costs, delayed repairs, longer periods without service, and less availability of the assets. The combined effect of inflation and uncertainties in global trade makes inventory planning more difficult. While service providers are increasingly likely to establish local stock and adopt predictive spare parts management, supply chain volatility remains a major operational problem.

Company Analysis

Competitive Landscape

The following competitive assessment supports broader Wind Turbine Operation and Maintenance Market analysis by highlighting major participants operating across OEM services, independent maintenance, digital monitoring, and lifecycle optimization.

Company Name

Overview

Products and Services relevant to this market

Vestas Wind Systems A/S

Global wind turbine manufacturer with extensive service operations and long-term maintenance portfolio.

Predictive maintenance, turbine servicing, monitoring solutions, spare-parts management, performance optimization.

Siemens Gamesa Renewable Energy, S.A.U.

Major onshore and offshore wind technology provider with strong service capabilities.

O&M contracts, offshore logistics, diagnostics, condition monitoring, lifecycle management.

GE Vernova Inc.

Renewable energy company supporting large global wind turbine installations.

Maintenance services, digital analytics, performance upgrades, component replacement programs.

Nordex SE

International turbine supplier serving utility-scale wind projects globally.

Service agreements, inspections, monitoring, technical support, operational optimization.

Enercon GmbH

Germany-based wind energy specialist with broad aftermarket support network.

Turbine maintenance, engineering services, spare parts, operational management.

Goldwind Science & Technology Co., Ltd.

Leading Chinese wind turbine manufacturer with expanding service business.

Lifecycle services, predictive maintenance, remote monitoring, technical consulting.

Suzlon Energy Limited

Prominent wind energy company with strong presence in India.

Asset management, maintenance support, inspections, performance enhancement services.

Envision Energy Co., Ltd.

Renewable technology company focused on digital energy solutions.

Smart maintenance platforms, monitoring systems, asset analytics, optimization services.

Deutsche Windtechnik AG

Independent service specialist servicing multi-brand turbine fleets globally.

Independent O&M, inspections, repair services, technical consulting, retrofits.

SkySpecs, Inc.

Technology company specializing in automated inspections and analytics.

Drone inspections, data analytics, asset monitoring, predictive maintenance solutions.

Trust & Transparency

Research Methodology

The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst review.

View Full Research Methodology

Questions Answered

Frequently Asked Questions

What makes independent service providers increasingly important?

As turbine warranties expire, operators seek flexible and cost-efficient maintenance alternatives, creating opportunities for multi-brand independent service providers.

How does a Wind Turbine Operation and Maintenance Market Report support strategic planning?

It helps stakeholders evaluate demand patterns, competitive positioning, regional opportunities, emerging technologies, service revenue potential, and investment priorities.

Which technologies are transforming turbine maintenance operations?

Artificial intelligence, digital twins, drones, robotics, condition monitoring systems, and predictive analytics are improving reliability while reducing downtime and maintenance costs.

Why is offshore wind maintenance growing faster than onshore maintenance?

Offshore assets require specialized vessels, complex logistics, skilled personnel, and advanced monitoring systems, resulting in higher maintenance intensity and faster revenue growth.

What factors are increasing maintenance spending in wind energy projects?

Larger turbines, offshore deployment, aging fleets, predictive maintenance investments, and stricter performance requirements are increasing maintenance expenditures across global wind assets.

Access the Full Wind Turbine Operation and Maintenance Market Report

Get segment-level forecasts, regional estimates, competitive benchmarking, company profiles and downloadable Excel datasets.

Access the full Wind Turbine Operation and Maintenance Market Report
350 pages PDF & Excel | 2026-09-15
Similar Research

Related Market Reports