
Kidney Stone Management Devices Market Outlook: Size, Share, Trends, Growth Analysis, Competitive Landscape & Forecast, 2026–2033

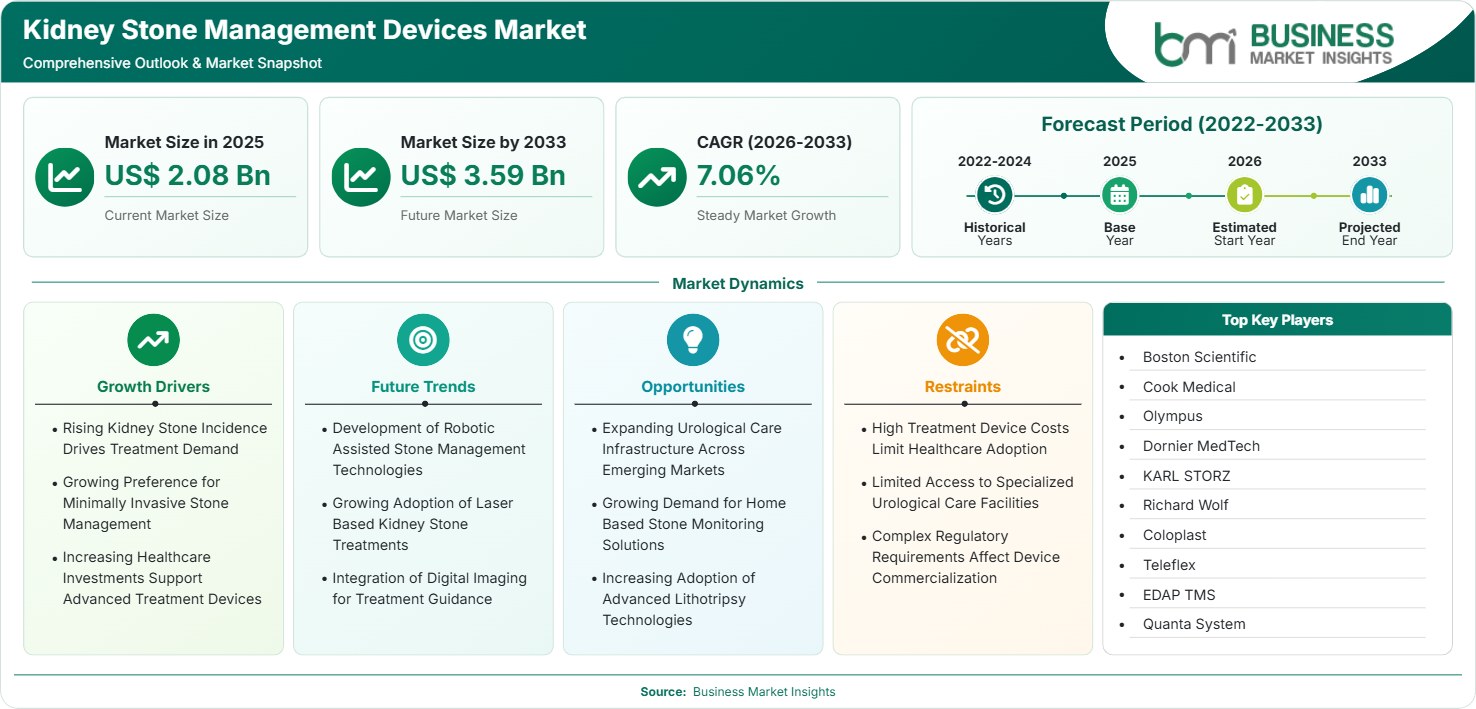
The Kidney Stone Management Devices Market size was valued at US$ 2.08 billion in 2025 and is projected to reach US$ 3.59 billion by 2033, growing at a CAGR of 7.06% during 2026–2033, supported by rising kidney stone incidence, minimally invasive treatment preference, healthcare infrastructure expansion, advanced lithotripsy adoption, and outpatient care.

Report Coverage
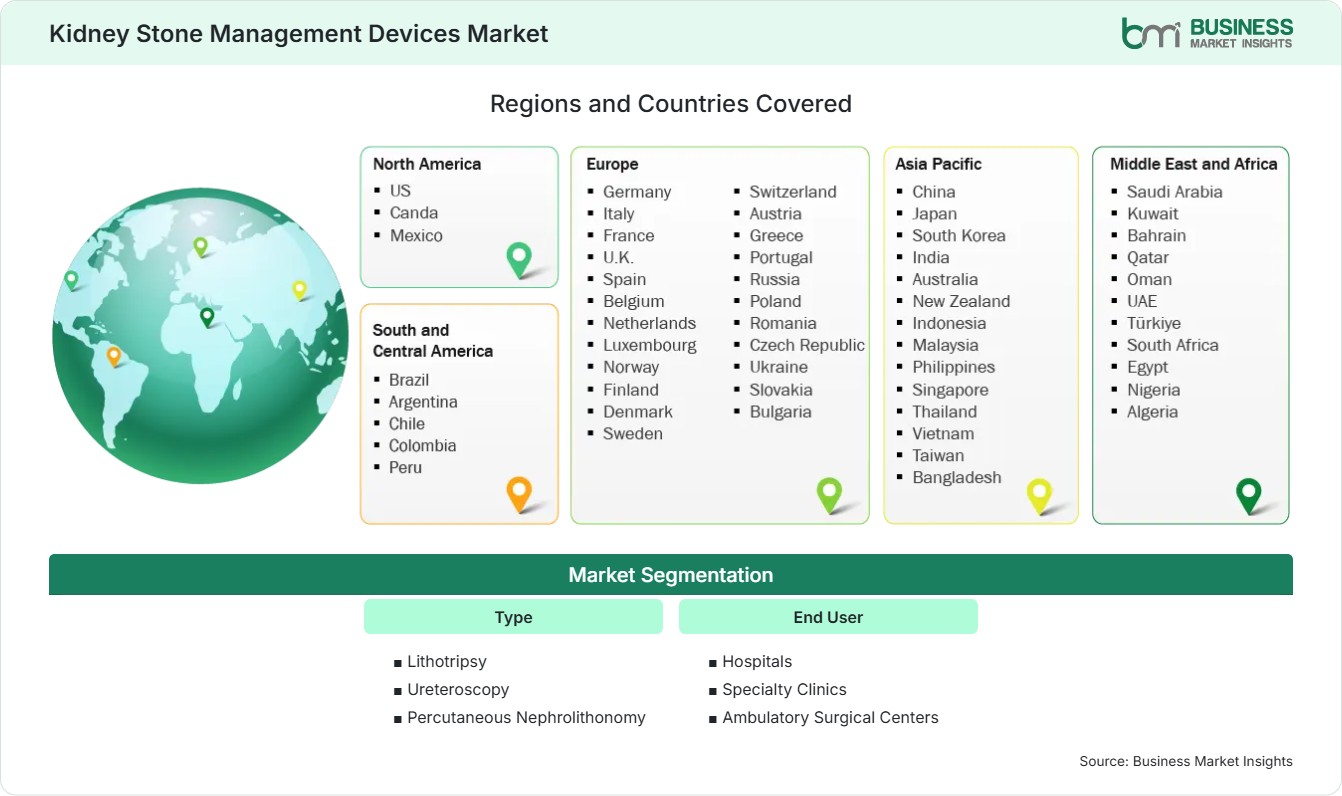
  • Type: Lithotripsy, Ureteroscopy, Percutaneous Nephrolithonomy
  • End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers
US$ 2.08 Bn Market size in 2025
US$ 3.59 Bn Market Size by 2033
7.06% CAGR, 2026 - 2033
2026-2033 Forecast Period

AI Overview

Kidney Stone Management Devices Market Summary

  • North America Region: North America holds a 32%–36% share in 2025 and is projected to grow at a 6.5%–7.2% CAGR through 2033, supported by established urology infrastructure, specialist availability, advanced endoscopy, minimally invasive treatment adoption, and expanding outpatient procedures. The U.S. remains the leading regional market, supported by sophisticated hospitals, specialty practices, advanced equipment adoption, and established treatment pathways.
  • Fastest Growing Region: Asia Pacific holds a 23%–27% share in 2025 and is projected to grow at a 8.1%–9.0% CAGR through 2033, driven by expanding healthcare infrastructure, rising treatment access, urbanization, specialist training, growing urology services, and increasing adoption of minimally invasive stone-management procedures.
  • Leading Segment: Ureteroscopy represents a 42%–46% share in 2025 and is projected to grow at a 7.2%–7.9% CAGR through 2033, supported by flexible endoscopy, improved visualization, laser fragmentation, broader anatomical access, and clinician preference for minimally invasive treatment.
  • High Growth Segment: Ambulatory Surgical Centers represent a 14%–18% Kidney Stone Management Devices Market share in 2025 and are projected to expand at a 8.0%–8.8% CAGR through 2033, supported by outpatient migration, shorter recovery requirements, streamlined workflows, lower facility utilization, and increasing procedural specialization.
  • Key Market Opportunity: Expansion of urological infrastructure, outpatient stone treatment, advanced lithotripsy, connected monitoring, and cost-efficient procedural technologies creates opportunities for manufacturers targeting hospitals, specialty clinics, and ambulatory facilities.
  • Major Market Players: Boston Scientific Corporation; Cook Medical; Olympus Corporation; Dornier MedTech GmbH; KARL STORZ SE & Co. KG; Richard Wolf GmbH; Coloplast A/S; Teleflex Incorporated; EDAP TMS S.A.; Quanta System S.p.A.
Strategic Insights

Kidney Stone Management Devices Market: Strategic Insights

Kidney Stone Management Devices Market Strategic Framework
FREE PDF
Request your free sample
Request free sample
Stakeholder View

Key Takeaways

  • Integrated suppliers can capture greater value by combining access, visualization, fragmentation, retrieval, and procedural support technologies.
  • Ureteroscopy and advanced lithotripsy offer strong upside as clinicians prioritize minimally invasive procedures and efficient stone clearance.
  • Product innovation is moving toward smaller instruments, improved visualization, precise energy control, flexible platforms, and easier procedural integration.
  • Asia Pacific offers an attractive expansion opportunity as hospitals and specialty centers increase advanced urological treatment capacity.
  • Outpatient migration is creating demand for efficient equipment designed for specialty clinics and ambulatory surgical centers.
  • Partnerships with hospitals, urologists, distributors, and healthcare networks can strengthen market access and accelerate technology adoption.
Geographic Outlook

Kidney Stone Management Devices Market Regional Highlights

North America Kidney Stone Management Devices Market

North America holds a 32%–36% share in 2025 and is projected to grow at a 6.5%–7.2% CAGR through 2033. The region benefits from established urology infrastructure, specialist availability, advanced endoscopy, and strong minimally invasive treatment adoption. The Kidney Stone Management Devices Market growth is supported by established urology infrastructure, specialist availability, advanced endoscopy, and strong minimally invasive treatment adoption.

  • The United States remains the principal regional demand center because of its extensive urology network, established minimally invasive treatment pathways, sophisticated hospitals, specialty practices, and broad availability of advanced procedural technologies.
  • Canada provides additional opportunities through hospital modernization, specialist urology services, expanding procedural capacity, and greater adoption of technologies designed to reduce hospitalization and improve treatment efficiency.
  • Hospitals increasingly evaluate systems according to procedural versatility, visualization quality, equipment reliability, maintenance requirements, physician familiarity, training requirements, and compatibility with existing operating-room infrastructure.
  • Ambulatory facilities are gaining relevance for suitable stone procedures as healthcare providers prioritize efficient workflows, patient convenience, shorter stays, and better utilization of specialized clinical resources.

US Kidney Stone Management Devices Market

The United States accounts for approximately 88%–92% of North American demand in 2025 and is projected to grow at a 6.6%–7.3% CAGR through 2033. Demand is supported by established urology practices, advanced hospital infrastructure, minimally invasive treatment adoption, and sophisticated lithotripsy capabilities. Outpatient migration and demand for precise visualization further support technology replacement and adoption across specialized treatment facilities.

  • U.S. hospitals continue upgrading flexible ureteroscopy, laser systems, access devices, imaging platforms, and retrieval technologies as physicians seek improved procedural precision and treatment flexibility.
  • Ambulatory surgical centers provide an expanding channel for suitable stone procedures because streamlined treatment pathways can improve patient convenience, operational efficiency, and resource utilization.
  • Competition increasingly involves physician training, clinical support, service contracts, equipment reliability, technology upgrades, and workflow integration rather than hardware specifications alone.

Europe Kidney Stone Management Devices Market

Europe holds a 25%–29% share in 2025 and is projected to expand at a 6.2%–7.0% CAGR through 2033. Germany, France, the United Kingdom, Italy, Spain, and Nordic markets represent important demand centers with established urological services. Growth is supported by minimally invasive treatment adoption, hospital modernization, endoscopic technology use, specialist expertise, and expanding outpatient capacity across public and private healthcare providers.

  • Germany supports strong demand through advanced hospitals, specialist urology centers, established endourological expertise, and adoption of sophisticated visualization, lithotripsy, and laser technologies.
  • France and the United Kingdom provide opportunities through mature healthcare networks, specialist treatment centers, hospital modernization, and increasing focus on efficient procedural pathways.
  • Italy and Spain contribute demand through specialist hospitals, private healthcare facilities, and wider adoption of minimally invasive treatment technologies for appropriate stone cases.
  • Nordic markets emphasize resource efficiency, patient-centered care, technology reliability, and streamlined workflows, supporting demand for compact and versatile urological equipment.

Asia Pacific Kidney Stone Management Devices Market

Asia Pacific holds a 23%–27% share in 2025 and is projected to grow at a 8.1%–9.0% CAGR through 2033. China, India, Japan, South Korea, and Australia represent major opportunities, while Southeast Asia offers additional potential. Growth is supported by healthcare infrastructure development, specialist training, increasing treatment access, urbanization, and rising adoption of minimally invasive urological procedures across public and private healthcare facilities.

  • China combines a large treatment population with expanding tertiary hospitals, growing urology specialization, healthcare investment, and increasing adoption of advanced procedural equipment.
  • India provides substantial potential as private hospitals, specialty centers, and ambulatory facilities expand advanced urological services across metropolitan and regional healthcare markets.
  • Japan and South Korea support premium technology demand through sophisticated hospitals, experienced specialists, advanced imaging capabilities, and established minimally invasive treatment practices.
  • Southeast Asian markets are developing specialist capacity and private healthcare infrastructure, creating opportunities for suppliers offering training, service support, flexible distribution, and cost-conscious equipment configurations.

Rest of World Kidney Stone Management Devices Market

Rest of World represents an estimated 13%–17% Kidney Stone Management Devices Market share in 2025 and is projected to grow at a 6.8%–7.7% CAGR through 2033. Latin America, the Middle East, and Africa present differentiated opportunities shaped by hospital expansion, specialist availability, and private healthcare development. Brazil, Mexico, Saudi Arabia, the UAE, and South Africa offer important entry points for international suppliers seeking regional expansion.

  • Brazil and Mexico provide opportunities through large healthcare systems, private hospital networks, specialist urology practices, and increasing adoption of minimally invasive procedural technologies.
  • Gulf markets are attractive for premium equipment suppliers because healthcare modernization programs emphasize advanced surgical capabilities, specialized services, and upgraded hospital infrastructure.
  • South Africa offers a regional opportunity through private healthcare infrastructure and specialist facilities serving patients from surrounding markets.
  • Emerging markets require adaptable pricing, distributor partnerships, physician training, and reliable service coverage because infrastructure, purchasing power, and specialist availability vary considerably.
Global Market Geography
FREE PDF
Request your free sample
Request free sample
Segment Analysis

Kidney Stone Management Devices Market Segmentation

Type

Ureteroscopy represents a 42%–46% share in 2025 and is projected to grow at a 7.2%–7.9% CAGR through 2033. The Kidney Stone Management Devices Market scope across device types reflects demand for minimally invasive visualization, fragmentation, retrieval, and access technologies. Adoption is supported by flexible endoscopy, improved procedural control, and broader use of minimally invasive stone treatment.

  • Lithotripsy: Lithotripsy systems fragment stones using externally or internally delivered energy, supporting minimally invasive treatment and enabling clinicians to select techniques according to stone characteristics.
  • Ureteroscopy: Ureteroscopy enables direct visualization and treatment of stones throughout the urinary tract, with flexible platforms supporting difficult anatomical locations and precise endoscopic intervention.
  • Percutaneous Nephrolithonomy (PCNL): PCNL supports treatment of larger or complex renal stones through percutaneous access, offering effective stone clearance when less invasive approaches may be unsuitable.

End User

Hospitals represent a 61%–65% share in 2025 and are projected to grow at a 6.5%–7.1% CAGR through 2033. Hospitals remain central because they manage complex cases and maintain multidisciplinary teams, imaging, anesthesia, operating-room infrastructure, and postoperative support. Specialty clinics and ambulatory facilities are expanding as suitable procedures shift toward efficient outpatient pathways.

  • Hospitals: Hospitals provide comprehensive infrastructure for complex stone cases, including operating rooms, anesthesia, imaging, emergency support, multidisciplinary specialists, and advanced procedural equipment.
  • Specialty Clinics: Specialty clinics provide focused urological care, dedicated expertise, shorter treatment pathways, and specialized workflows for selected stone procedures requiring efficient outpatient management.
  • Ambulatory Surgical Centers: Ambulatory centers support suitable procedures through streamlined workflows, shorter stays, specialized equipment, and efficient resource utilization, encouraging manufacturers to develop outpatient-oriented configurations.
Market Forces

Kidney Stone Management Devices Market Dynamics

Key Market Drivers

Rising Kidney Stone Incidence Drives Treatment Demand

The increased prevalence of stone leads to a high need for diagnostic and therapeutic urological services. There are dietary factors, physical activity, metabolic factors, dehydration, and demographic factors that could contribute to stone formation and recurrent episodes. Recurrent stones mean the constant need for efficient treatment devices. Thus, the Kidney Stone Management Devices Market trend remains related to the high need for urological services. Manufacturers have an advantage due to the high demand for minimally invasive procedures, visualization equipment, access devices, energy delivery platforms, and retrieval devices.

Growing Preference for Minimally Invasive Stone Management

The trend is increasingly towards procedures with low levels of surgical invasion, hospital stay, and post-treatment rehabilitation. Flexible ureteroscopy, laser lithotripsy, and improved access tools support this shift toward less invasive procedures. Improved visual technology and the flexibility of the instruments aid in improved control and precision during the procedure. Equipment is assessed by healthcare practitioners based on its visual clarity, ergonomic features, reliability, versatility, and workflow capabilities. The trend pushes users to upgrade their existing technology and drives demand for new technology.

Increasing Healthcare Investments Support Advanced Treatment Devices

Investments in health care are growing the capability to provide treatments in hospitals, specialized treatment centers, and ambulatory care facilities. The construction of operating theaters, the installation of imaging technology, specialist training, and the development of private health care increase the likelihood that urological technology will be installed. Investments are especially important in developing countries, where there are few opportunities for specialized treatments. There is an increasing need for systems that allow multiple procedures to be performed with acceptable maintenance costs.

Key Market Opportunities

Expanding Urological Care Infrastructure Across Emerging Markets

Emerging market potential lies in increased capacity in hospitals and specialist centers for urological services. New hospital facilities would be able to equip themselves with state-of-the-art endoscopy, lithotripsy, imaging, and surgery units without many past obligations. The manufacturers could use regional distribution channels, physician education programs, maintenance services, and flexible design for improved market access. Growth would be appealing where there is an overlap among patient needs, modernization of health care systems, and private-sector investments. Economical systems with high clinical performance features can enhance market competitiveness when capital is limited in hospitals.

Growing Demand for Home Based Stone Monitoring Solutions

Digital health technologies enable remote surveillance of patients beyond office visits and after stone management interventions. In-home technologies may help in hydration tracking, symptom recording, medication adherence, recovery tracking, and communication with medical professionals. Connected technologies may ensure greater continuity among diagnosis, intervention, and follow-up, but they do not replace procedural treatment. The Kidney Stone Management Devices Market forecast is positive for technologies that will link patient data with the urologist workflow. These technologies may increase accessibility for patients located far from specialized centers.

Increasing Adoption of Advanced Lithotripsy Technologies

Opportunities from advanced lithotripsy stem from improvements in energy delivery, stone-fragmentation control, imaging, and process efficiency. Healthcare professionals are increasingly focused on evaluating systems for clinical flexibility, precision, ease of integration into the workflow, maintenance, and compatibility with other equipment used in the institution. Vendors can exploit this by offering equipment updates, replacement programs, servicing, and physician training. This is a business opportunity not only for hospitals and other large institutions but for specialized centers that perform such procedures in an outpatient setting.

Market Restraints and Challenges

High Treatment Device Costs Limit Healthcare Adoption

Factor: Modern lithotripter devices, flexible endoscopes, visualization systems, laser systems, and associated tools have high initial and ongoing costs. Impact: The cost of purchasing, maintaining, operating, and training on these devices can slow their adoption in smaller hospitals and poorly funded healthcare organizations. The greater the lack of reimbursement or the volume of procedures required to use these devices, the greater the impact of high costs. Vendors are encouraged to offer a range of purchase schemes, service agreements, reconditioned tools, modular systems, and financing programs. Technology buyers also evaluate other medical needs, slowing down the process of replacing old devices.

Limited Access to Specialized Urological Care Facilities

Factor: Complex procedures in stone treatment require expertise from urologists, anesthesiologists, imaging facilities, specialized equipment, and facilities capable of managing complications. Impact: The lack of such resources limits implementation despite high patient demand, especially in rural areas. Urban concentration of specialists may lead to long distances for patients who need complex care. This limitation can be addressed by manufacturers through physician education, referral systems, telemedicine services, mobile services, and simplified equipment setup. The long-term solution lies in the development of healthcare facilities, the recruitment of more specialists, equipment financing, and procedural facilities.

Company Analysis

Competitive Landscape

The competitive environment includes diversified medical-device manufacturers, specialized urology technology providers, endoscopy companies, laser-system developers, and businesses focused on procedural access and supporting equipment. Kidney Stone Management Devices Market analysis indicates that competition increasingly centers on procedural precision, visualization, equipment reliability, physician familiarity, service support, and workflow integration.

Company Name

Overview

Products and Services relevant to this market

Boston Scientific Corporation

Global medical-device company with a broad urology portfolio serving hospitals and specialist providers.

Lithotripsy systems, ureteroscopes, retrieval devices, access products, guidewires, stents, and stone-management accessories.

Cook Medical

Medical-device manufacturer with established urology products supporting minimally invasive stone procedures.

Ureteral access products, guidewires, stone retrieval devices, stents, dilation systems, and endourological accessories.

Olympus Corporation

Global medical-technology company with extensive endoscopy capabilities and urological visualization systems.

Flexible and rigid ureteroscopes, visualization platforms, endoscopic accessories, treatment instruments, and urology technologies.

Dornier MedTech GmbH

Specialized medical-technology provider focused on urology and stone-management technologies.

Lithotripsy systems, laser technologies, treatment platforms, urological equipment, accessories, and procedural support.

KARL STORZ SE & Co. KG

Endoscopy specialist providing visualization and minimally invasive surgical technologies.

Ureteroscopes, endoscopic imaging, visualization systems, instruments, access tools, and urological procedure platforms.

Richard Wolf GmbH

German medical-technology company focused on endoscopy and minimally invasive surgical equipment.

Ureteroscopy systems, endoscopic instruments, visualization technologies, lithotripsy accessories, and urological equipment.

Coloplast A/S

Healthcare company providing products for urology and specialized urinary care.

Urological catheters, drainage products, stone-management accessories, and urinary tract care products.

Teleflex Incorporated

Global medical-device company serving hospitals through specialty interventional and surgical portfolios.

Urological access devices, guidewires, catheters, retrieval products, stents, and procedural accessories.

EDAP TMS S.A.

Urology-focused medical-technology company specializing in stone treatment and minimally invasive procedures.

Extracorporeal shock wave lithotripsy systems, urological treatment platforms, and procedural technologies.

Quanta System S.p.A.

Medical laser technology company developing systems for urology and surgical specialties.

Holmium laser systems, stone fragmentation technologies, surgical lasers, accessories, and urological support.

Trust & Transparency

Research Methodology

The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst review.

View Full Research Methodology

Questions Answered

Frequently Asked Questions

What does the Kidney Stone Management Devices Market report indicate about future competition?

Competition is likely to emphasize procedural efficiency, visualization, lithotripsy precision, instrument flexibility, service support, physician training, and technology integration. Companies offering comprehensive urology portfolios and reliable lifecycle support should be positioned to strengthen relationships with hospitals, specialty clinics, and ambulatory providers.

Why are ambulatory surgical centers creating new opportunities for device manufacturers?

Ambulatory centers can perform appropriate stone procedures through streamlined workflows and shorter stays. Their expansion creates demand for compact, efficient, reliable systems that can support procedural throughput while minimizing equipment complexity, maintenance requirements, and unnecessary hospital resource utilization.

How are advanced visualization technologies influencing stone-management device adoption?

Improved visualization helps clinicians identify stones, navigate complex anatomy, position instruments, and monitor fragmentation during procedures. Better imaging and flexible endoscopic capabilities can improve procedural confidence and support minimally invasive treatment, encouraging healthcare providers to upgrade older visualization and endoscopy platforms.

Which applications present the strongest opportunity in the market?

Ureteroscopy, lithotripsy, and PCNL provide strong opportunities because they address different stone sizes, locations, and clinical complexities. Outpatient ureteroscopy and advanced lithotripsy can be particularly attractive where providers prioritize efficient treatment pathways, shorter recovery, and broader procedural capacity.

What factors are improving Kidney Stone Management Devices Market return on investment?

Growing procedure volumes, minimally invasive treatment preferences, outpatient migration, technology upgrades, and expanding specialist infrastructure can improve equipment utilization and investment returns. Suppliers can strengthen returns through service contracts, consumable sales, training programs, equipment upgrades, and platforms capable of supporting multiple urological procedures.

Access the Full Kidney Stone Management Devices Market Report

Get segment-level forecasts, regional estimates, competitive benchmarking, company profiles and downloadable Excel datasets.

Access the full Kidney Stone Management Devices Market Report
350 pages PDF & Excel | 2026-08-20
Similar Research

Related Market Reports