
Automotive Wraps Films Market Outlook: Size, Share, Trends, Growth Analysis, Competitive Landscape & Forecast, 2026-2033

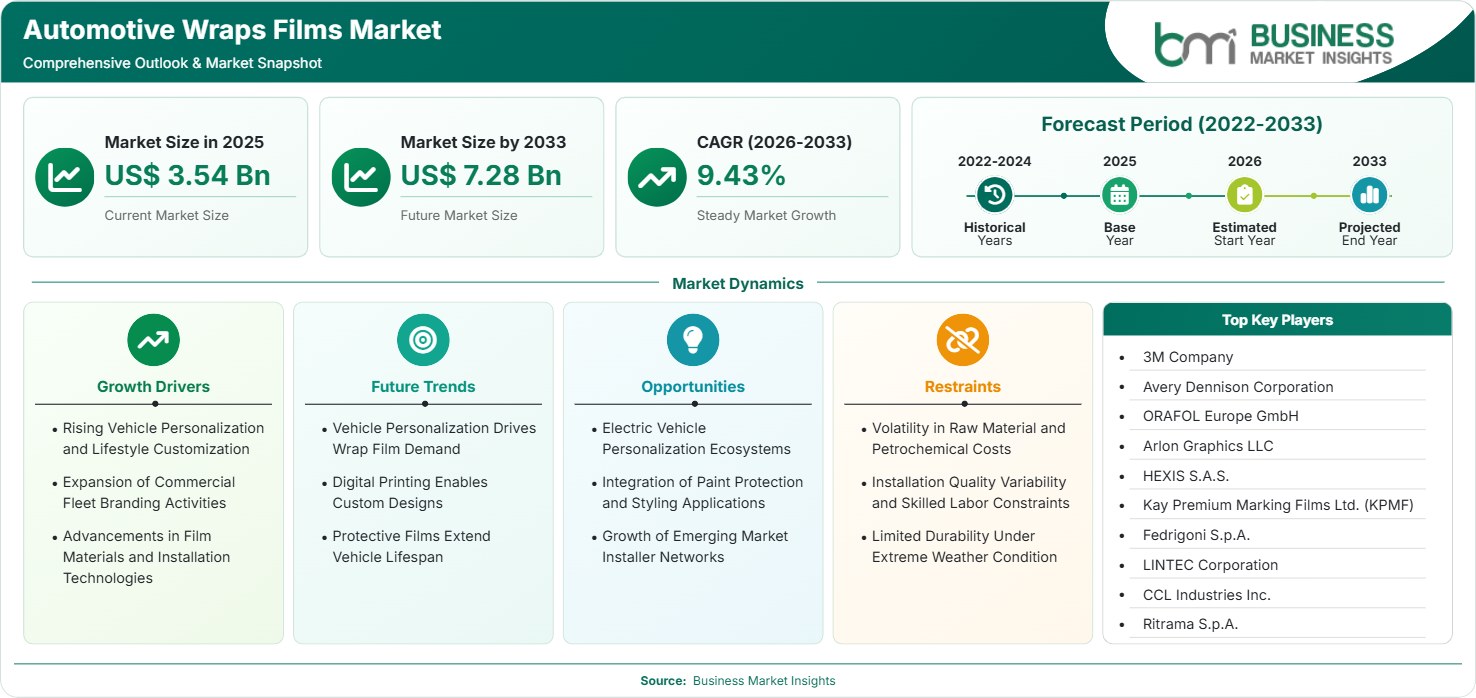
The Automotive Wraps Films Market size was valued at US$ 3.54 Billion in 2025 and is projected to reach US$ 7.28 Billion by 2033, growing at a CAGR of 9.43% during 2026–2033. Rising vehicle personalization, expanding fleet branding, durable vinyl innovations, and increasing aftermarket customization are accelerating adoption, while commercial advertising applications and premium finish technologies create substantial long-term opportunities.

Report Coverage
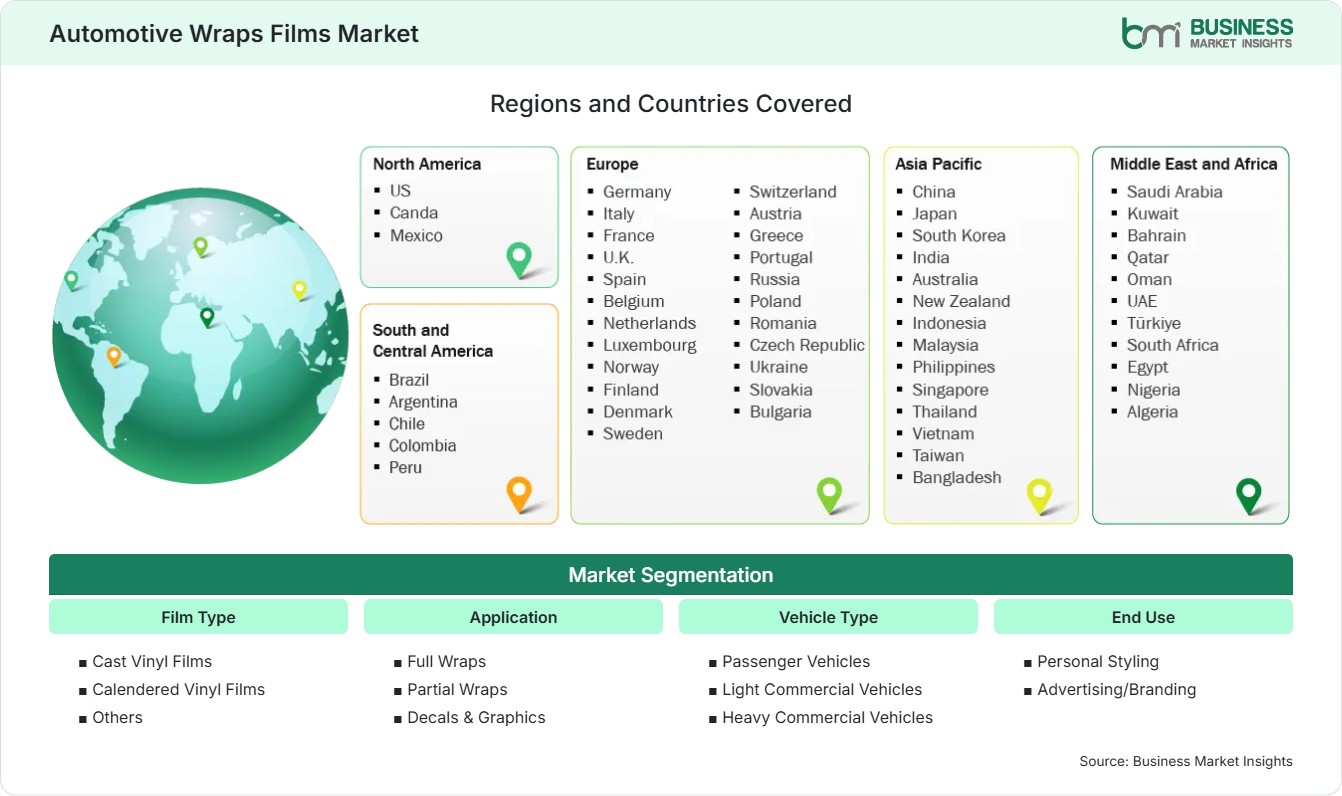
  • Film Type: Cast Vinyl Films, Calendered Vinyl Films, Others
  • Application: Full Wraps, Partial Wraps, Decals & Graphics
  • Vehicle Type: Passenger Vehicles, Light Commercial Vehicles, Heavy Commercial Vehicles
  • End Use: Personal Styling, Advertising/Branding
US$ 3.54 Bn Market size in 2025
US$ 7.28 Bn Market Size by 2033
9.43% CAGR, 2026 - 2033
2026-2033 Forecast Period

AI Overview

Automotive Wraps Films Market Summary

  • North America Region: North America holds an Automotive Wraps Films Market share of 34%–37% in 2025, growing at a CAGR of 8.5%–9.0% during 2026–2033. Strong vehicle customization culture, mature aftermarket networks, fleet advertising demand, and premium vinyl adoption support expansion. Growing investments in paint protection integration and installer certification programs create opportunities. US market maintains steady demand across commercial fleets and enthusiasts, advancing at an estimated 8.7%–9.2% CAGR through 2033.
  • Fastest Growing Region: Asia Pacific holds a market share of 27%–30% in 2025, growing at a CAGR of 10.8%–11.5% during 2026–2033. Rising automotive ownership, expanding detailing centers, e-commerce marketing fleets, urban mobility services, and increasing consumer spending on aesthetics support strong growth opportunities across major developing economies.
  • Leading Segment: Cast Vinyl Films account for a 54%–58% share in 2025 and are projected to grow at a 9.6%–10.2% CAGR. Superior conformability, durability, color retention, and suitability for premium wrapping applications continue supporting demand from luxury vehicles, fleet graphics, and complex surface installations.
  • High Growth Segment: Full Wraps represent 42%–46% share of the Automotive Wraps Films Market in 2025 with an anticipated 10.4%–11.0% CAGR. Increasing preference for complete vehicle transformations, corporate branding visibility, removable customization options, and cost advantages versus repainting continue strengthening segment momentum globally.
  • Key Market Opportunity: Demand for electric vehicle personalization, digitally printed graphics, and paint-protection-integrated wrapping solutions creates high-value opportunities as consumers seek aesthetics, protection, branding flexibility, and resale value enhancement simultaneously.
  • Major Market Players: 3M Company, Avery Dennison Corporation, ORAFOL Europe GmbH, Arlon Graphics LLC, HEXIS S.A.S., Kay Premium Marking Films Ltd. (KPMF), Fedrigoni S.p.A., LINTEC Corporation, CCL Industries Inc., and Ritrama S.p.A.
Strategic Insights

Automotive Wraps Films Market: Strategic Insights

Automotive Wraps Films Market Strategic Framework
FREE PDF
Request your free sample
Request free sample
Stakeholder View

Key Takeaways

  • The value chain is becoming increasingly integrated, with raw material suppliers, converters, distributors, certified installers, and vehicle-detailing networks collaborating to improve service quality and reduce installation failures.
  • Commercial fleet branding and electric vehicle personalization present the strongest medium-term revenue opportunities due to rising marketing visibility requirements and growing consumer demand for distinctive vehicle appearances.
  • Product innovation is shifting toward self-healing surfaces, improved air-egress technologies, low-VOC adhesives, and hybrid protection films combining appearance enhancement with paint preservation.
  • Asia Pacific offers a compelling investment environment because of rapid vehicle ownership growth, expanding detailing infrastructure, and increasing consumer spending on vehicle aesthetics.
  • Strategic partnerships, distributor expansion, certification programs, and aftermarket channel acquisitions are becoming prevalent as suppliers strengthen geographic reach and installation quality standards.
  • Growth in ride-hailing, logistics delivery fleets, and mobile advertising applications is creating recurring replacement demand that supports long-term revenue visibility for manufacturers.
Geographic Outlook

Automotive Wraps Films Market Regional Highlights

North America Automotive Wraps Films Market

North America accounted for approximately 34%–37% of the Automotive Wraps Films Market share in 2025 and is projected to expand at a CAGR of 8.5%–9.0% through 2033. Strong aftermarket customization culture, established installer networks, and extensive commercial fleet operations support demand. Premium vehicle ownership and increasing interest in paint-preserving alternatives to repainting continue enhancing adoption. The region benefits from mature advertising ecosystems where vehicle graphics provide cost-effective marketing exposure. Fleet operators increasingly deploy wraps to maintain brand visibility while preserving vehicle resale value.

  • Fleet advertising across logistics, food delivery, and service industries continues generating high replacement demand for durable vinyl solutions.
  • Installer certification programs and professional detailing networks improve installation quality, increasing consumer confidence and repeat business.
  • Commercial enterprises increasingly use removable vehicle graphics to support short-cycle marketing campaigns without permanent vehicle modifications.
  • Demand for matte, satin, metallic, and textured finishes is expanding as personalization preferences diversify across vehicle owners.

US Automotive Wraps Films Market

The United States represents approximately 78%–82% of regional demand and is anticipated to grow at a CAGR of 8.7%–9.2% through 2033. High specialty vehicle ownership, strong motorsports influence, and widespread acceptance of aftermarket customization drive adoption. Corporate fleet branding remains a significant revenue source. Growth in electric vehicle ownership is encouraging demand for distinctive aesthetics and paint protection, while a mature installer ecosystem supports both premium and mass-market applications.

  • Large logistics fleets increasingly integrate wraps into branding and asset management strategies.
  • Strong dealership relationships help promote personalization packages at vehicle purchase.
  • Premium vinyl products benefit from substantial enthusiast communities and automotive event participation.
  • EV owners increasingly seek customization without affecting original paint integrity.

Europe Automotive Wraps Films Market

Europe held approximately 28%–31% share in 2025 and is expected to grow at a CAGR of 8.8%–9.4%. Environmental awareness and preference for reversible vehicle modifications support adoption across passenger and commercial fleets. Germany leads regional consumption, while Poland and Spain are among faster-growing markets with CAGRs estimated above regional averages. Vehicle leasing prevalence further encourages removable branding and styling solutions. Regulatory interest in sustainable materials is encouraging innovation in recyclable and lower-emission film technologies.

  • Germany remains the leading market due to strong automotive culture and premium vehicle penetration.
  • Poland benefits from expanding graphics-installation capacity and growing commercial vehicle branding demand.
  • Wrap adoption among leased vehicles increases because films preserve exterior finish quality.
  • Sustainability-focused product development is influencing supplier investment priorities.
  • Commercial fleet modernization continues supporting regional volume growth.

Asia Pacific Automotive Wraps Films Market

Asia Pacific accounted for a 27%–30% share in 2025 and is expected to register the fastest expansion at a CAGR of 10.8%–11.5% during the Automotive Wraps Films Market forecast period. China remains the largest regional market, while India demonstrates some of the strongest growth momentum. Rising disposable incomes, expanding vehicle parc, accelerating urbanization, and increasing visibility of customization trends support demand. Investments in automotive services, detailing studios, and e-commerce delivery fleets are creating sustained requirements for branding and protective film solutions.

  • China leads regional revenues through extensive automotive ownership and aftermarket development.
  • India records strong momentum due to increasing vehicle personalization among younger consumers.
  • Growth of ride-hailing and delivery services supports recurring demand for fleet graphics.
  • Regional manufacturing investments improve product accessibility and pricing competitiveness.
  • Social media influence accelerates consumer awareness of advanced styling solutions.

Rest of World Automotive Wraps Films Market

Rest of World represented approximately 8%–10% share in 2025 and is projected to expand at a CAGR of 9.3%–10.0% through 2033. South & Central America benefit from growing advertising applications and commercial vehicle branding, with Brazil leading regional demand. In the Middle East and Africa, the UAE and Saudi Arabia show notable momentum driven by luxury vehicle customization and expanding automotive aftermarket services. Urban business promotion activities and developing automotive ecosystems continue creating incremental opportunities.

  • Brazil remains the leading Latin American market supported by commercial transportation activity.
  • UAE demand is strengthened by luxury vehicle ownership and premium styling preferences.
  • Saudi Arabia benefits from expanding automotive retail and customization infrastructure.
  • Vehicle graphics are increasingly adopted by small businesses seeking local advertising visibility.
  • Distribution network expansion improves product reach across previously underserved markets.
Global Market Geography
FREE PDF
Request your free sample
Request free sample
Segment Analysis

Automotive Wraps Films Market Segmentation

Film Type

Film Type accounted for a large share of the industry, with Cast Vinyl Films being the largest type. The Film Type category accounted for about 54%-58% of the market in 2025 and is expected to grow at a CAGR of 9.6%-10.2%. The market scope of Automotive Wraps Films is increasingly widening owing to the preference for durability, flexibility, and high visual quality.

  • Cast Vinyl Films: Preferred for complex vehicle contours due to superior conformability, durability, color consistency, and reduced shrinkage, making them ideal for premium customization and commercial branding projects.
  • Calendered Vinyl Films: Offer cost-effective solutions for short-to-medium duration graphics applications where affordability and broad color availability remain important purchasing considerations.

Application

Application Dynamics are affected by rising needs for brand visibility and personalization. The category that dominates is Full Wraps, representing a market share of around 42%–46% in 2025 and forecasted to have a CAGR of 10.4%–11.0%. The trends in the Automotive Wraps Films Market are shifting towards full transformation, providing maximum visual effect and protection.

  • Full Wraps: Deliver comprehensive vehicle coverage, enhanced customization flexibility, strong branding visibility, and superior aesthetic transformation for personal and commercial applications.
  • Partial Wraps: Enable targeted customization while reducing installation costs, making them attractive for businesses and cost-conscious vehicle owners.
  • Decals & Graphics: Widely adopted for promotional branding, fleet identification, and decorative personalization, requiring lower material consumption and quicker installation.

Vehicle Type

Vehicle Type Segmentation is widely favored for its broad applicability in transportation. Passenger Cars retain their market leadership position, capturing 60%-64% market share in 2025 and growing at a CAGR of 9.5%-10.1%. Ownership of premium and electric cars increases personalized demands among consumers.

  • Passenger Vehicles: Strong consumer interest in appearance enhancement and vehicle protection supports widespread aftermarket adoption globally.
  • Light Commercial Vehicles: Branding requirements among logistics, delivery, and service fleets continue driving demand for professionally installed graphics solutions.
  • Heavy Commercial Vehicles: Long-distance visibility and corporate identity requirements support adoption across transportation and industrial sectors.

End Use

The end-use demand is driven by increased preference for personalization and business communication requirements. Personal Styling captured around a 55%-59% market share in 2025 and is expected to register a CAGR of 9.8%-10.4%. Social media influence and awareness of aftermarket customization will continue to drive category growth.

  • Personal Styling: Consumers increasingly seek unique visual finishes, color transformations, and protective enhancements without committing to permanent repainting.
  • Advertising/Branding: Businesses leverage mobile advertising exposure through vehicle graphics to improve brand visibility and marketing efficiency across local and regional markets.
Market Forces

Automotive Wraps Films Market Dynamics

Key Market Drivers

Rising Vehicle Personalization and Lifestyle Customization

Increased consumer spending on car beauty is another key driver in terms of demand. Today’s car owners are more inclined towards seeing vehicles as lifestyle products rather than mere modes of transportation. All automobile aftermarket industry associations worldwide are reporting steady growth in spending on vehicle customization, especially exterior customization. Automotive Wraps Films market growth can benefit from the availability of a high-end visual finish at a much lower cost than professional painting. The range of demand includes matte, gloss, satin, chrome, and specialized finishes. The elements of social media content, automotive events, influencer marketing, and enthusiast communities help build awareness. The above elements all work together to enable consistent replacement cycles and installer usage.

Expansion of Commercial Fleet Branding Activities

Commercial graphics provide a constant stream of advertisements at fairly minimal overall cost. Increasingly, logistics, delivery, utilities, contractors, and ride-sharing companies are employing graphic branding. With the growth of delivery fleets in cities worldwide, the visibility of mobile advertising is increasing. Moreover, there has been increased focus on the removability of graphics to ensure flexibility of the assets in the event of a transfer of ownership. In terms of Automotive Wraps Films Market Trends, demand for digital printing films to customize advertisements will rise. Benefits such as durability, weather resistance, and better color retention can be achieved by using the films commercially. These dynamics strengthen long-term demand across both developed and emerging economies, where fleet utilization rates continue increasing.

Advancements in Film Materials and Installation Technologies

Manufacturing companies have advanced polymer science, air-release channels, pressure-sensitive adhesives, and UV-resistant coatings. The next generation of films will make installation easier and ensure the product is durable, adding value for the end-user. There are also technological advancements that make the products compatible with complicated car designs. There are self-healing films, enhanced laminates, and paint-protection capabilities of films, which are proving popular among luxury users. Certification can help installers take advantage of advanced products, leading to greater satisfaction and lower costs. Innovation-led product differentiation remains an important competitive strategy as suppliers seek higher-value applications across the luxury, commercial, and electric-vehicle segments.

Key Market Opportunities

Electric Vehicle Personalization Ecosystems

The growing number of electric vehicle owners offers significant business potential. EV customers tend to show strong interest in fashionable looks, sustainability, and technological personalization. The film enables distinctive branding and look customization without damaging the OEM coating. With increasing production volumes of electric vehicles worldwide, stylists and body shops are becoming more inclined to offer styling packages alongside cars. The Automotive Wraps Films Market Forecasts indicate an increasing demand for high-quality coatings that meet EV customers' needs. In addition, when combined with paint protection technologies, it increases the value proposition. Suppliers capable of developing EV-specific products, installer networks, and dealership partnerships are well-positioned to capture incremental revenue over the forecast period.

Integration of Paint Protection and Styling Applications

The merging of color-change films with protection solutions is giving rise to a whole new range of products. Consumers now look for something that not only meets their aesthetic needs but also protects against scratches, cracks, and weathering. These hybrid products have better margins and cater specifically to owners of luxury vehicles. Performance-based differentiation helps companies leverage better pricing power. Investment in high-end film technologies is growing in line with customer demand for multifunctional products. This convergence expands addressable markets by appealing simultaneously to styling enthusiasts and protection-focused consumers seeking enhanced ownership experiences.

Growth of Emerging Market Installer Networks

Even with the growth in the automotive population, many emerging countries still have limited penetration. Training, certification, and distribution can go a long way to ensure that more markets are covered. The increasing urbanization, coupled with rising disposable incomes, is creating greater demand for aftermarket automotive services. Fleet upgrades in Asia, the Middle East, and Latin America are also encouraging adoption. Partnerships in the region will help bridge skills gaps while ensuring quality installations and customer satisfaction. Early brand presence in the market may yield a sustainable competitive advantage as industry adoption accelerates.

Market Restraints and Challenges

Volatility in Raw Material and Petrochemical Costs

Factor: Vinyl resins, special adhesives, and coating compounds remain closely linked to petrochemical logistics chains. Impact: Volatility in input prices generates cost pressure on manufacturers and distributors. Price uncertainty in materials can lead to margin instability and make it more difficult for companies to plan procurement. Small converters may be at greater risk due to their inability to achieve economies of scale when purchasing raw materials. Transporting costs and energy prices impact manufacturing logistics. In tough market conditions, suppliers find it difficult to fully transfer costs to the end user.

Installation Quality Variability and Skilled Labor Constraints

Factor: The successful installation depends heavily on the installer's skills and environmental conditions during installation. Impact: This could lead to inconsistent quality, which may manifest as lifting, bubbles, discoloration, or premature replacement. Many emerging markets face difficulties finding qualified installers capable of working with top-grade materials. Increased training costs become operational costs for the distributors and service providers. This could mean less repeat business and slow down market acceptance. While manufacturers continue to expand certification initiatives, workforce development remains a critical challenge affecting adoption rates and the consistency of long-term service quality.

Company Analysis

Competitive Landscape

Automotive Wraps Films Market analysis indicates competition is driven by material innovation, distribution reach, installer training programs, and premium product differentiation.

Company Name

Overview

Products and Services relevant to this market

3M Company

Global materials science leader serving automotive aftermarket and graphics industries worldwide.

Vehicle wrap films, graphic films, laminates, adhesive technologies, automotive customization solutions.

Avery Dennison Corporation

Major graphics solutions provider with extensive wrapping film portfolio and installer ecosystem.

Supreme Wrapping Film, digital wrap films, paint protection films, certification services.

ORAFOL Europe GmbH

European specialist in graphic media and wrapping solutions with global reach.

ORACAL wrapping films, ORAGUARD protection films, fleet graphics materials.

Arlon Graphics LLC

Focused manufacturer of premium graphic and vehicle wrapping products.

Cast wrap films, printable media, overlaminates, fleet branding solutions.

HEXIS S.A.S.

French producer known for innovative self-adhesive film technologies.

Color change wraps, digital printing films, protective coatings, specialty finishes.

Kay Premium Marking Films Ltd. (KPMF)

Niche premium manufacturer serving customization and branding applications.

Premium wrapping films, metallic finishes, specialty color solutions.

Fedrigoni S.p.A.

Global labeling and specialty materials company with graphic media operations.

Self-adhesive graphics, wrapping media, decorative film applications.

LINTEC Corporation

Japanese materials technology company with imaging and adhesive expertise.

Adhesive films, graphic media, automotive surface solutions.

CCL Industries Inc.

International specialty packaging and labeling group with graphics capabilities.

Printable films, branding materials, pressure-sensitive media solutions.

Ritrama S.p.A.

Established self-adhesive materials supplier serving graphics and automotive sectors.

Vehicle graphics films, advertising media, specialty adhesive products.

Trust & Transparency

Research Methodology

The market analysis combines proprietary research with secondary data from government agencies, company disclosures, regulatory filings, industry databases and expert interviews. Market estimates are validated through data triangulation, cross-market benchmarking and analyst review.

View Full Research Methodology

Questions Answered

Frequently Asked Questions

What insights does the Automotive Wraps Films Market Report provide?

The Market Report evaluates regional demand patterns, segment performance, competitive strategies, technology developments, investment opportunities, and forecast outlook through 2033.

What are the main customer groups purchasing wrap films?

Key buyers include personal vehicle owners, logistics operators, ride-hailing fleets, automotive dealerships, advertising agencies, and commercial fleet managers seeking branding visibility.

How are electric vehicles influencing demand?

Electric vehicle owners frequently seek distinctive aesthetics and protective solutions, encouraging adoption of color-change wraps, premium finishes, and integrated protection technologies.

What is the most commonly used film type in the industry?

Cast vinyl films dominate because they provide excellent conformability, durability, and finish quality for complex vehicle surfaces and premium customization projects.

What factors are accelerating adoption of vehicle wrapping solutions?

Demand is being supported by vehicle personalization, fleet advertising, paint protection needs, removable customization options, and improved film durability that makes wraps a practical alternative to repainting.

Access the Full Automotive Wraps Films Market Report

Get segment-level forecasts, regional estimates, competitive benchmarking, company profiles and downloadable Excel datasets.

Access the full Automotive Wraps Films Market Report
350 pages PDF & Excel | 2026-09-22
Similar Research

Related Market Reports