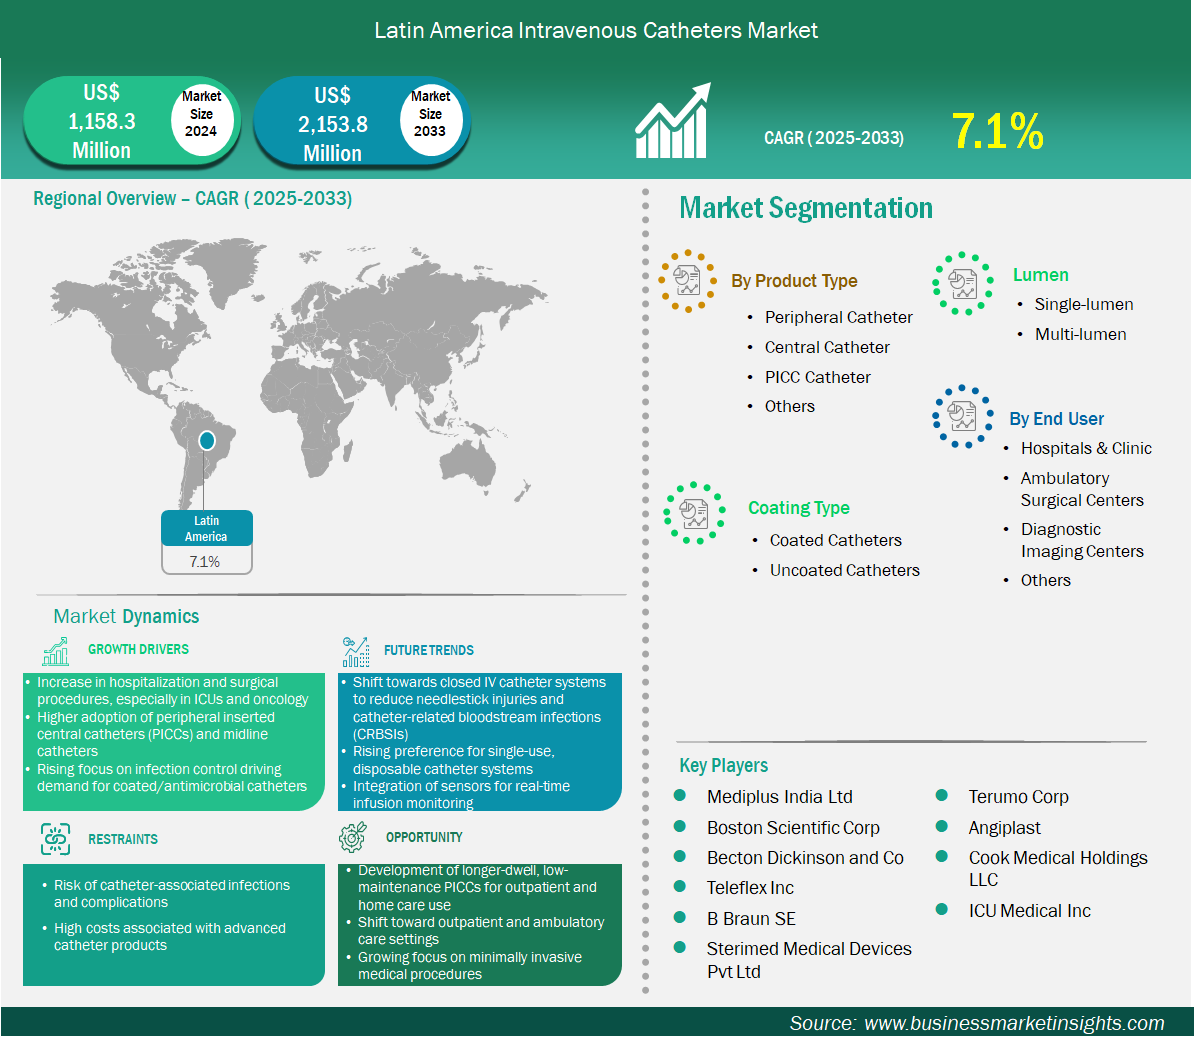
The Latin America intravenous catheters market size is expected to reach US$ 2,153.8 million by 2033 from US$ 1,158.3 million in 2024. The market is estimated to record a CAGR of 7.1% from 2025 to 2033.
Executive Summary and Latin America Intravenous Catheters Market Analysis:
The intravenous catheters market in Latin America is experiencing significant growth driven by the increase in hospitalization and surgical procedures; especially in ICUs and oncology, higher adoption of peripherally inserted central catheters (PICCs) and midline catheters, and rising focus on infection control driving demand for coated/antimicrobial catheters. Latin America’s intravenous catheter market spans sophisticated urban hospitals and resource-pressured regional facilities, creating layered demand profiles. Peripheral catheters underpin routine admissions, ED volumes, and surgical recovery, with nurse-led protocols guiding gauge selection and securement to minimize failure. Coated catheters are progressively adopted in tertiary institutions in Brazil, Mexico, Chile, and Colombia, where infection dashboards and accreditation cycles prioritize CRBSI reduction and phlebitis control; hydrophilic and antimicrobial coatings gain favour for extended dwell and fragile veins. Multi-lumen devices serve concentrated oncology hubs and high-acuity ICUs, enabling parallel infusions of chemo, antibiotics, nutrition, and vasoactive agents while reducing line changes. Hospitals and clinics dominate consumption, supported by public investments and private operator growth in metropolitan corridors; outpatient infusion suites add volume in payer-managed networks seeking reduced inpatient days. Distribution is hybrid: multinational manufacturers compete with agile regional firms that excel in consignment, reimbursement navigation, and clinician education. Procurement committees evaluate lifecycle cost, complication rates, and training packages, awarding advantage to vendors that demonstrate durable dwell, low infiltration, and robust securement. Variability in funding and logistics drives portfolio tiering—baseline peripheral lines for high-throughput wards, coated ranges for tertiary centers, and multi-lumen SKUs for complex care anchors. Country heterogeneity—currency dynamics, regulatory timelines, and public health priorities—demands tailored engagement. Overall, Latin America rewards pragmatic, clinically validated designs supported by reliable supply, training fidelity, and post-sales service that stabilizes outcomes in variable environments.
Latin America Intravenous Catheters Market Segmentation Analysis:
Key segments that contributed to the derivation of the intravenous catheters market analysis are product, coating type, lumen, and end user.
- By product, the intravenous catheters market is segmented into peripheral catheter, central catheter, PICC catheter, and others. Peripheral catheter dominated the market in 2024, driven by the emergency caseloads and standardized perioperative fluid protocols.
- By coating type, the intravenous catheters market is segmented into coated catheters, uncoated catheters. Coated catheters dominated the market in 2024, driven by tertiary hospital infection benchmarks and outcome-linked procurement.
- By lumen, the market is segmented into single-lumen, multi-lumen. Multi-lumen dominated the market in 2024, driven by the complex chemo and critical care pathways in urban centers.
- By end user, the market is segmented into hospitals & clinics, ambulatory surgical centers, diagnostic imaging centers, and others. Hospitals & clinics dominated the market in 2024, driven by public-private network expansion and payer-backed outpatient infusions.
Latin America Intravenous Catheters Market Outlook
The Latin America intravenous catheters market is segmented into Mexico, Brazil, Argentina, Peru, Chile, and Colombia. Forward momentum will derive from oncology program expansion, outpatient infusion growth, and infection control commitments. Peripheral catheter demand remains resilient as health systems pursue shorter stays and faster turnover; vein-friendly materials, atraumatic tips, and securement innovations will reduce failure and reinsertion burden. Coated catheters are set to accelerate under hospital quality incentives and payer recognition of infection-related costs, favouring outcome-linked contracts and vendor-supported audits. Multi-lumen adoption will rise with intensifying chemo protocols and ICU modernization; portfolios offering clear lumen segregation, simplified maintenance, and standardized accessories will capture share. Supply-chain robustness is a competitive differentiator—regional warehousing, dual-source strategies, and transparent replenishment SLAs will influence tenders amid transport and currency volatility. Workforce pressures push devices that streamline insertion and maintenance; vendor training and simulation programs will be weighed alongside price as committees target complication reductions. Sustainability considerations—packaging waste and recyclability—are entering larger system tenders, creating opportunities for eco-optimized lines that maintain sterility standards. Digital documentation and barcode tracking are expanding, enabling traceability and integrating adverse event data into procurement evaluations. Success necessitates balancing affordability with measurable clinical gains, localized service presence, and reimbursement fluency. Expect steady growth driven by complex therapy intensity, outpatient pathways, and quality mandates that elevate coated and multi-lumen segments while sustaining peripheral mainstays.
Latin America Intravenous Catheters Market Country Insights
Based on region, the Latin America intravenous catheters market is further segmented into Mexico, Brazil, Argentina, Peru, Chile, and Colombia. Brazil held the largest share in 2024.
Brazil’s dense hospital landscape and oncology expansion underpin multi-lumen utilization, while teaching hospitals lead coated adoption tied to infection metrics. Mexico’s mixed public-private system scales peripheral volumes in IMSS and ISSSTE networks, with urban tertiary centers piloting coated lines under outcome-linked procurement. Chile’s accreditation culture and specialty concentration favour coated catheters, while integrated private systems extend outpatient infusions. Colombia’s insurer-driven networks grow ambulatory suites, pushing peripheral demand and structured training mandates that lift catheter performance. Argentina balances affordability with quality benchmarks in capital-region hospitals, adopting coated ranges for extended dwell and complex therapies. Peru invest in tertiary capacity and ICU modernization, incrementally expanding multi-lumen use. Logistics and reimbursement heterogeneity necessitate country-specific strategies: robust consignment and training for Brazil’s large systems, payer engagement for Colombia, and tender fluency for Mexico’s public institutions. Cross-border harmonization of product codes and documentation eases regional supply. Clinician champions, proof-of-outcomes, and guaranteed replenishment are decisive in tenders. Sustainability preferences are emerging in Brazil and Chile, nudging packaging optimization. Across markets, differentiation rests on infection performance, dwell durability, ergonomic insertion, and dependable support infrastructure aligning with national priorities and operational realities.
Latin America Intravenous Catheters Market Company Profiles
Mediplus India Ltd, Boston Scientific Corp, Becton Dickinson and Co, Teleflex Inc, B Braun SE, Sterimed Medical Devices Pvt Ltd, Terumo Corp, Angiplast, Cook Medical Holdings LLC, ICU Medical Inc, are among the key players operating in the market. These players adopt strategies such as expansion, product innovation, and mergers and acquisitions to stay competitive in the market and offer innovative products to their consumers.
Latin America Intravenous Catheters Market Research Methodology:
The following methodology has been followed for the collection and analysis of data presented in this report:
-
Secondary Research
The research process begins with comprehensive secondary research, utilizing both internal and external sources to gather qualitative and quantitative data for each market. Commonly referenced secondary research sources include, but are not limited to:
- Company websites, annual reports, financial statements, broker analyses, and investor presentations
- Industry trade journals and other relevant publications
- Government documents, statistical databases, and market reports
- News articles, press releases, and webcasts specific to companies operating in the market
Note: All financial data included in the Company Profiles section has been standardized to US$. For companies reporting in other currencies, figures have been converted to US$ using the relevant exchange rates for the corresponding year.
-
Primary Research
Business Market Insights conducts a significant number of primary interviews each year with industry stakeholders and experts to validate and analyze the data and gain valuable insights. These research interviews are designed to:
- Refine findings from secondary research
- Enhance the expertise and market understanding of the analysis team
- Gain insights into market size, trends, growth patterns, competitive dynamics, and future prospects
Primary research is conducted via email interactions and telephone interviews with industry experts across various markets, categories, segments, and sub-segments in different regions. Participants typically include:
- Industry stakeholders: Vice Presidents, business development managers, market intelligence managers, and national sales managers
- External experts: Valuation specialists, research analysts, and key opinion leaders with industry-specific expertise
Key Sources Referred:
- World Health Organization (WHO)
- World Heart Federation (WHF)
- Organisation for Economic Cooperation and Development (OECD)
- The World Bank Group
- Worldometer
- The Lancet
- International Bar Association
- International Trade Administration
- Eurostat
Latin America Intravenous Catheters Market Strategic Insights
Latin America Intravenous CathetersMarket Report Highlights
| Report Attribute | Details |
| Market size in 2024 | US$ 1,158.3 Million |
| Market Size by 2033 | US$ 2,153.8 Million |
| CAGR (2025 - 2033) | 7.1% |
| Historical Data | 2022-2023 |
| Forecast period | 2025-2033 |
| Segments Covered |
By Product
|
|
Regions and Countries Covered
|
|
| Latin America | Mexico, Brazil, Argentina, Peru, Chile, Colombia |
| Market leaders and key company profiles |
|
Latin America Intravenous Catheters Market Country and Regional Insights