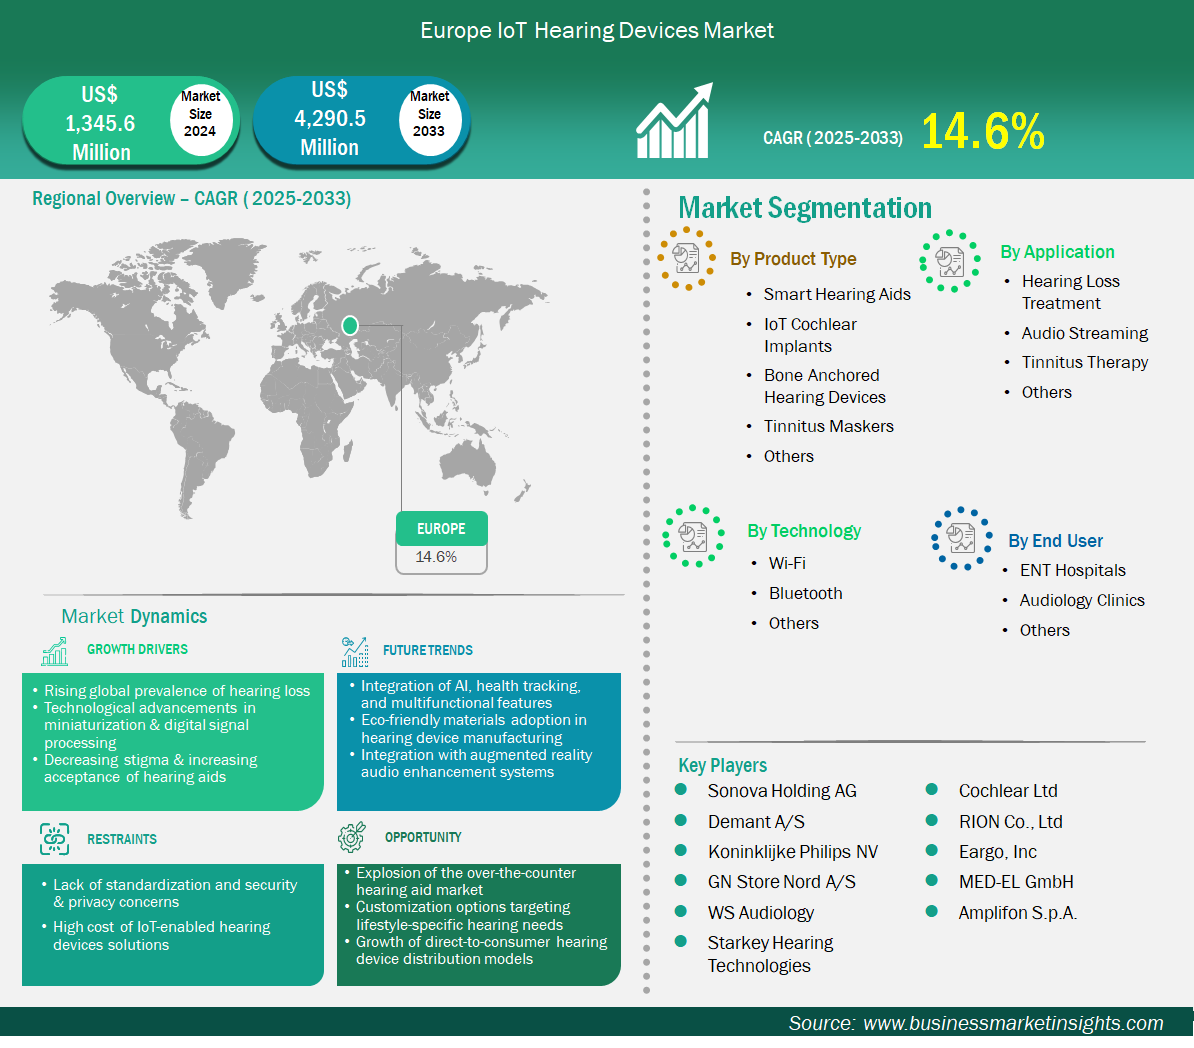
The Europe IoT hearing devices market size is expected to reach US$ 4,290.5 million by 2033 from US$ 1,345.6 million in 2024. The market is estimated to record a CAGR of 14.6% from 2025 to 2033.
Executive Summary and Europe IoT Hearing Devices Market Analysis:
The IoT hearing devices market in Europe is experiencing significant growth driven by the rising global prevalence of hearing loss, technological advancements in miniaturization & digital signal processing, decreasing stigma & increasing acceptance of hearing aids. Europe’s IoT hearing devices market is defined by regulatory rigor, demographic demand, and technological sophistication. The region benefits from mature healthcare systems and a rapidly aging population, creating strong demand for connected hearing solutions. Smart hearing aids dominate, supported by EU MDR regulations that emphasize device safety, interoperability, and digital integration. Market analysis shows Western Europe leading adoption, with Germany, France, and the UK investing heavily in IoT-enabled audiology programs. Eastern Europe is gradually scaling through government-backed e‑health initiatives. Competitive dynamics are shaped by European manufacturers such as GN Hearing and Widex, alongside global players expanding through partnerships with local distributors. Multifunctional devices that combine hearing support with audio streaming and health monitoring are gaining traction, reflecting Europe’s appetite for integrated digital health solutions.
Europe IoT Hearing Devices Market Segmentation Analysis:
Key segments that contributed to the derivation of the IoT hearing devices market analysis are product, technology, application, and end user.
- By product, the IoT hearing devices market is segmented into smart hearing aids, IoT cochlear implants, bone anchored hearing devices, tinnitus maskers, and others. Smart hearing aids dominated the market in 2024, driven by aging demographics, strong reimbursement, and advanced audiology ecosystems.
- By technology, the IoT hearing devices market is segmented into Wi-Fi, Bluetooth, and others. Bluetooth dominated the market in 2024, driven by standardized interoperability with smartphones and EU compliance requirements.
- In terms of application, the market is segmented into hearing loss treatment, audio streaming, tinnitus therapy, and others. Hearing loss treatment dominated the market in 2024, driven by mature care pathways and widespread clinical adoption across national health systems.
- By end user, the market is segmented into ENT hospitals, audiology clinics, and others. Audiology clinics dominated the market in 2024, driven by dense specialist networks delivering fitting, programming, and ongoing remote care.
Europe IoT Hearing Devices Market Outlook
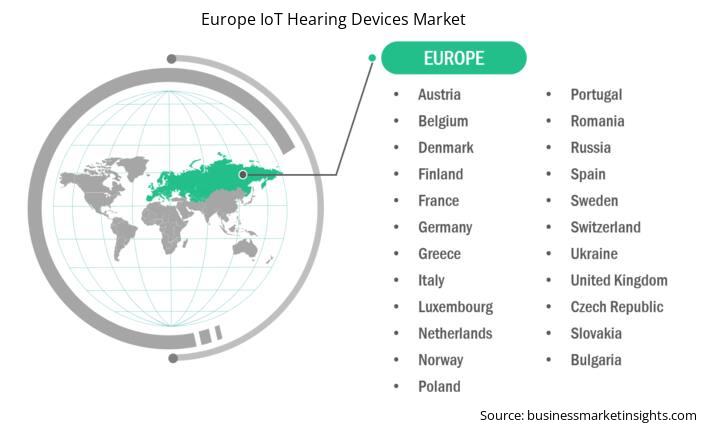
The Europe IoT hearing devices market is segmented into Belgium, Austria, Finland, Denmark, Greece, Poland, Romania, Russia, Ukraine, the Czech Republic, Slovakia, Bulgaria, Italy, Luxembourg, Germany, Switzerland, France, the Netherlands, Norway, Portugal, Spain, Sweden, and the United Kingdom. The outlook for Europe’s IoT hearing devices market is robust, supported by demographic shifts, regulatory compliance, and technological innovation. The EU MDR regulations are accelerating adoption by ensuring device safety and interoperability, while digital health policies promote tele‑audiology and remote monitoring. Private insurers and public health systems increasingly recognize the cost‑effectiveness of IoT hearing devices, particularly in reducing long‑term treatment costs and improving patient satisfaction. Strategic collaborations between device manufacturers and telecom operators are expected to expand access, leveraging Europe’s advanced mobile infrastructure. Premium product categories will dominate in Western Europe, where disposable incomes and healthcare infrastructure are strong, while affordable IoT hearing aids tailored for middle‑income consumers will expand reach in Eastern Europe. The outlook also suggests growing demand for multifunctional devices that combine hearing support with lifestyle features such as streaming and health tracking. As Europe continues to prioritize digital health transformation, IoT hearing devices are positioned as a cornerstone of the region’s evolving healthcare ecosystem. The market outlook points to sustained growth, with IoT hearing devices playing a critical role in addressing the needs of aging populations, improving patient outcomes, and reducing healthcare costs across Europe.
Europe IoT Hearing Devices Market Country Insights
Based on region, the Europe IoT hearing devices market is further segmented into Belgium, Austria, Finland, Denmark, Greece, Poland, Romania, Russia, Ukraine, the Czech Republic, Slovakia, Bulgaria, Italy, Luxembourg, Germany, Switzerland, France, the Netherlands, Norway, Portugal, Spain, Sweden, and the United Kingdom. Germany held the largest share in 2024.
Country‑level insights reveal significant diversity in adoption patterns across Europe, reflecting differences in healthcare infrastructure, income levels, and regulatory frameworks. Germany leads Europe with strong audiology infrastructure and government support for IoT cochlear implants. France emphasizes integration of IoT hearing aids into national health strategies, while the UK benefits from NHS pilot programs expanding access to connected devices. Nordic countries are early adopters of tele‑audiology, leveraging digital platforms to deliver care to remote populations. Eastern Europe, including Poland, is gradually scaling adoption through EU‑funded initiatives. Country insights highlight Western Europe’s dominance in premium adoption, while Eastern Europe represents growth opportunities, underscoring the importance of localized strategies tailored to diverse healthcare systems.
Europe IoT Hearing Devices Market Company Profiles
Sonova Holding AG, Demant A/S, Koninklijke Philips NV, GN Store Nord A/S, WS Audiology, Starkey Hearing Technologies, Cochlear Ltd., RION Co., Ltd., Eargo, Inc., MED-EL GmbH, Amplifon S.p.A., are among the key players operating in the market. These players adopt strategies such as expansion, product innovation, and mergers and acquisitions to stay competitive in the market and offer innovative products to their consumers.
Europe IoT Hearing Devices Market Research Methodology:
The following methodology has been followed for the collection and analysis of data presented in this report:
-
Secondary Research
The research process begins with comprehensive secondary research, utilizing both internal and external sources to gather qualitative and quantitative data for each market. Commonly referenced secondary research sources include, but are not limited to:
- Company websites, annual reports, financial statements, broker analyses, and investor presentations
- Industry trade journals and other relevant publications
- Government documents, statistical databases, and market reports
- News articles, press releases, and webcasts specific to companies operating in the market
Note: All financial data included in the Company Profiles section has been standardized to US$. For companies reporting in other currencies, figures have been converted to US$ using the relevant exchange rates for the corresponding year.
-
Primary Research
Business Market Insights conducts a significant number of primary interviews each year with industry stakeholders and experts to validate and analyze the data and gain valuable insights. These research interviews are designed to:
- Refine findings from secondary research
- Enhance the expertise and market understanding of the analysis team
- Gain insights into market size, trends, growth patterns, competitive dynamics, and future prospects
Primary research is conducted via email interactions and telephone interviews with industry experts across various markets, categories, segments, and sub-segments in different regions. Participants typically include:
- Industry stakeholders: Vice Presidents, business development managers, market intelligence managers, and national sales managers
- External experts: Valuation specialists, research analysts, and key opinion leaders with industry-specific expertise
Key Sources Referred:
- World Health Organization (WHO)
- Organisation for Economic Cooperation and Development (OECD)
- The World Bank Group
- Worldometer
- The Lancet
- International Bar Association
- International Trade Administration
- Eurostat
- United Nations Department of Economic and Social Affairs
Europe IoT Hearing Devices Market Strategic Insights
Europe IoT Hearing DevicesMarket Report Highlights
| Report Attribute | Details |
| Market size in 2024 | US$ 1,345.6 Million |
| Market Size by 2033 | US$ 4,290.5 Million |
| CAGR (2025 - 2033) | 14.6% |
| Historical Data | 2022-2023 |
| Forecast period | 2025-2033 |
| Segments Covered |
By Product
|
|
Regions and Countries Covered
|
|
| Europe | Germany, Italy, France, United Kingdom, Spain, Belgium, Netherlands, Luxembourg, Norway, Finland, Denmark, Sweden, Switzerland, Austria, Greece, Portugal, Russia, Poland, Romania, Czech Republic, Ukraine, Slovakia, Bulgaria |
| Market leaders and key company profiles |
|
Europe IoT Hearing Devices Market Country and Regional Insights