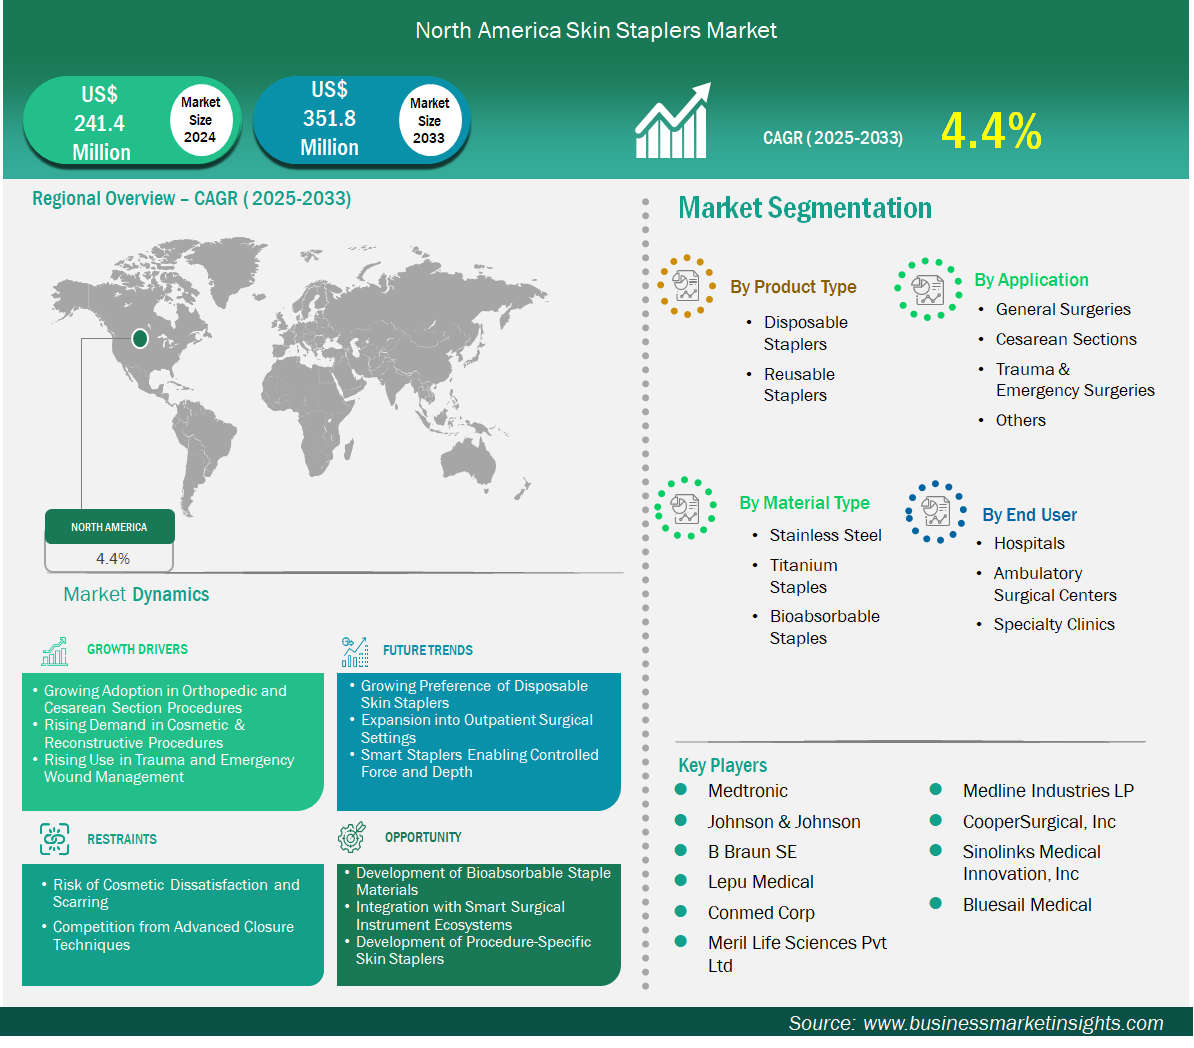
The North America skin staplers market size is expected to reach US$ 351.8 million by 2033 from US$ 241.4 million in 2024. The market is estimated to record a CAGR of 4.4% from 2025 to 2033.
Executive Summary and North America Skin Staplers Market Analysis:
The North America skin staplers market is highly developed, supported by advanced healthcare systems and widespread adoption of innovative surgical technologies. Hospitals and surgical centers across the region prioritize efficiency, patient safety, and infection control, creating strong demand for modern wound closure devices. The market benefits from robust R&D investments and rapid integration of powered and disposable staplers into surgical workflows. Private healthcare providers and outpatient centers are key contributors to growth, while public institutions maintain high standards for device procurement. Despite strong adoption, challenges such as high device costs and stringent regulatory compliance can slow product introductions. Overall, North America remains a global leader in surgical innovation, with skin staplers playing a critical role in enhancing operative efficiency and improving recovery outcomes across diverse surgical specialties, including bariatric, orthopedic, and cosmetic procedures.
North America Skin Staplers Market Segmentation Analysis:
Key segments that contributed to the derivation of the skin staplers market analysis are product type, material type, application, and end user.
- By product type, the skin staplers market is segmented into disposable staplers and reusable staplers. The disposable staplers segment dominated the market in 2024. Disposable skin staplers are predominantly preferred for superior infection control, pre-sterilization, convenience, and rapid wound closure in diverse clinical settings.
- By material type, the skin staplers market is segmented into stainless steel, titanium staples, and bioabsorbable staples. The stainless steel segment dominated the market in 2024. Stainless steel staples are widely used due to their strength, biocompatibility, cost-effectiveness, and reliable performance in general wound closure.
- By application, the skin staplers market is segmented into general surgery, cesarean sections, trauma & emergency surgeries, and others. The general surgery segment dominated the market in 2024. Skin staplers are broadly used for quick and efficient wound closure across a vast number of routine and complex general surgical procedures, making this the largest application.
- By end user, the market is segmented into hospitals, ambulatory surgical centers, and specialty clinics. The hospitals segment held the largest share of the market in 2024. Hospitals perform the vast majority of complex and high-volume surgical procedures across diverse specialties, making them the largest consumers of skin staplers.
North America Skin Staplers Market Outlook
The North America skin staplers market reflects a strong preference for advanced wound closure solutions that improve surgical precision and reduce complications. Hospitals increasingly favor staplers over traditional sutures for their ability to minimize operative time and enhance patient recovery. A major driver is the rise in outpatient and ambulatory surgeries, fueled by healthcare cost containment and patient demand for shorter hospital stays. These procedures require efficient closure tools that ensure safety and speed, making staplers indispensable in same-day surgical environments. Manufacturers are responding with ergonomic, disposable staplers designed for quick turnaround and compliance with infection control protocols. This trend is reinforced by technological advancements and surgeon training programs, positioning skin staplers as a cornerstone of modern surgical care. As outpatient volumes grow, demand for staplers continues to rise, shaping North America’s surgical landscape toward efficiency and innovation.
North America Skin Staplers Market Country Insights
Based on country, the North America skin staplers market is further segmented into the United States, Canada and Mexico. The United States held the largest share in 2024.
The United States dominates the North America skin staplers market, driven by its advanced healthcare infrastructure and high surgical volumes. Hospitals and ambulatory centers are early adopters of powered and disposable staplers, which offer precision and reduce infection risks. Rising demand for minimally invasive procedures in bariatric, orthopedic, and cosmetic surgeries has accelerated adoption of staplers as essential wound closure tools. Strong regulatory frameworks ensure product quality and safety, while reimbursement policies support the use of advanced devices in surgical care. Leading manufacturers collaborate with U.S. healthcare institutions to introduce innovative stapling technologies and provide surgeon training programs. While cost pressures persist in smaller facilities, urban hospitals and specialty centers set benchmarks for surgical efficiency and patient outcomes. The U.S. continues to lead global innovation in wound closure practices, reinforcing its position as a key driver of market growth.
North America Skin Staplers Market Company Profiles
North America Skin Staplers Market Research Methodology:
The following methodology has been followed for the collection and analysis of data presented in this report:
Secondary Research
The research process begins with comprehensive secondary research, utilizing both internal and external sources to gather qualitative and quantitative data for each market. Commonly referenced secondary research sources include, but are not limited to:
- Company websites, annual reports, financial statements, broker analyses, and investor presentations
- Industry trade journals and other relevant publications
- Government documents, statistical databases, and market reports
- News articles, press releases, and webcasts specific to companies operating in the market
Note: All financial data included in the Company Profiles section has been standardized to US$. For companies reporting in other currencies, figures have been converted to US$ using the relevant exchange rates for the corresponding year.
Primary Research
Business Market Insights conducts a significant number of primary interviews each year with industry stakeholders and experts to validate and analyze the data and gain valuable insights. These research interviews are designed to:
- Refine findings from secondary research
- Enhance the expertise and market understanding of the analysis team
- Gain insights into market size, trends, growth patterns, competitive dynamics, and future prospects
Primary research is conducted via email interactions and telephone interviews with industry experts across various markets, categories, segments, and sub-segments in different regions. Participants typically include:
- Industry stakeholders: Vice Presidents, business development managers, market intelligence managers, and national sales managers
- External experts: Valuation specialists, research analysts, and key opinion leaders with industry-specific expertise
Key Sources Referred:
- The World Bank
- World Health Organization (WHO)
- Center for Disease Control and Prevention (CDC)
- Wound Healing Society (WHS)
- The Interprofessional Wound Care Association (IWCA)
- European Wound Management Association
- Company website
- Company annual reports
- Company investor presentations
North America Skin Staplers Market Strategic Insights
North America Skin StaplersMarket Report Highlights
| Report Attribute | Details |
| Market size in 2024 | US$ 241.4 Million |
| Market Size by 2033 | US$ 351.8 Million |
| CAGR (2025 - 2033) | 4.4% |
| Historical Data | 2022-2023 |
| Forecast period | 2025-2033 |
| Segments Covered |
By Product Type
|
|
Regions and Countries Covered
|
|
| North America | US, Canada, Mexico |
| Market leaders and key company profiles |
|
North America Skin Staplers Market Country and Regional Insights