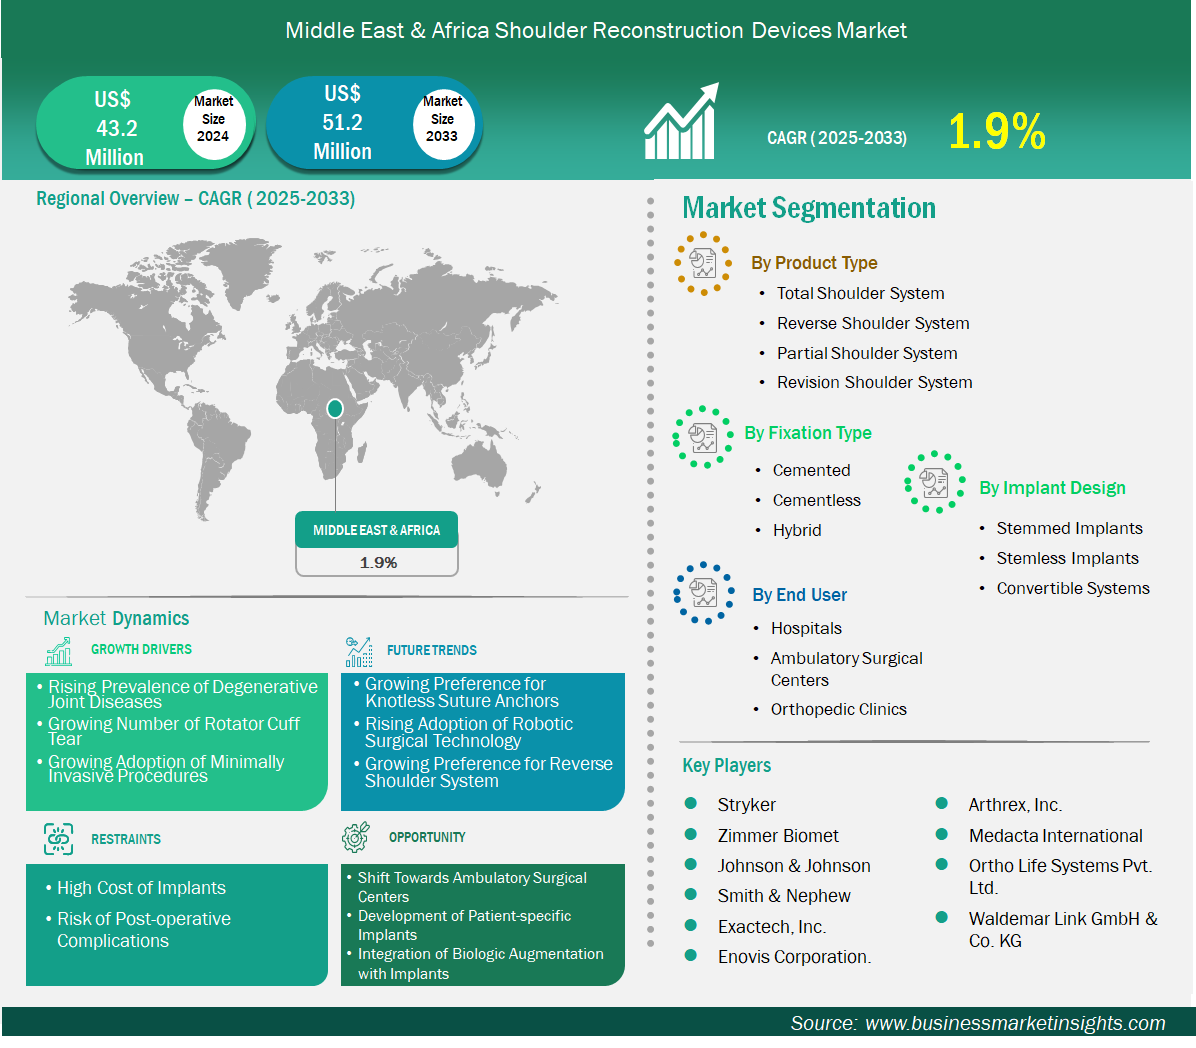
The Middle East and Africa shoulder reconstruction devices market size is expected to reach US$ 51.2 million by 2033 from US$ 43.2 million in 2024. The market is estimated to record a CAGR of 1.9% from 2025 to 2033.
Executive Summary and Middle East and Africa Shoulder Reconstruction Devices Market Analysis:
The Middle East and Africa shoulder reconstruction devices market is transforming as healthcare systems get upgraded and more people have access to advanced orthopedic care. The growing incidences of shoulder injuries, arthritis, and trauma-related disorders are major factors leading to the increase in demand for suitable reconstruction solutions. Hospitals across key countries are expanding orthopedic units and incorporating minimally invasive techniques to enhance patient outcomes. Growth is largely supported by public and private sector investments in surgical technology and medical training. While Africa faces challenges such as limited specialist availability and uneven healthcare access, Middle Eastern nations, particularly Saudi Arabia, are leading market progress. The region overall shows promising momentum toward advanced joint care, supported by growing awareness of post-surgical recovery benefits and quality-of-life improvements.
Middle East and Africa Shoulder Reconstruction Devices Market Segmentation Analysis:
Key segments that contributed to the derivation of the shoulder reconstruction devices market analysis are product type, fixation type, implant design, and end user.
- By product type, the shoulder reconstruction devices market is segmented into total shoulder system, reverse shoulder system, partial shoulder system, and revision shoulder system. The reverse shoulder system segment dominated the market in 2024. Its ability to restore function in rotator cuff-deficient shoulders and growing elderly population made it the preferred choice. Surgeons favor it for complex cases due to better stability and outcomes.
- By fixation type, the shoulder reconstruction devices market is segmented into cemented, cementless, and hybrid. The cementless segment dominated the market in 2024. Rising demand for biologic integration and reduced surgical time contributed to its dominance. It also lowers the risk of cement-related complications.
- By implant design, the market is segmented into stemmed implants, stemless implants, and convertible systems. The stemless implants segment dominated the market in 2024. Their bone-preserving design and ease of implantation led to increased adoption. They’re especially suitable for younger, active patients.
- By end user, the market is segmented into hospitals, ambulatory surgical centers, and orthopedic clinics. The hospitals segment held the largest share of the market in 2024. Equipped with advanced surgical facilities and specialized staff, hospitals handle the majority of shoulder reconstruction procedures. Their capacity for post-operative care also attracts more patients.
Middle East and Africa Shoulder Reconstruction Devices Market Outlook
The market is shifting from the standard open surgeries towards more advanced arthroscopic and implant-based reconstruction techniques. One of the main reasons for this is the rising trend of early intervention and functional restoration after a shoulder injury, which is a common scenario among the working-age and athletic populations. The growing number of highly specialized orthopedic centers, along with enhanced diagnostic capabilities, is making it possible to achieve accurate and successful surgical results. Collaborations on a global scale are also facilitating the acquisition of skills in reverse and anatomic shoulder replacement procedures for surgeons in different parts of the region. Moreover, healthcare modernization programs funded by the government and the involvement of international device manufacturers are expanding access to top-notch implants and surgical systems in the Middle East as well as Africa.
Middle East and Africa Shoulder Reconstruction Devices Market Country Insights
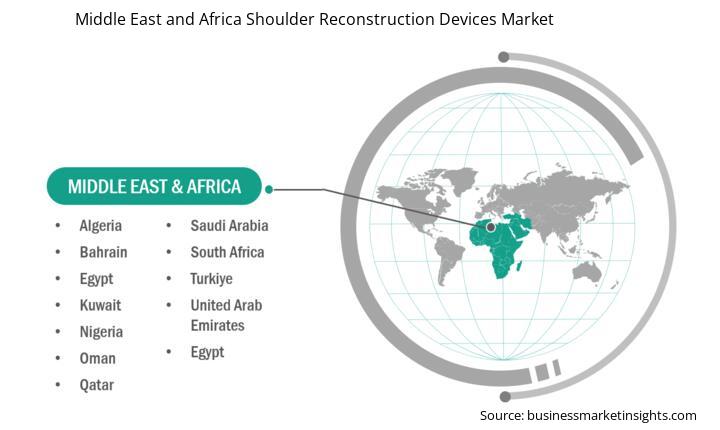
Based on country, the Middle East and Africa shoulder reconstruction devices Market is segmented into Saudi Arabia, the United Arab Emirates, Kuwait, Bahrain, Qatar, Oman, Turkiye, South Africa, Egypt, Nigeria, Algeria, and the Rest of MEA. Saudi Arabia held the largest share in 2024.
Saudi Arabia dominates the Middle East and Africa shoulder reconstruction devices market due to its state-of-the-art healthcare facilities and the continuous investments made as per Vision 2030. Major hospitals in Riyadh, Jeddah, and Dammam have evolved into the regional hubs for orthopedic surgeries, being well-equipped with the latest technology and staffed with highly-skilled specialists. The government's emphasis on expanding specialized medical centers and instituting training programs has strengthened local surgical expertise. Private hospitals are progressively adventuring in the introduction of robotic-assisted and patient-specific reconstruction methods to not only enhance the results but also to attract medical tourists. Meanwhile, local distributors are working with international manufacturers to ensure steady implant availability and technical support. Thus, the rising focus on healthcare innovation, and growing awareness regarding early joint disorder detection will maintain Saudi Arabia as a leading market for shoulder reconstruction devices in the Middle East and Africa region.
Middle East and Africa Shoulder Reconstruction Devices Market Company Profiles
Stryker, Zimmer Biomet, Johnson & Johnson, Smith & Nephew, Exactech, Inc., Enovis Corporation, Arthrex, Inc., Medacta International, Ortho Life Systems Pvt. Ltd., and Waldemar Link GmbH & Co. KG are among the key players operating in the market. These players adopt strategies such as expansion, product innovation, and mergers and acquisitions to stay competitive in the market and offer innovative products to their consumers.
Middle East and Africa Shoulder Reconstruction Devices Market Research Methodology:
The following methodology has been followed for the collection and analysis of data presented in this report:
Secondary Research
The research process begins with comprehensive secondary research, utilizing both internal and external sources to gather qualitative and quantitative data for each market. Commonly referenced secondary research sources include, but are not limited to:
- Company websites, annual reports, financial statements, broker analyses, and investor presentations
- Industry trade journals and other relevant publications
- Government documents, statistical databases, and market reports
- News articles, press releases, and webcasts specific to companies operating in the market
Note: All financial data included in the Company Profiles section has been standardized to US$. For companies reporting in other currencies, figures have been converted to US$ using the relevant exchange rates for the corresponding year.
Primary Research
Business Market Insights conducts a significant number of primary interviews each year with industry stakeholders and experts to validate and analyze the data and gain valuable insights. These research interviews are designed to:
- Refine findings from secondary research
- Enhance the expertise and market understanding of the analysis team
- Gain insights into market size, trends, growth patterns, competitive dynamics, and future prospects
Primary research is conducted via email interactions and telephone interviews with industry experts across various markets, categories, segments, and sub-segments in different regions. Participants typically include:
- Industry stakeholders: Vice Presidents, business development managers, market intelligence managers, and national sales managers
- External experts: Valuation specialists, research analysts, and key opinion leaders with industry-specific expertise
Key Sources Referred:
- The World Bank
- World Health Organization (WHO)
- Center for Disease Control and Prevention (CDC)
- American Academy of Orthopedic Surgeons
- American Orthopedic Association
- The World Orthopedic Organization
- Company website
- Company annual reports
- Company investor presentations
Middle East and Africa Shoulder Reconstruction Devices Market Strategic Insights
Middle East and Africa Shoulder Reconstruction DevicesMarket Report Highlights
| Report Attribute | Details |
| Market size in 2024 | US$ 43.2 Million |
| Market Size by 2033 | US$ 51.2 Million |
| CAGR (2025 - 2033) | 1.9% |
| Historical Data | 2022-2023 |
| Forecast period | 2025-2033 |
| Segments Covered |
By Product Type
|
|
Regions and Countries Covered
|
|
| Middle East and Africa | Saudi Arabia, United Arab Emirates, Kuwait, Bahrain, Qatar, Oman, Turkiye, South Africa, Egypt, Nigeria, Algeria |
| Market leaders and key company profiles |
|
Middle East and Africa Shoulder Reconstruction Devices Market Country and Regional Insights