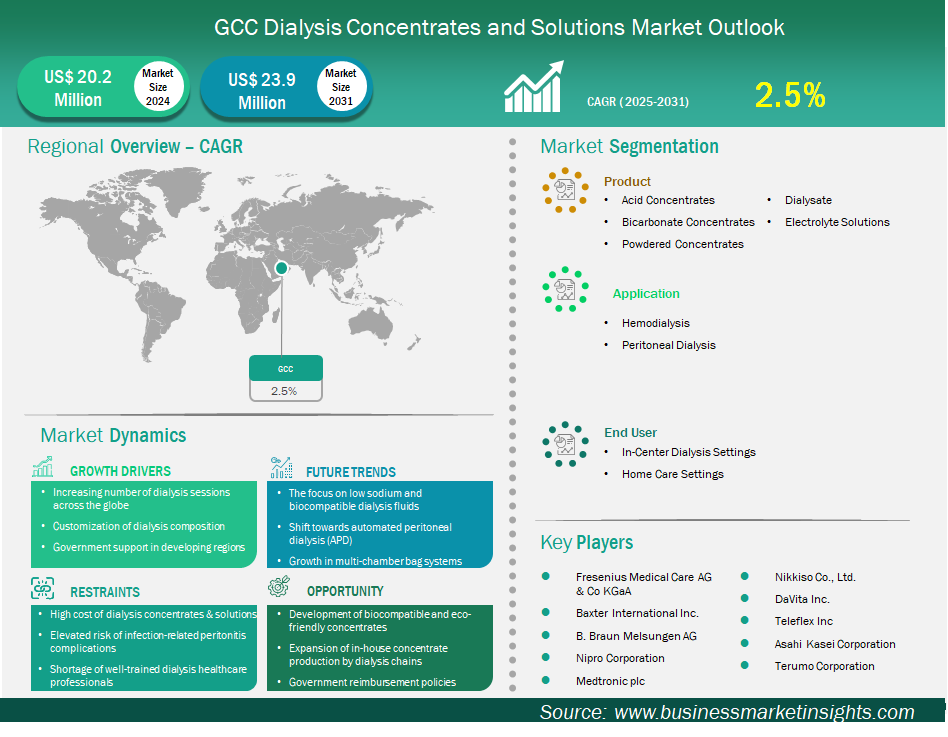
The GCC dialysis concentrates and solutions market size is expected to reach US$ 23.9 million by 2031 from US$ 20.2 million in 2024. The market is estimated to record a CAGR of 2.5% from 2025 to 2031.
Executive Summary and GCC Dialysis Concentrates and Solutions Market Analysis:
The GCC dialysis concentrates and solutions market is experiencing strong growth, driven by rising dialysis sessions, increasing customization of treatment compositions, and government-backed initiatives in emerging regions. The GCC represents a high-growth market supported by substantial government investment and a high prevalence of risk factors such as diabetes and hypertension. The region benefits from strong funding and advanced medical technologies. Countries like Saudi Arabia and the UAE are rapidly expanding dialysis services and facilities. A large patient population requiring dialysis, combined with significant investment in advanced, high-quality healthcare services, is fueling demand for in-center hemodialysis consumables. International players view the GCC as highly attractive due to strong purchasing power and supportive government policies focused on healthcare infrastructure development and addressing the growing burden of non-communicable diseases.
GCC Dialysis Concentrates and Solutions Market Segmentation Analysis:
Key segments that contributed to the derivation of the dialysis concentrates and solutions market analysis are product, application, and end user.
- By product, the dialysis concentrates and solutions market is segmented into acid concentrates, bicarbonate concentrates, powdered concentrates, dialysate, and electrolyte solutions. Acid concentrates dominated the market in 2024, driven by their critical role and high-volume utilization as a core component in hemodialysis, which is the predominant treatment modality across the region.
- In terms of application, the market is segmented into hemodialysis and peritoneal dialysis. Hemodialysis accounted for a larger share in 2024, driven by its long-standing position as the primary treatment for end-stage renal disease (ESRD). This dominance is supported by a substantial patient base and well-established, publicly funded clinical infrastructure across GCC countries.
- By end user, the market is segmented into in-center dialysis settings and home care settings. In-center dialysis dominated the market in 2024, driven by the high prevalence of advanced-stage patients with comorbidities requiring continuous medical supervision. Limited infrastructure and inadequate patient training for home-based care in many parts of the region further reinforce this segment’s leadership.
GCC Dialysis Concentrates and Solutions Market Outlook
The GCC dialysis concentrates and solutions market is set for strong expansion, driven by innovation and a growing focus on patient-centric care. While in-center hemodialysis will remain dominant, the market is clearly shifting toward decentralized care through home-based dialysis, particularly peritoneal dialysis (PD). This transition aims to enhance patient autonomy and quality of life while optimizing healthcare resources. The market is expected to see an influx of home-friendly solutions, including portable dialysis machines and easy-to-use solution bags. Additionally, the GCC is an attractive target for companies offering advanced biocompatible dialysate formulations designed to reduce long-term complications. Future growth will be fueled by sustained government investment in healthcare infrastructure, increased adoption of telehealth and digital health technologies, and a strategic shift toward preventive care to address underlying causes of kidney disease.
GCC Dialysis Concentrates and Solutions Market Country Insights
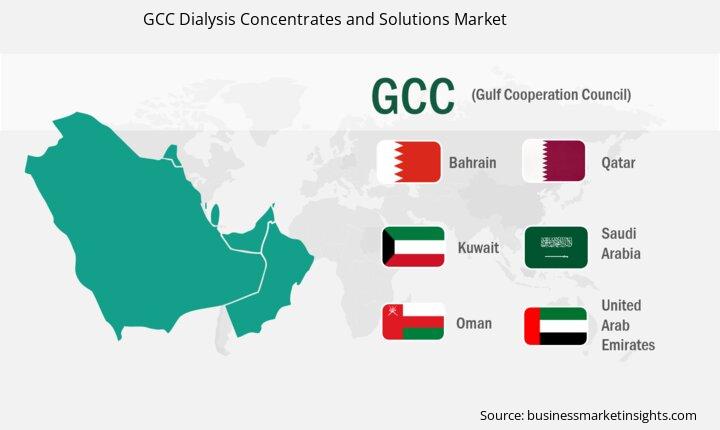
Based on country, the GCC dialysis concentrates and solutions market is segmented into the United Arab Emirates, Bahrain, Saudi Arabia, Oman, Qatar, and Kuwait. Saudi Arabia held the largest share in 2024.
The GCC dialysis concentrates and solutions market exhibits distinct characteristics across member countries. Saudi Arabia, the region’s largest economy and population base, is the leading market for dialysis products. Growth is driven by substantial government healthcare spending and a large patient population. The country is also the primary source of new dialysis clinic openings and an early adopter of advanced dialysis technologies. The UAE, the GCC’s business and medical tourism hub, represents a sophisticated, quality-driven market. It has a high density of private clinics and serves as a premium market for ready-to-use dialysis solutions. Qatar and Kuwait boast high per capita income but relatively small patient populations. Both countries will continue investing in state-of-the-art dialysis care, emphasizing patient comfort, convenience, and tailored solutions aligned with national healthcare priorities.
GCC Dialysis Concentrates and Solutions Market Company Profiles
Fresenius Medical Care AG & Co KGaA; Baxter International Inc.; B. Braun SE; Nipro Corp; Medtronic Plc; Nikkiso Co., Ltd; Teleflex Inc; Asahi Kasei Medical Co., Ltd.; Terumo Corp; and DaVita Inc. are among the key players operating in the market. These players adopt strategies such as expansion, product innovation, and mergers and acquisitions to stay competitive in the market and offer innovative products to their consumers.
GCC Dialysis Concentrates and Solutions Market Research Methodology:
The following methodology has been followed for the collection and analysis of data presented in this report:
-
Secondary Research
The research process begins with comprehensive secondary research, utilizing both internal and external sources to gather qualitative and quantitative data for each market. Commonly referenced secondary research sources include, but are not limited to:
- Company websites, annual reports, financial statements, broker analyses, and investor presentations
- Industry trade journals and other relevant publications
- Government documents, statistical databases, and market reports
- News articles, press releases, and webcasts specific to companies operating in the market
Note: All financial data included in the Company Profiles section has been standardized to US$. For companies reporting in other currencies, figures have been converted to US$ using the relevant exchange rates for the corresponding year.
-
Primary Research
Business Market Insights conducts a significant number of primary interviews each year with industry stakeholders and experts to validate and analyze the data and gain valuable insights. These research interviews are designed to:
- Refine findings from secondary research
- Enhance the expertise and market understanding of the analysis team
- Gain insights into market size, trends, growth patterns, competitive dynamics, and future prospects
Primary research is conducted via email interactions and telephone interviews with industry experts across various markets, categories, segments, and sub-segments in different regions. Participants typically include:
- Industry stakeholders: Vice Presidents, business development managers, market intelligence managers, and national sales managers
- External experts: Valuation specialists, research analysts, and key opinion leaders with industry-specific expertise
Key Sources Referred:
- World Health Organization (WHO)
- United States Renal Data System (USRDS)
- The World Bank Group
- Worldometer
- The Lancet
- International Trade Administration
GCC Dialysis Concentrates and Solutions Market Strategic Insights
GCC Dialysis Concentrates and SolutionsMarket Report Highlights
| Report Attribute | Details |
| Market size in 2024 | US$ 20.2 Million |
| Market Size by 2031 | US$ 23.9 Million |
| CAGR (2025 - 2031) | 2.5% |
| Historical Data | 2021-2023 |
| Forecast period | 2025-2031 |
| Segments Covered |
By Product
|
|
Regions and Countries Covered
|
|
| GCC | United Arab Emirates, Bahrain, Saudi Arabia, Oman, Qatar, Kuwait |
| Market leaders and key company profiles |
|
GCC Dialysis Concentrates and Solutions Market Country and Regional Insights